Report
Highlight

Read as text
$RDY Dr. Reddy's September-quarter profit fell 36% to ₹925 Cr on lower lenalidomide sales, price erosion, higher SG&A and lower other income. 🏢 Dr. Reddy's Laboratories is a Hyderabad-based generic drug maker whose NYSE shares traded at $13.335 at 14:10 ET on October 23, 2026 📉 Profit attributable to shareholders for the September 2026 quarter fell 36% from a year earlier to ₹925 Cr, while revenue slipped just 1.5% to ₹8,671 Cr 📉 North America revenue fell 23% to ₹2,489 Cr on lower lenalidomide sales, and the company says the drop was 29% in dollar terms 📉 EBITDA margin fell to 20.6% from 26.7% and diluted EPS to ₹11.1 from ₹17.3, as price erosion and product mix cut gross margin while SG&A rose 6% and other income fell 66% 📈 Against that, profit roughly doubled from the June quarter, when EBITDA margin was 12.5% after a ₹240 Cr semaglutide provision, and India grew 17% and Emerging Markets 24% 🏦 The balance sheet is not the problem, since the company held a net cash surplus of ₹2,502 Cr at 30 September 2026 ⚠️ The US FDA issued Form 483 observations at four plants between July and October 2026, while the semaglutide API issue that drove the June-quarter provision is still being resolved 📅 Next: Dengue vaccine QDENGA is set to launch in India's private markets in the first half of 2027; watch the replies to the FDA Form 483s Source: SEC 6-Ks, Oct 23 (results deck + interim report)
Highlight
Read as text
$IONS Follow-up: Roche's sefaxersen cut IgA nephropathy proteinuria 43.1% vs placebo at 37 weeks. 🏢 Ionis Pharmaceuticals, an RNA-drug maker worth ~$7.12B ($42.84, 13:49 ET Oct 23, 2026), licensed kidney drug sefaxersen to Roche, and its September 23, 2026 8-K said only that the Phase 3 IMAgINATION study met its primary endpoint, with no effect size 📈 Roche's ASN Kidney Week 2026 data now put that effect at a 43.1% cut in proteinuria versus placebo at 37 weeks (95% CI 32.5-52.0, P<0.0001), on 24-hour urine protein-to-creatinine ratio 📈 The effect held in all prespecified subgroups, more patients with baseline blood in urine cleared it by Week 37, and Roche saw no new safety signals versus the Phase 2 study 🤝 Ionis already received an upfront payment, license fee and development milestones from Roche and is eligible for regulatory and sales milestones plus tiered royalties on any net sales, at undisclosed rates, so the data cannot be sized in dollars against its ~$7.12B market value ($42.84, 13:49 ET Oct 23, 2026) or $2.70B in cash and investments (June 30, 2026) ⚠️ The bear case is that a 37-week proteinuria drop is a stand-in measure, and the study stays blinded until kidney function (eGFR) is read at week 105 📅 Next: Roche will share the data with health authorities; the blinded study runs to an eGFR readout at week 105, and no filing date is given Source: SEC 8-K, Oct 23 + SEC 8-K, Sep 23
Highlight
Read as text
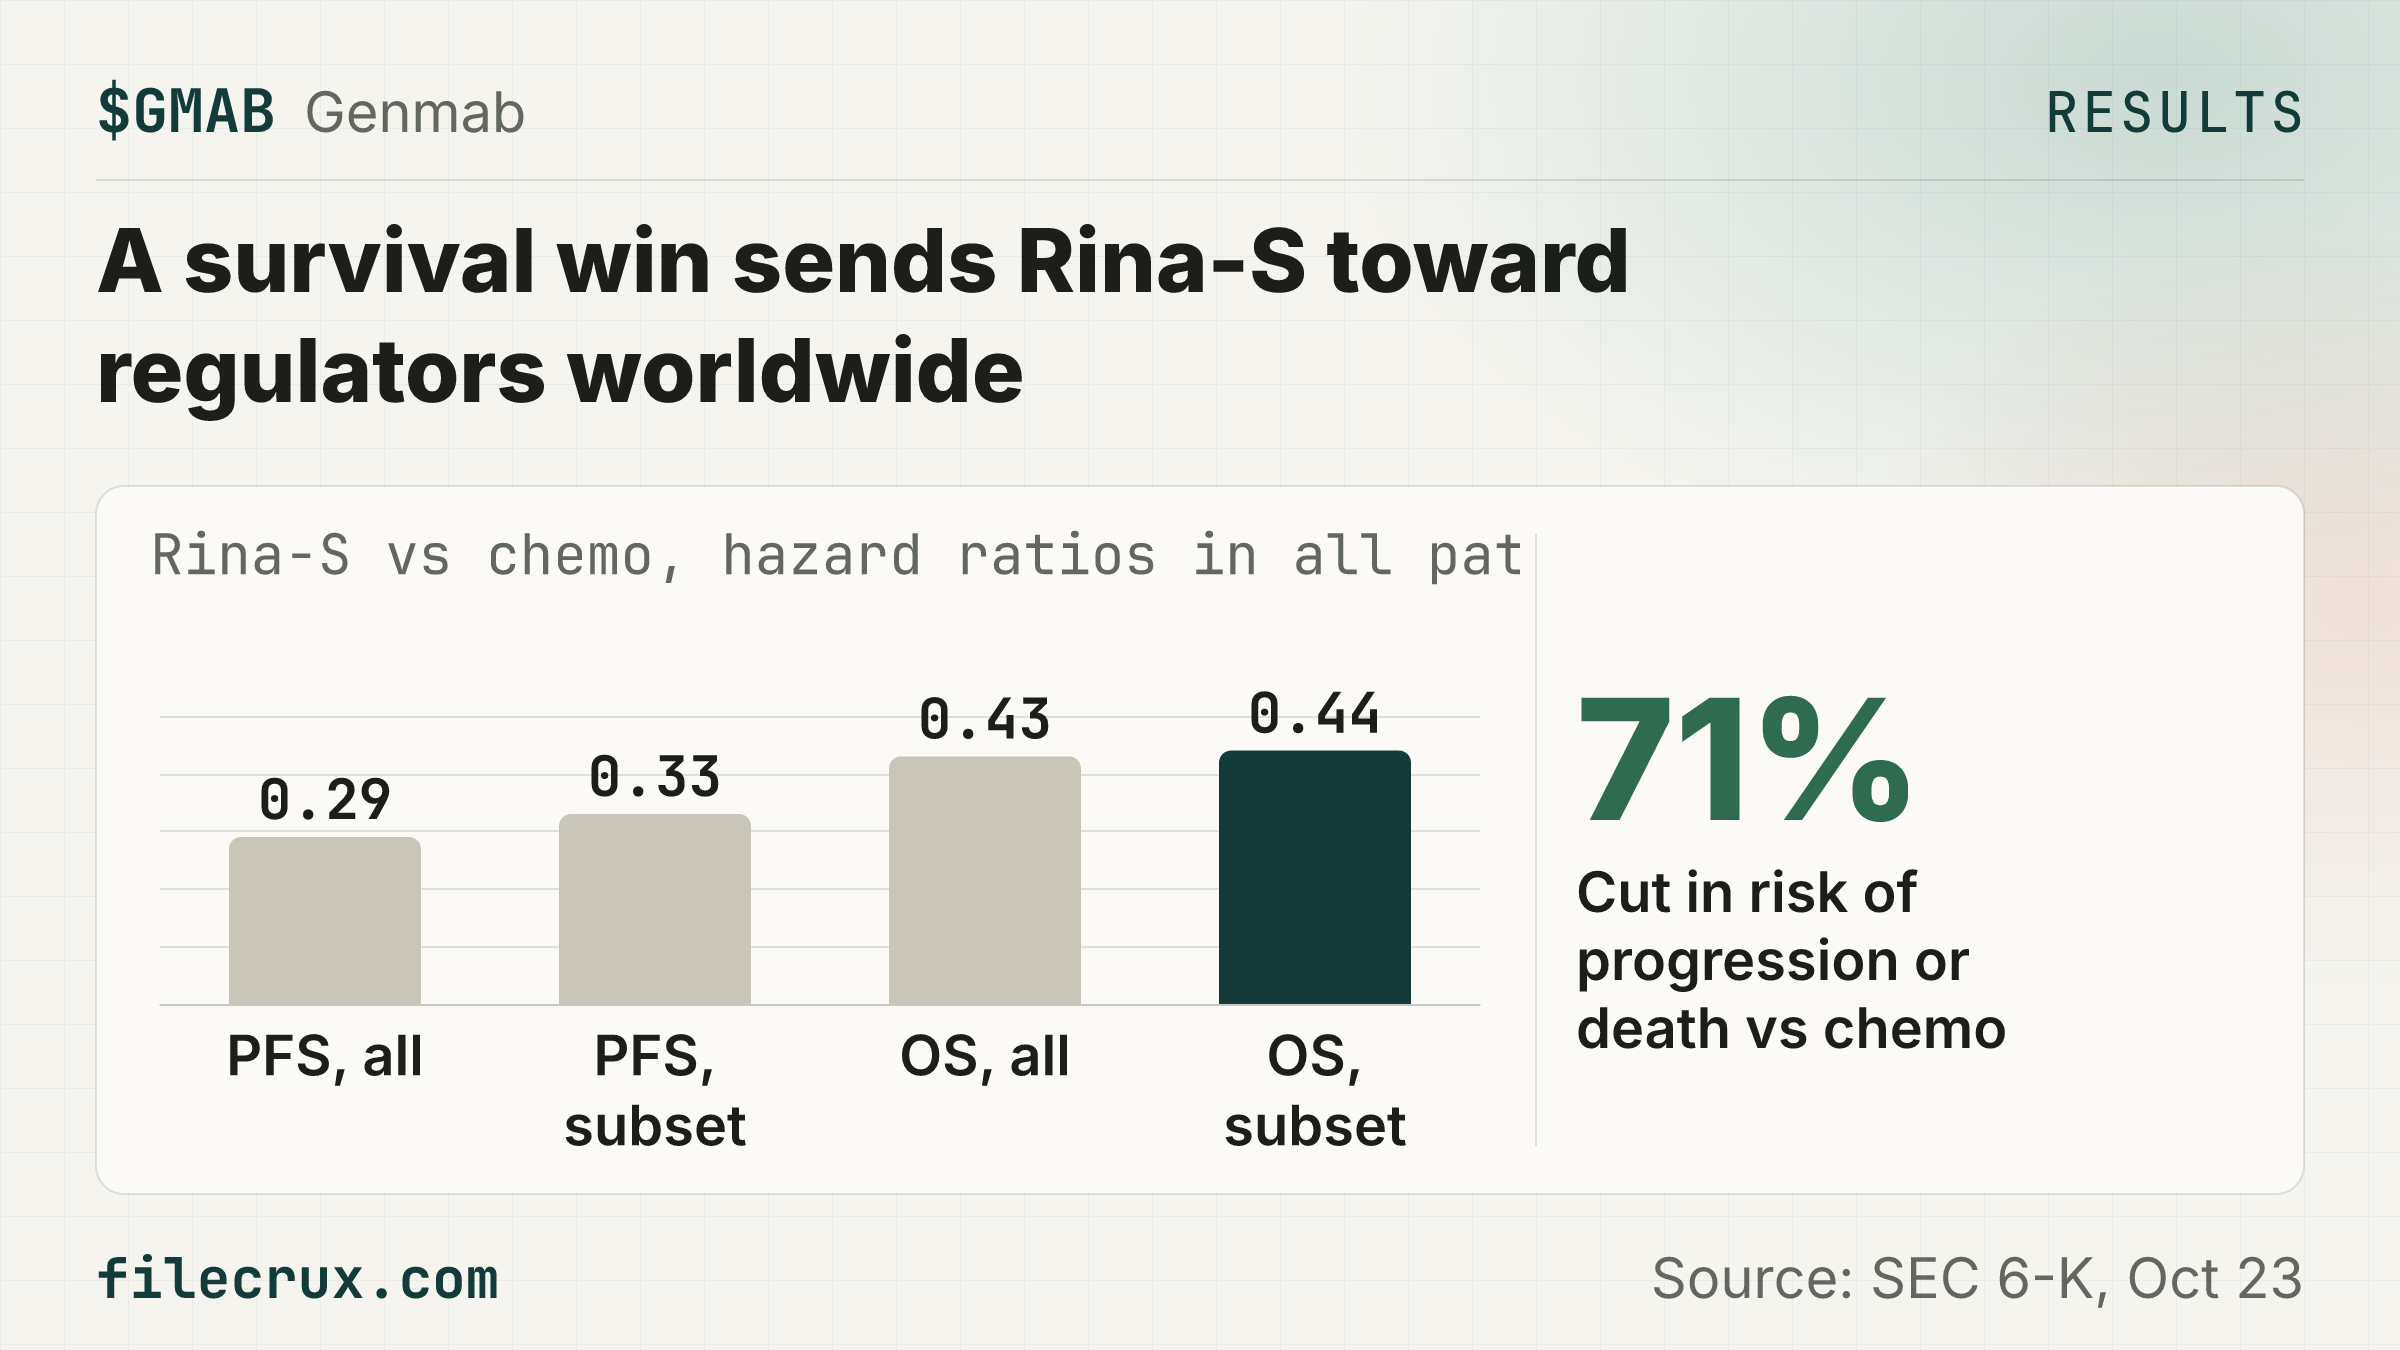
$GMAB Genmab's ovarian cancer drug Rina-S cut the risk of death by 57% in its first Phase 3 trial. 🏢 Genmab is a Copenhagen antibody-drug developer worth about $2.76B at $42.605 a share at 12:07 ET on October 23, 2026, whose science is behind eight approved medicines, and it earns royalties on J&J's DARZALEX, which sold $4,239M in Q3 2026 ✅ In the 584-patient Phase 3 RAINFOL-02 trial in platinum-resistant ovarian cancer, Rina-S beat chemotherapy, cutting the risk of progression or death by 71% (HR 0.29) and the risk of death by 57% (HR 0.43) 📈 The 584-patient all-comer group was enrolled regardless of FRα level, and the 492-patient primary set, which required prior mirvetuximab for high-FRα patients where eligible and available, still showed a 67% cut in progression risk (HR 0.33) and a survival HR of 0.44; the release gives no results broken out by FRα level 🏦 Genmab held $1.72B in cash at December 31, 2025, and its shares traded at $42.605 at 12:07 ET on October 23, 2026 ⚠️ The release gives only hazard ratios, with no median survival months, response rates or side-effect rates, the trial was open-label with investigator-assessed progression as its primary endpoint, and Rina-S is not yet approved anywhere 📅 Next: Genmab hosts an investor update on Wednesday, October 28 at 5:00 p.m. CET/12:00 p.m. EDT, and will take the data to regulators worldwide and to a future medical meeting Source: SEC 6-K, Oct 23
Highlight
Read as text
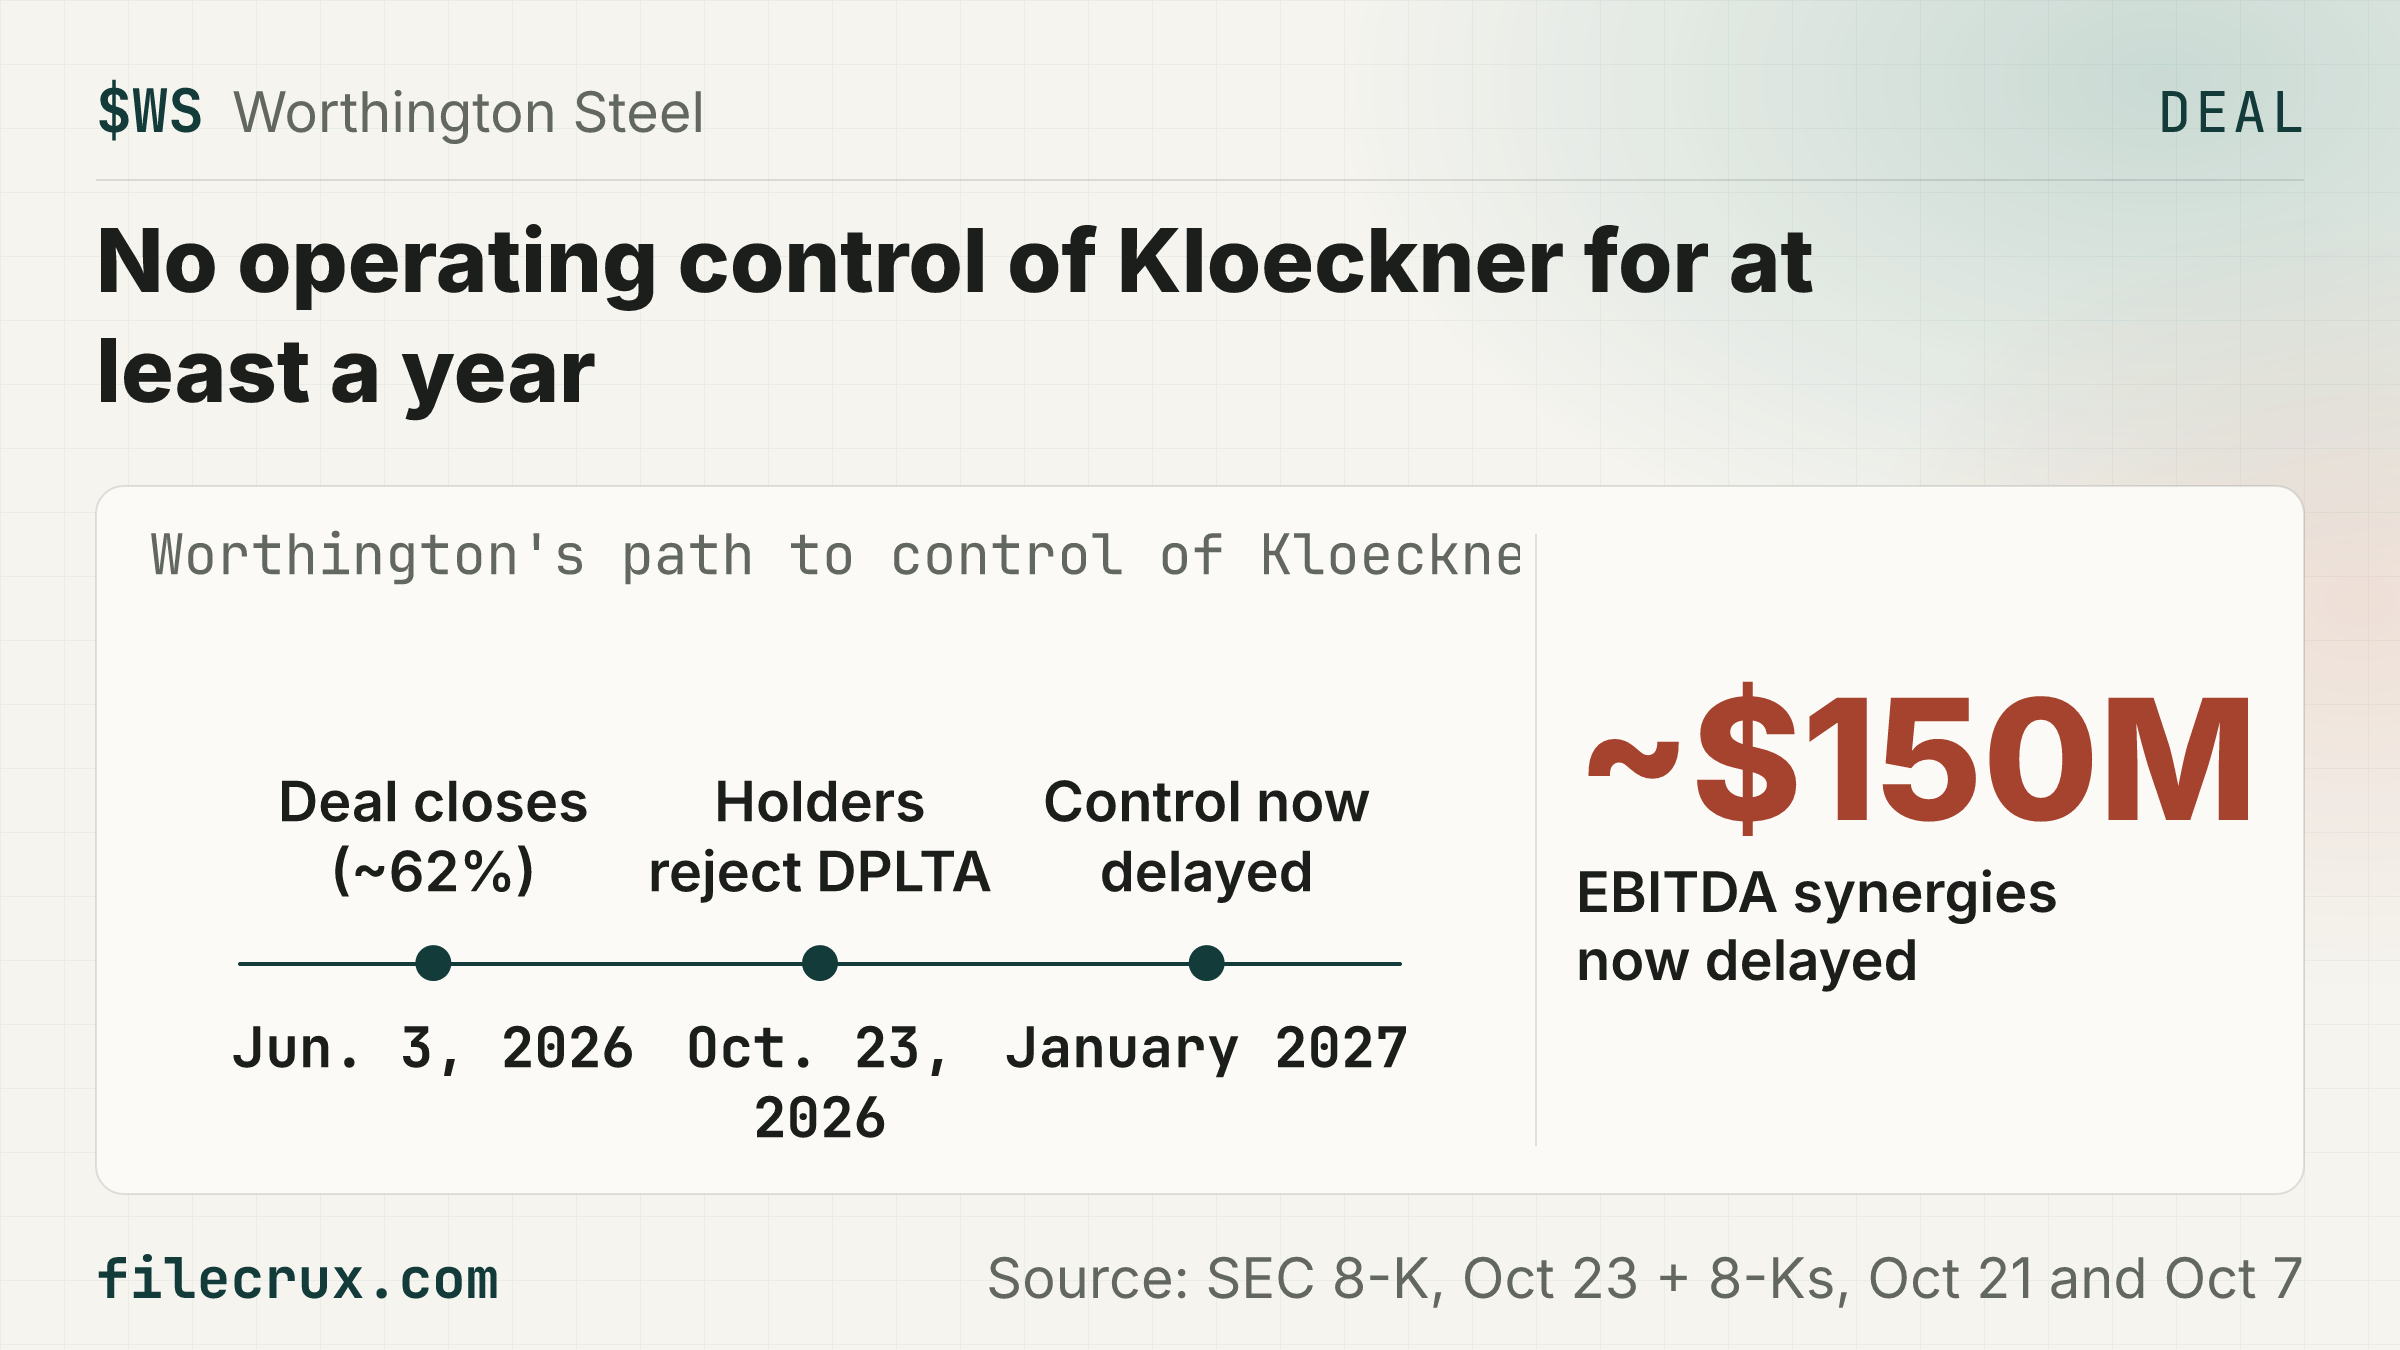
$WS Kloeckner holders voted down Worthington's control pact, delaying its ~$150M synergy plan. 🏢 Worthington Steel is a Columbus, Ohio steel processor that took about 62% of German metals processor Kloeckner & Co when that deal closed on June 3, 2026 ⚠️ At Kloeckner's October 23 meeting, its shareholders did not approve the domination and profit-and-loss transfer agreement, so Worthington keeps its stake but still has no operating control, which it had expected as early as January 2027 ⚠️ That delays the ~$150M of EBITDA synergies and ~$150M of working-capital savings that Worthington's October deck tied to the agreement, with about half of the run-rate due only in the first full year after it takes effect, though Worthington says it will pursue commercial, procurement and operational opportunities within the existing structure now 🏢 Kloeckner brought $1,772.7M of Worthington's $2,726.6M of net sales in the quarter to August 31, 2026, about 65%, in a company worth about $2.14B at $41.71 a share at 12:04 ET on October 23, 2026 🤝 Kloeckner stays fully consolidated and the financing is unaffected; without the agreement Worthington does not owe minority holders a fixed annual dividend and fixed-price put, but it also cannot direct Kloeckner's cash flows or pledge its assets 📅 Next: Worthington will not seek another vote on the agreement for at least one year from the Oct. 23, 2026 meeting Source: SEC 8-K, Oct 23 + 8-Ks, Oct 21 and Oct 7
Highlight

Read as text
$TGTX TG's off-the-shelf CAR-T kept MS disability stable or better in 7 of 8 patients at Day 180. 🏢 TG Therapeutics is a commercial-stage biotech whose revenue comes mostly from BRIUMVI, its approved drug for relapsing multiple sclerosis, and is worth about $8.04 billion at $52.51 a share at 11:16 ET on October 23, 2026 📈 In 26 patients with progressive MS who had worsened despite earlier anti-CD20 drugs, disability scores held steady or improved in 89% at Day 90 (16/18) and 88% at Day 180 (7/8), and three patients improved by 2.0 or more EDSS points 🏢 At $52.51 a share at 11:16 ET on October 23, 2026, TG is worth about $8.04 billion and held $616.6 million of cash and investments as of June 30, 2026 🏢 That market value is about 8.5 times TG's 2026 revenue target of roughly $950 million, so it rests on BRIUMVI, and these data, with no dose-limiting or high-grade CAR-T toxicities, add an early pipeline option rather than near-term sales 🏦 TG says its cash plus BRIUMVI revenue will fund its current plan, so this early study does not by itself point to a share sale ⚠️ The case against is that the study is open-label with no control group, median follow-up is only 4.9 months, the Day 180 figure rests on 8 patients, and the headline cites 16/19 at Day 90 while the body says 16/18 📅 Next: Azer-cel dose escalation and longer-term follow-up are ongoing, and topline Phase 3 subcutaneous BRIUMVI data is due year-end 2026/first quarter 2027 Source: Business Wire release, Oct 23 + SEC 8-K, Aug 3
Report
LKQ swaps chief executives and pulls its forecast as Europe sinks
Highlight

Read as text
$IOVA Final melanoma data: 62.5% response, 19.8-month median PFS, vs 65.2% in a May 31, 2024 cut. 🏢 Iovance Biotherapeutics sells Amtagvi (lifileucel), the first FDA-approved one-time cell therapy for previously treated advanced melanoma ⚠️ Median PFS is 19.8 months in the final 24-patient cohort with longer follow-up, after a May 31, 2024 cut in the October 5 deck had it not reached at 21.7 months 🏢 The final Phase 2 response rate is 62.5% (15 of 24) with a 29.2% complete response rate, against 65.2% and 30.4% at the May 31, 2024 cut ⚠️ At $13.675 at 10:22 ET on October 23, 2026, Iovance is worth about $6.19B, about 15 times its 2026 revenue guide of $410M to $420M, a value resting on new labels in frontline melanoma (70,000 patients a year) and second-line lung cancer (~7X the U.S. melanoma opportunity) 🏦 Cash and investments of $297.7M on June 30, 2026, with a runway the company puts into 2H 2028, fund the wait for the 670-patient TILVANCE-301 Phase 3 ⚠️ The release warns this 24-patient cohort may not predict TILVANCE-301, whose primary endpoints are response and progression-free survival by independent review 🏢 The two rates may reflect a different patient count: 15 of 24 is the final 62.5%, and the interim 65.2% would equal 15 of 23, though the filings do not give the interim count; median overall survival is still not reached at 50.9 months 📅 Next: Iovance presents its first lifileucel soft tissue sarcoma data in an ESMO Rapid Oral on Monday, October 26, 2026 Source: GlobeNewswire release, Oct 23 + SEC 8-K, Oct 5
Highlight
Read as text
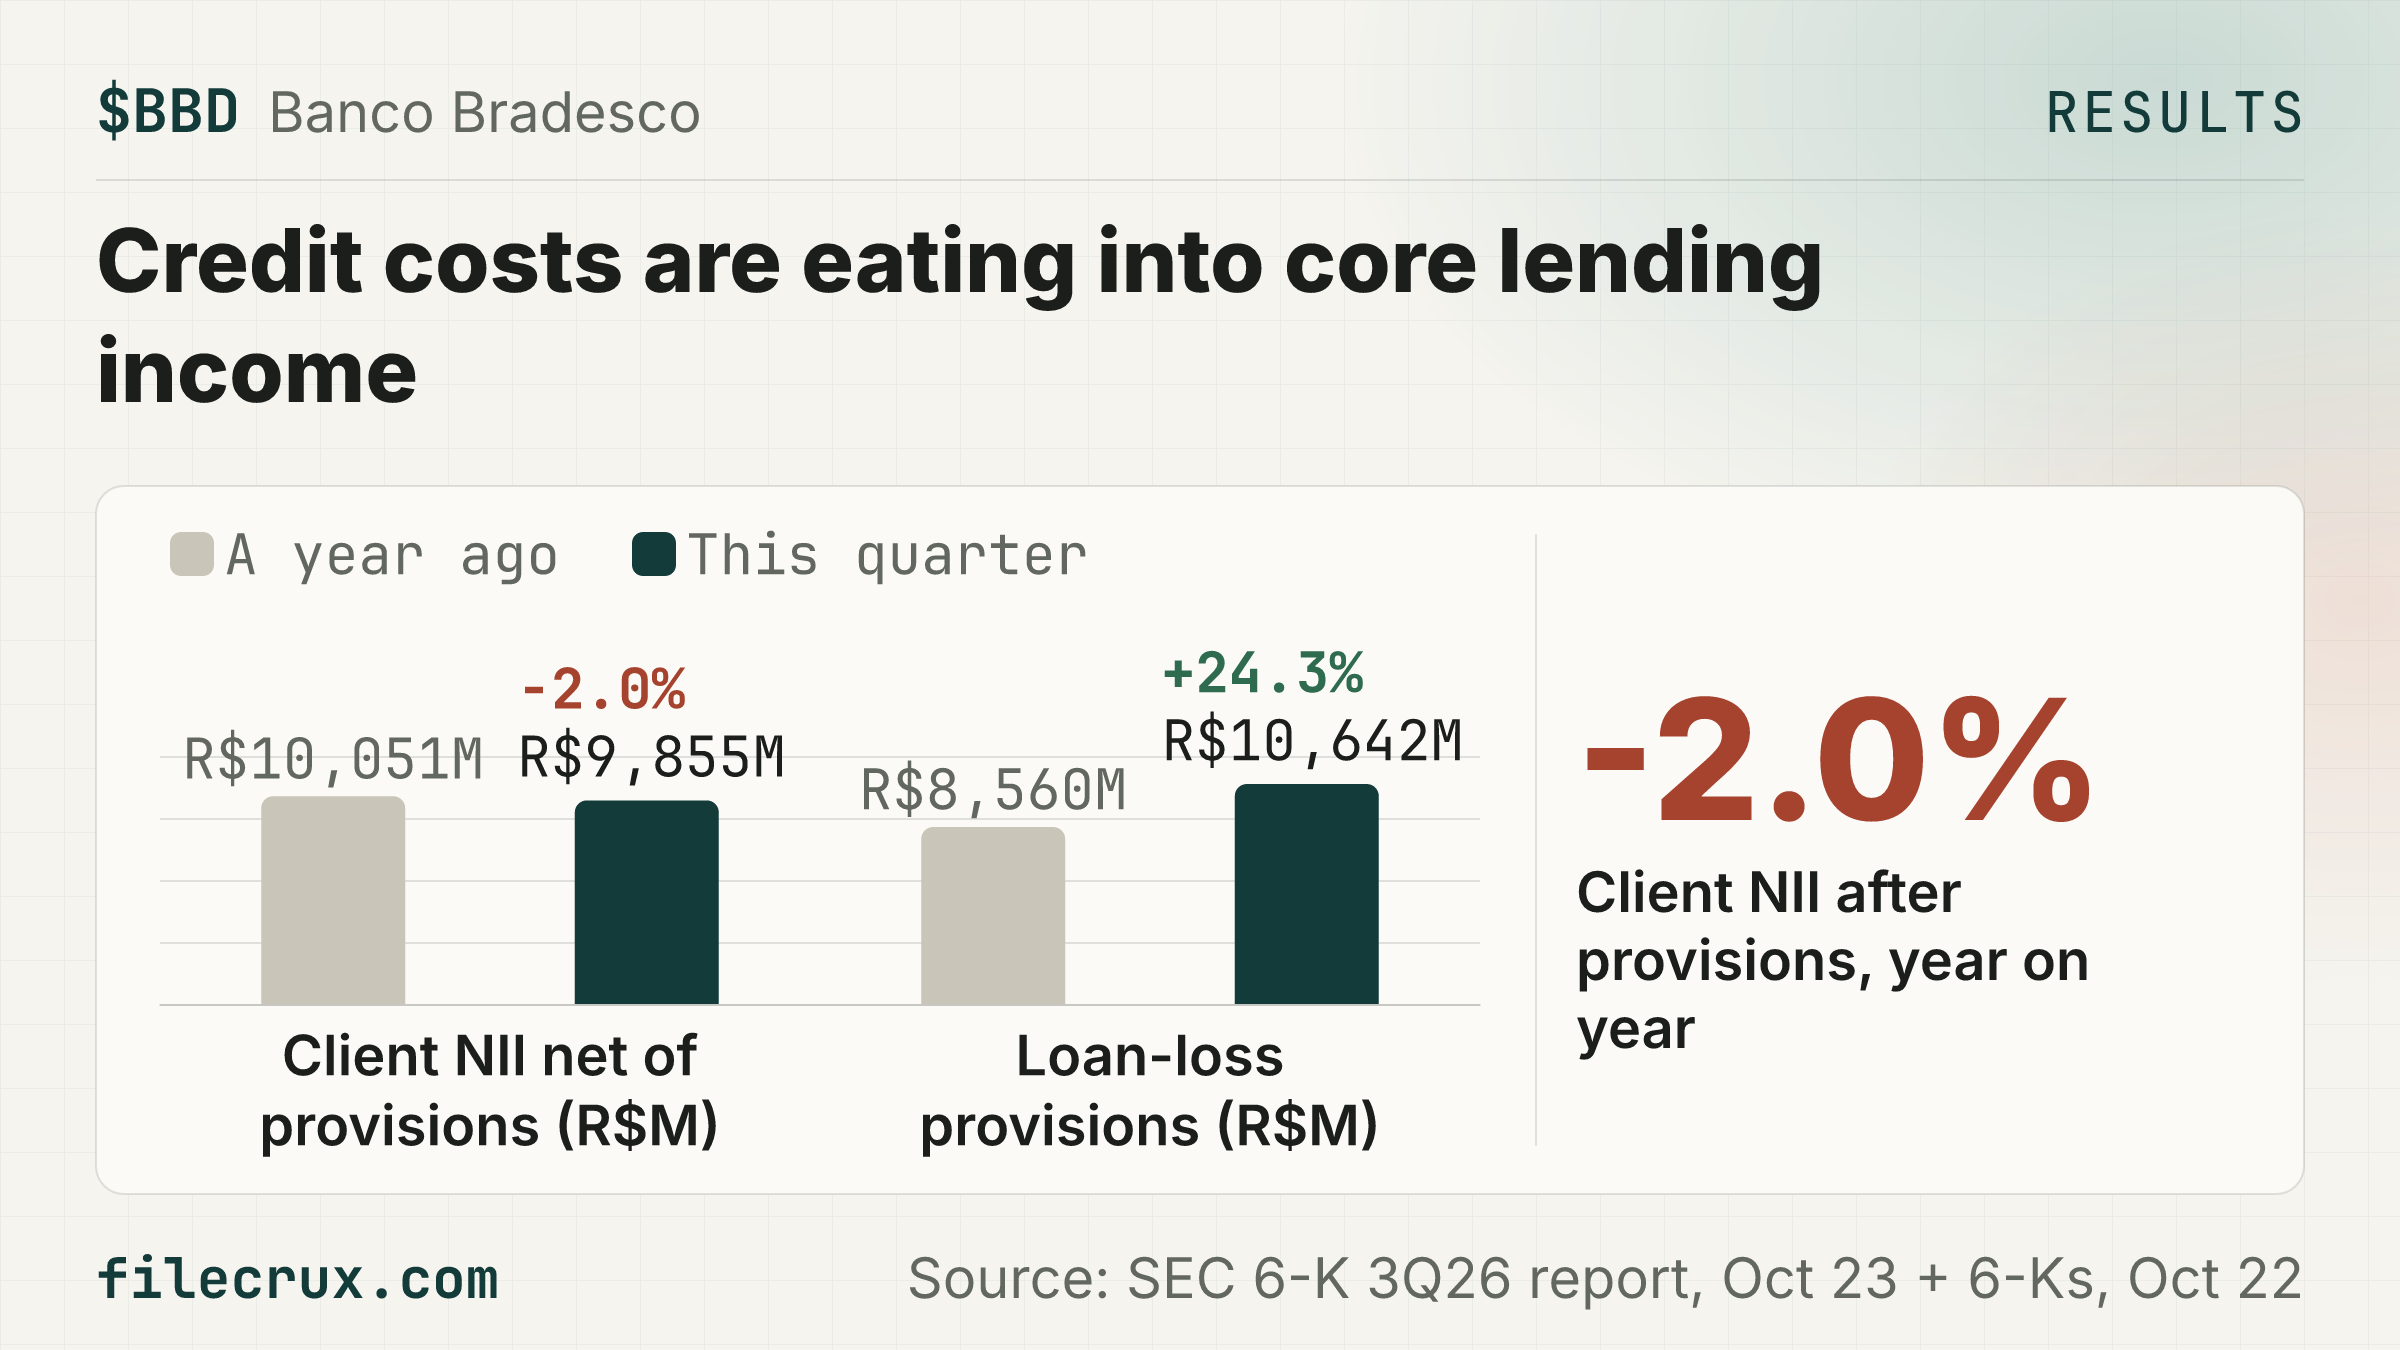
$BBD Bradesco 3Q26 recurring profit rose 14.6% to R$7.1bn, but loan-loss provisions jumped 24.3%. 🏢 Banco Bradesco is a Brazilian bank and insurer with R$2.54 trillion of total assets at the end of 3Q26 and R$193.5bn of cash at December 31, 2025 📉 Lending income after credit costs shrank: client net interest income net of provisions fell 2.0% year on year to R$9,855 million from R$10,051 million, as provisions rose 24.3% to R$10,642 million from R$8,560 million ⚠️ Provisions now run at about 1.5 times quarterly recurring profit, loans over 90 days late rose 0.3 points on the quarter to 4.6%, and provisions covered only 83% of loans moving into Stage 3 in 3Q26 (94% over nine months), which the bank says would be above 100% excluding government emergency-program loans ⚠️ Nine-month net interest income after provisions is R$32.0bn, so a fourth quarter at the 3Q26 pace of R$10.7bn would land near R$42.7bn, the bottom of the R$42bn to R$48bn 2026 guide 📈 Against that, profit growth came from market NII of R$875 million versus R$99 million a year ago, fee income up 4.2% on the quarter and an efficiency ratio improved to 45.4%, while the R$10bn capital raise helped lift common equity tier 1 to 12.1% in September from 11.3% in June 📈 Total NII after provisions still rose 5.7% year on year to R$10,730 million, and recurring profit rose 14.6% to R$7.1bn 📅 Next: Watch whether 4Q26 provisions keep NII after provisions above the R$42bn guide floor Source: SEC 6-K 3Q26 report, Oct 23 + 6-Ks, Oct 22
Highlight

Read as text
$CELC Gedatolisib combo reaches 15.7-month rPFS in 22 prostate cancer patients after abiraterone. 🏢 Celcuity sells REVTORPYK (gedatolisib), an FDA-approved breast cancer drug, and is testing the same drug with darolutamide in metastatic castration-resistant prostate cancer 📈 In the 22 men who had already taken abiraterone, FDA-approved breast cancer drugmaker Celcuity's combo posted median radiographic progression-free survival of 15.7 months, and 82.2% had not progressed at six months, as of an August 14, 2026 data cut-off 📈 That median is more than double the 5.5 to 6.7 months the company cites as today's progression-free survival in second-line treatment after AR therapy, though that comparison is across trials, not head to head 🏢 Prostate cancer would be a second market for a company worth about $3.21 billion at $65.57 a share at 16:00 ET on October 22, 2026, which held $754.0 million in cash and short-term investments on June 30, 2026 ⚠️ The case against is that results were weaker in the 18 men who had taken enzalutamide, at a 9.1-month median and a 62.5% six-month rate, and every group is small and uncontrolled across three doses ⚠️ Grade 3 treatment-related side effects hit 9 of the 45 men (20%), led by rash in 4 and itching in 2, but none were Grade 4 or 5 and none made a patient stop treatment 📅 Next: The randomized Phase 2 portion, which is meant to pick the Phase 3 dose, is expected to begin in the first half of 2027 Source: GlobeNewswire release, Oct 23
Highlight

Read as text
$TEM Tempus AI, a Chicago cancer-testing and patient-data licensing company, signs $192.5M of BMS and Pathos data deals running about five years. 🏢 Tempus AI is a Chicago company that sells cancer genetic tests and licenses de-identified patient data to drugmakers 🤝 Bristol-Myers Squibb will pay $137.5M in fixed payments, invoiced quarterly, for oncology data, Lens software and research services through December 31, 2031 ⚠️ The $55M from Pathos is a ceiling, not a fixed sum, because Pathos pays $100 per neurology record Tempus delivers, at 100,000 a year for five years, plus $5.0M for updates ⚠️ Pathos shares leadership and owners with Tempus, so a special committee of disinterested directors had to approve its order 📈 Spread evenly, the $192.5M comes to about $9.6M a quarter, roughly a tenth of the $93.2M Data and Applications revenue Tempus reported for Q2 2026 ⚠️ BMS can exit on 12 months' notice by paying a substantial termination fee, and Tempus cannot license the same neurology records to other buyers until 18 months after the later of delivery or October 22, 2027 📅 Next: Watch whether Pathos deliveries keep to 100,000 records a year; the neurology exclusivity window is tied to October 22, 2027 Source: SEC 8-K, Oct 23 + Q2 release, Jul 30
Highlight

Read as text
$RCI Rogers' record C$1.37B Q3 free cash flow leaned on C$274M of asset sales. 🏢 Rogers is Canada's communications, sports and entertainment company, worth about $17.9B at $33.2 a share at 16:00 ET on October 22, 2026 🏆 Free cash flow for the third quarter of 2026 was a record C$1,370M, up 65% from C$829M, mainly because reported capex fell to C$524M from C$964M ⚠️ Rogers' reported Q3 2026 capex of C$524M (C$964M a year ago) is net of C$274M it received for selling wireless and wireline network assets and real estate, so spending before those proceeds was C$798M, down only 18% from C$977M 📉 Without the sale proceeds, free cash flow would be about C$1.1B, up roughly 32%, and capital intensity nearer 15% than 9.6%, by our math, while adjusted diluted EPS fell 6% to C$1.29 from C$1.37 a year ago as adjusted EBITDA rose 1% to C$2,535M ⚠️ The 3.7x leverage ratio is as of September 30, before Rogers drew C$4.35B of short-term credit in full on October 1 to buy the last 25% of MLSE, and adding that to C$37,428M of adjusted net debt on the same C$10,030M trailing EBITDA gives about 4.2x by our math 📈 On the other side, operating cash flow, which does not count asset sales, rose 9% to C$1,658M, and Rogers reaffirmed its 2026 outlook for service revenue, adjusted EBITDA, capex and free cash flow 📅 Next: Rogers aims to sell a minority stake in Rogers Sports by the first half of 2027 and use the proceeds to repay debt, and plans to redeem its C$2.0B 2081 notes in December 2026 Source: Rogers Q3 release + SEC 6-K, Oct 23
Highlight

Read as text
$INFY Infosys cuts its FY27 revenue growth guide to 1%-2% from 1.5%-3.0%. 🏢 Infosys is a Bengaluru-based IT services and consulting firm with over 325,000 people, and this is its report for the quarter ended September 30, 2026 ✂️ The release cuts FY27 constant-currency revenue growth guidance to 1%-2% from the 1.5%-3.0% set on July 23, 2026, while keeping the 20%-22% operating margin range 📉 First-half revenue grew 1.9% in constant currency, so the new 1.5% midpoint implies a slower second half, after Q2 revenue of $5,145M grew 1.5% year on year in constant currency and 1.3% in reported dollars 🏢 At $12.27 a share at 08:34 ET on October 23, 2026, Infosys is worth about $49.8B, and it held $3.98B of cash and current investments on September 30, 2026 📉 Q2 net profit slipped to $817M from $839M a year earlier and free cash flow fell 15.7% to $928M, so the steady 21.0% margin did not lift dollar earnings ✅ Large-deal wins rose to $5.2B in Q2, 62% net new, from $3.6B in Q1, though a single mega deal of over $2B drove the jump, and AI revenue reached 10.5% of sales after growing 29% on the quarter 💰 The board declared an interim dividend of ₹26 per share, 13% more than last year 📅 Next: Watch whether the $5.2B of Q2 deal wins, including the mega deal, turn into revenue fast enough to hold the cut 1%-2% FY27 range Source: PR Newswire release, Oct 23 + SEC 6-K, Jul 28
Highlight
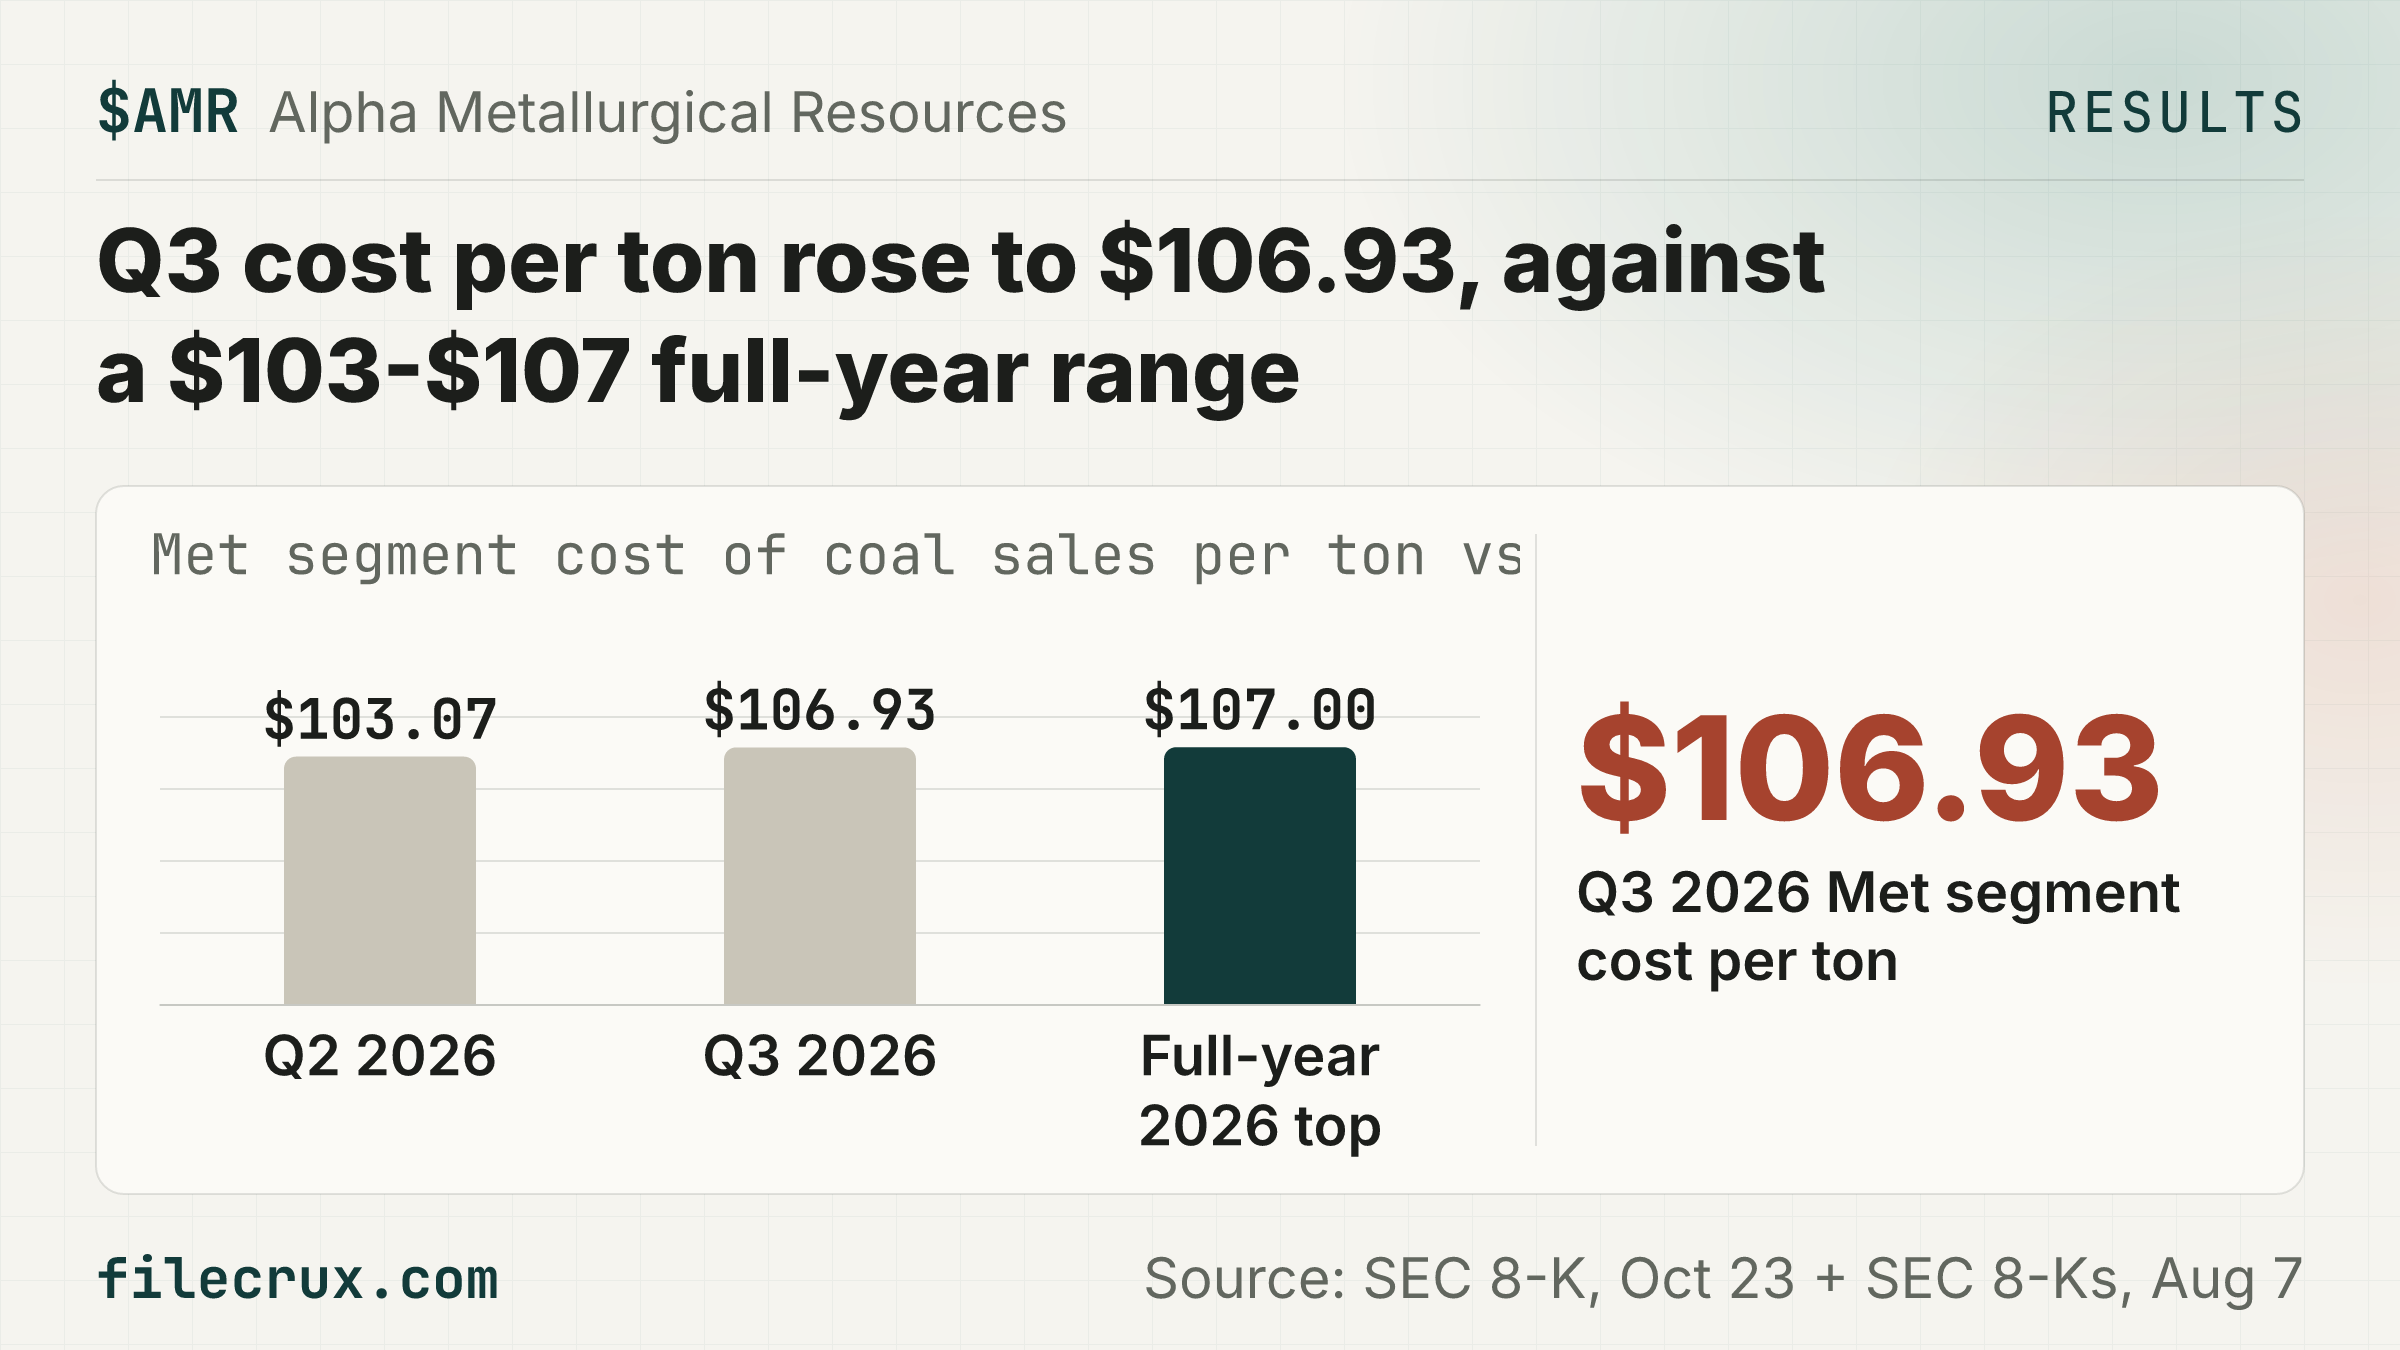
Read as text
$AMR Alpha's Q3 cost per ton climbed to $106.93, near the top of its 2026 range. 🏢 Alpha Metallurgical Resources, a Tennessee miner and the largest US producer of met coal for steelmaking, released preliminary Q3 2026 results ahead of its full report ⚠️ That cost is up from $103.07 per ton in Q2; with Q1 at $107.98, the year-to-date average is about $106.03 a ton, inside the $103.00 to $107.00 full-year range Alpha set on July 27 and about $0.97 below its top 📉 Realized price rose only to $121.09 a ton from $118.71, so the non-GAAP coal margin per ton shrank to $14.16 from $15.64 in Q2, while the GAAP coal margin rose to $2.45 a ton from $1.69 in Q2 🔥 The Q3 net loss of $9.3M, or $0.73 a share, sits against a market value of about $2.02B at $159.39 a share at 16:00 ET on October 22, 2026 ⚠️ Tons sold through Q3 add to about 11.06M (3.596M in Q1, 3.549M in Q2 and 3.915M in Q3), so Q4 needs roughly 3.14M to 4.34M tons to land inside the 14.2M to 15.4M shipment guidance, which this release did not update 📈 The quarter still improved on Q2, with tons sold up to 3.9M from 3.5M, Adjusted EBITDA up to $29.4M from $25.6M, and cash of $334.1M against only $10.6M of debt 📅 Next: Definitive Q3 results and the first 2027 outlook come before the market opens on November 6, 2026, with a call at 10:00 a.m. Eastern Source: SEC 8-K, Oct 23 + SEC 8-Ks, Aug 7
Highlight
Read as text
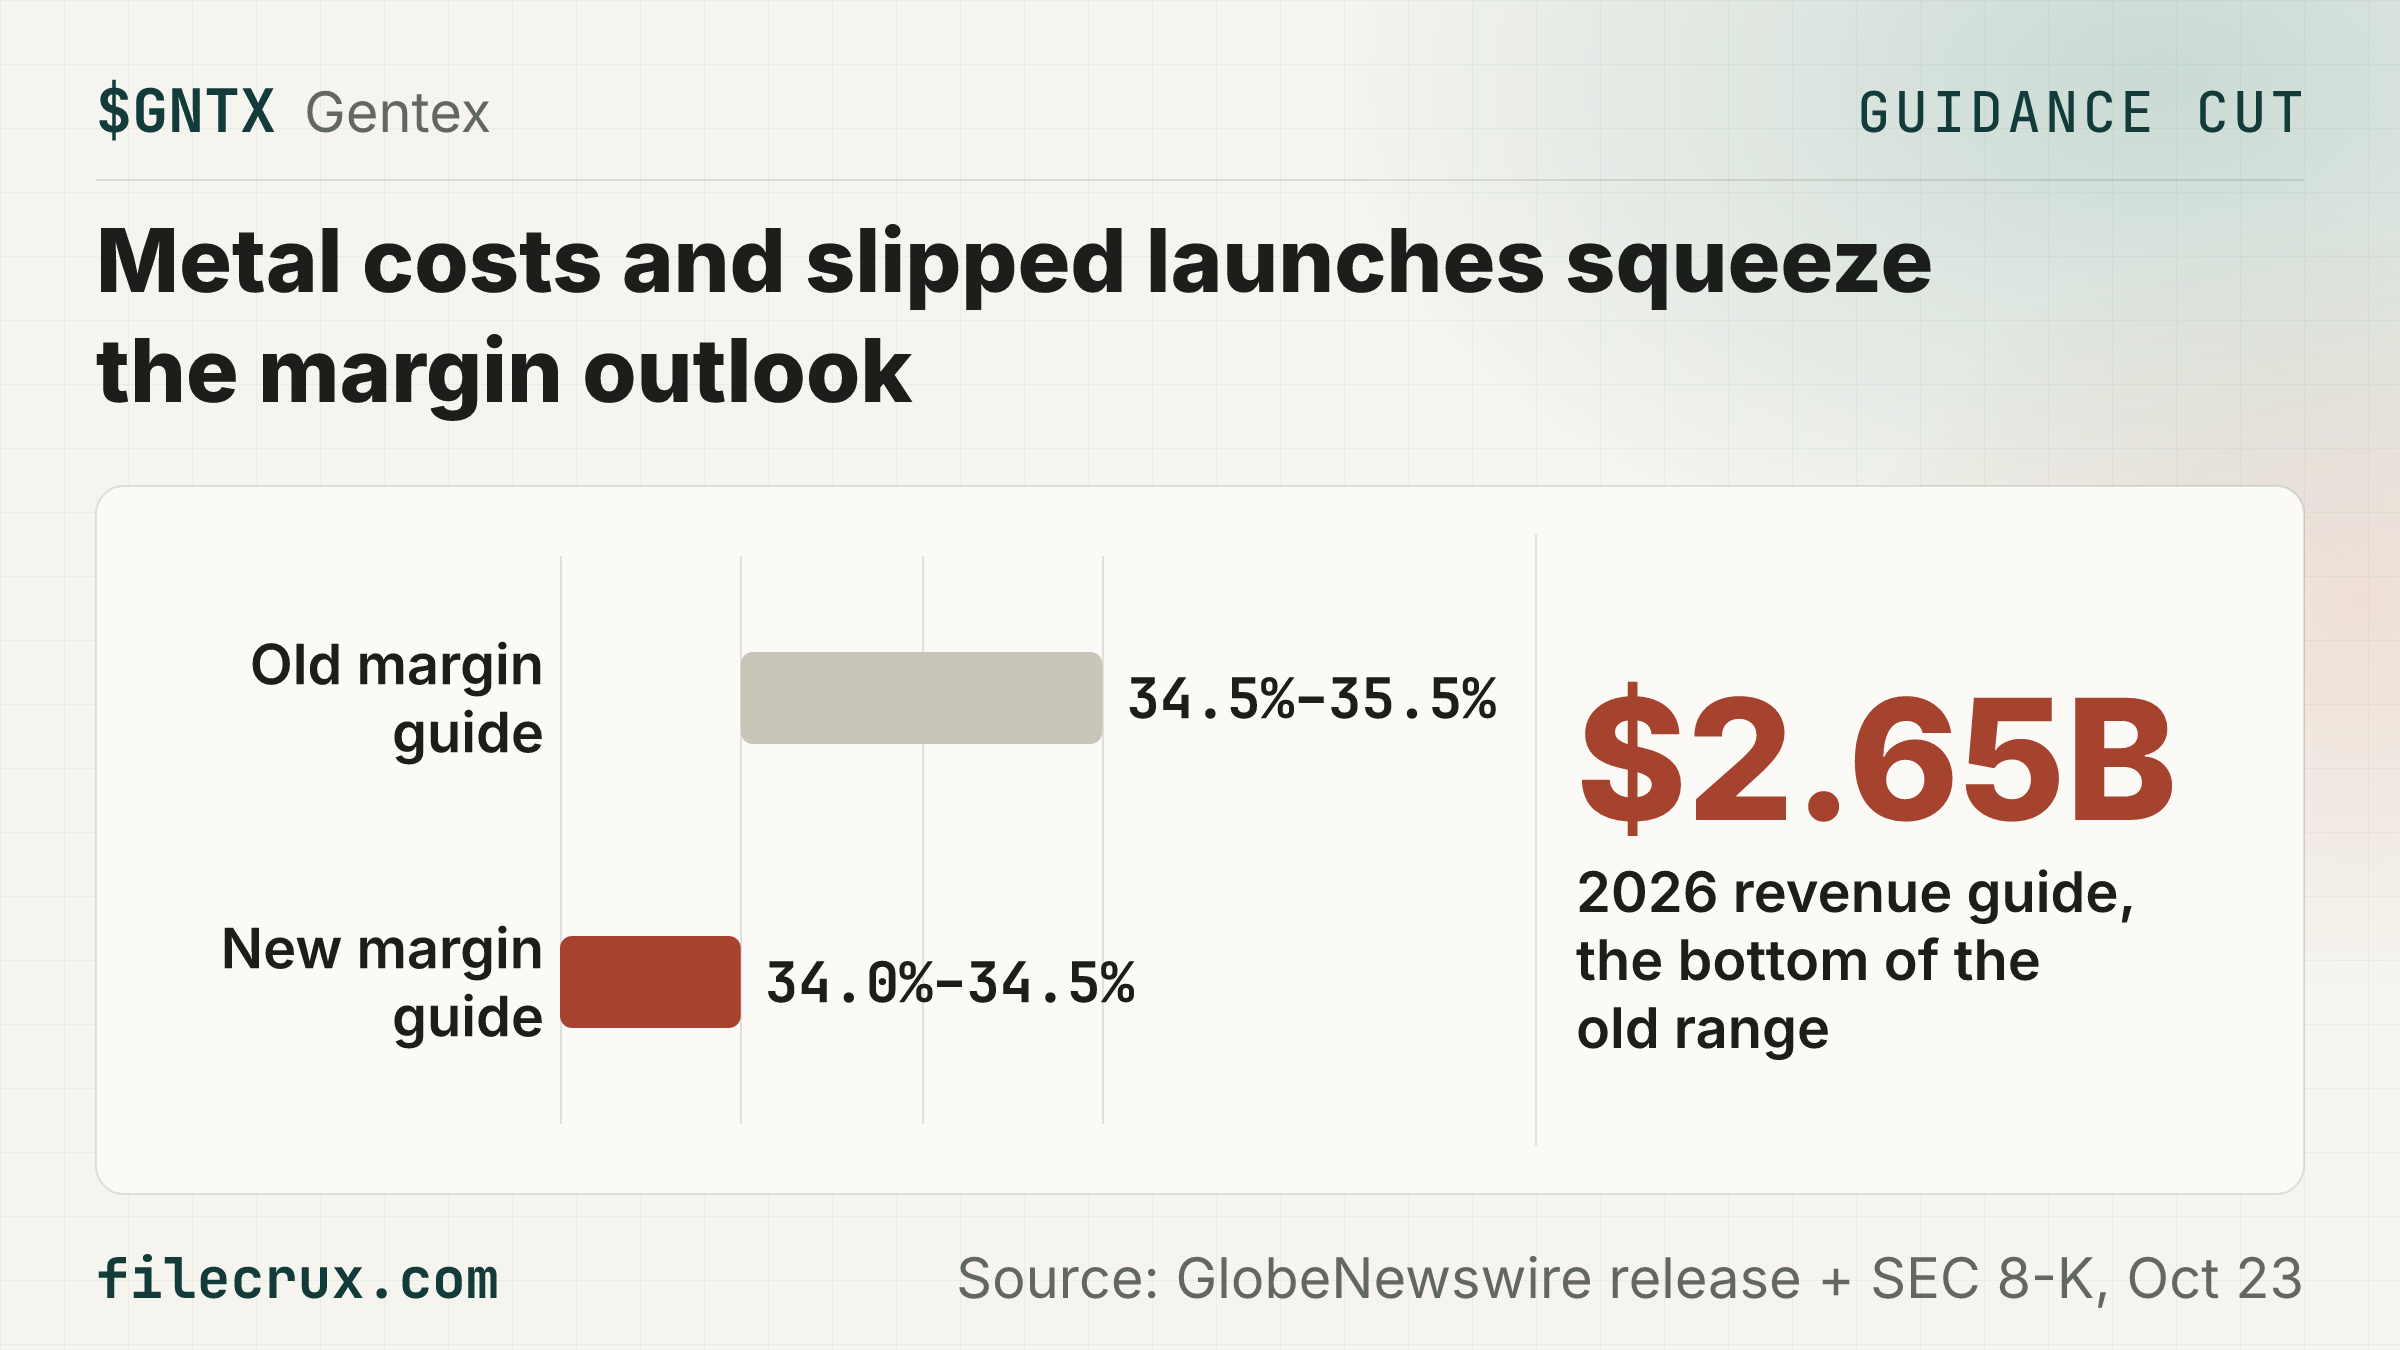
$GNTX Gentex cuts 2026 margin guide to 34.0% to 34.5% from 34.5% to 35.5%, revenue to about $2.65B. 🏢 Gentex, a Zeeland, Michigan supplier of digital vision and connected-car technology, was worth about $4.58B at its $21.74 close at 16:00 ET on October 22, 2026 📉 Third-quarter gross margin slid to 33.4% from 34.4% a year earlier ⚠️ Third-quarter sales of $647.7M came in about $35M below Gentex's own start-of-quarter forecast, which the release blames on customer issues and delayed launches, while saying automotive unit volumes were in line with expectations ⚠️ Our math on the new guide puts fourth-quarter sales near $676M at a gross margin of roughly 31.8% to 33.8%, so the low end would sit below the third quarter's already weak 33.4% 📉 GAAP diluted EPS fell to $0.43 from $0.46 a year earlier, while adjusted EPS held at $0.47 once impairment charges are stripped out 💰 Gentex spent $132.6M in the quarter buying back 5.7M shares at an average of $23.44, above the $21.74 close, which left cash and investments of about $379.3M at September 30 📈 On the other side, the margin guide includes $10M to $15M of fourth-quarter costs whose recoveries are expected in the first half of 2027, and the 2027 revenue outlook of $2.80B to $2.90B still stands 📅 Next: Gentex walks through the quarter on its call today, October 23, 2026, starting 9:30 a.m. ET; watch for detail on cost recovery and the 2027 outlook Source: GlobeNewswire release + SEC 8-K, Oct 23
Highlight

Read as text
$FHB Q3 net income fell 14% from a year ago to $63.7M as the credit-loss provision rose to $20.3M on a $12.5M partial charge-off on one CRE loan and other CRE downgrades. 🏢 First Hawaiian is Hawaii's oldest and largest bank, with $23.8B in assets and a market value of about $3.18B at the $26.13 close at 16:00 ET on October 22, 2026 🧾 A $12.5M partial charge-off on a single commercial real estate loan, plus other CRE downgrades, lifted the Q3 credit-loss provision to $20.3M from $4.5M a year earlier 📉 Diluted EPS fell to $0.52 from $0.59 a year earlier, and the $15.8M rise in the provision more than accounts for the $10.1M drop in net income 🧾 A tax settlement tied to the 2016 reorganization booked a $31.0M tax benefit against a $24.3M expense, and that net gain roughly cancelled $6.7M of merger costs, so credit drove the drop ⚠️ Net charge-offs jumped to 0.60% of average loans, annualized, from 0.11% in Q2, ran ahead of the provision, and left $226.5M of CRE loans rated special mention 📈 Net interest income rose to $174.1M from $171.0M in Q2, the margin reached 3.30% and CET1 capital stood at 13.50% 📅 The key question for holders is whether management shows the CRE trouble is limited to this loan before the Tri Counties Bank acquisition closes 📅 Next: Conference call today at 1:00 p.m. Eastern Time; $0.26 dividend payable November 27, 2026 Source: GlobeNewswire release + SEC 8-K, Oct 23
Highlight

Read as text
$LKQ LKQ ousts CEO Jude, pre-reports a Q3 net loss and withdraws its 2026 guidance. 🏢 LKQ sells recycled and aftermarket parts to repair cars in North America, Europe and Taiwan, and was worth about $5.68B at $22.47 a share at 16:00 ET on October 22, 2026 👤 CEO Justin Jude left effective today, and Chairman John Mendel and Audit Chair Sue Gove run the company until ex-Veritiv CEO Sal Abbate takes over on December 15, 2026 🔥 The same-day 8-K pre-reports a Q3 net loss of $16M to $32M, including $111M of non-cash impairments, against net income of $178M a year earlier 📉 Q3 adjusted EPS of $0.47 to $0.53 is 37% to 44% below last year's $0.84, as Europe's EBITDA margin fell to 4.1% to 5.1% from 10.0% on a German ERP rollout and UK and Benelux volume declines, while North America performed in line ✂️ Pulling the guide removes the July 30 forecast of $2.60 to $2.90 adjusted EPS and $625M to $775M of free cash flow, 11% to 14% of the market value at the October 22, 2026 close, leaving only preliminary Q3 ranges until full results 👤 Abbate's $12M sign-on RSU grant equals about 534,000 shares at the 16:00 ET October 22, 2026 close, roughly 0.2% of the 253M shares out, on top of a $3.3M sign-on cash award 📈 North America performed in line, Abbate grew Veritiv's share price more than 13-fold before its $2.6B sale, and the board ties his hire to an ongoing strategic review 📅 Next: Full Q3 results and a conference call on October 29, 2026; Abbate starts December 15, 2026 Source: GlobeNewswire release, Oct 23 + SEC 8-K, Oct 23
Highlight
Read as text
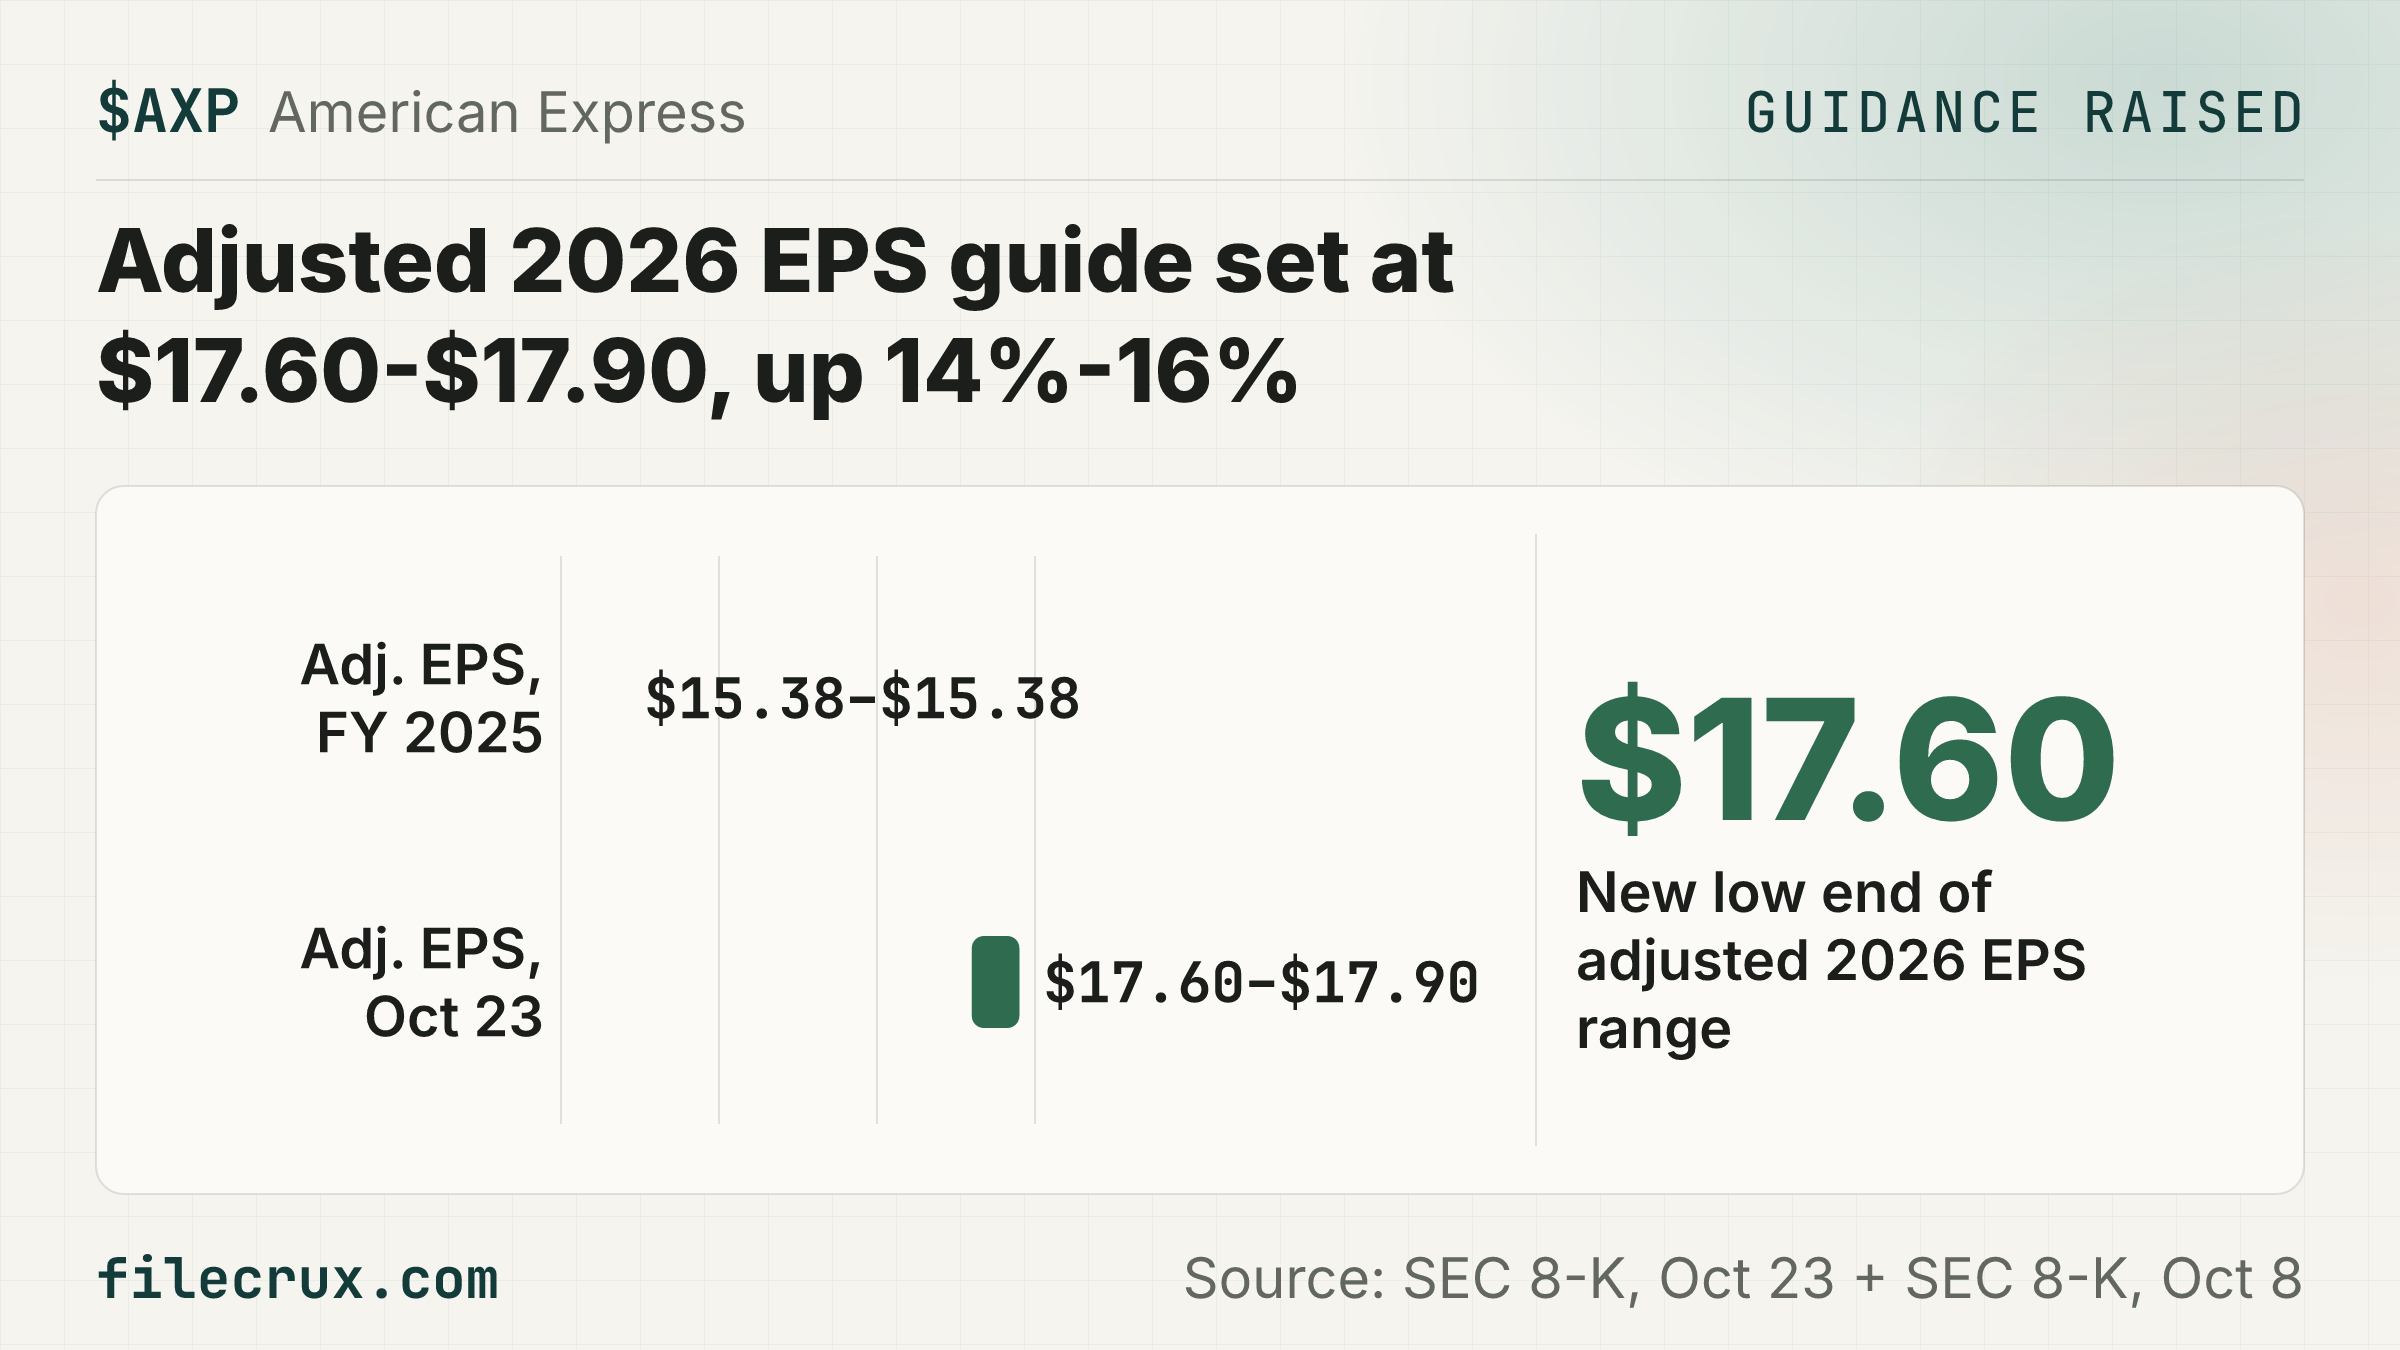
$AXP Amex lifts 2026 EPS guide to $18.30-$18.60, or $17.60-$17.90 adjusted, 14%-16% above 2025's $15.38. 🏢 American Express, the card issuer and payments network, was worth about $219.59B at $325.17 a share at 16:00 ET on October 22, 2026 🏦 In its October 8, 2026 8-K, the company said a $350M OCC civil money penalty would not change the full-year 2026 guidance it had already given 🚀 Today's adjusted 2026 EPS range of $17.60-$17.90 is 14%-16% above 2025's $15.38 🤝 The GAAP range sits higher because it books a $1.10-a-share after-tax gain from selling the GBTG stake, less a $0.37 restructuring charge paid for out of that gain ⚠️ Q3 adjusted EPS rose 13% to $4.68 from $4.14, but a tax rate of 18.1%, down from 24.1% thanks to discrete tax benefits, and a 3% drop in diluted shares did part of that work 📈 The core business still grew: revenue rose 9% to $20.1B, the net write-off rate eased to 1.8% from 1.9%, and the company says it is on track for 10% revenue growth this year 📅 Next: The investor call is at 8:30 a.m. (ET) today, October 23, 2026, and any color on 2027 is the thing to watch Source: SEC 8-K, Oct 23 + SEC 8-K, Oct 8
Highlight

Read as text
$BAH Booz Allen lifts its fiscal 2027 adjusted EPS guide to $6.50-$6.70 from $6.00-$6.35. 🏢 Booz Allen Hamilton is a McLean, Virginia technology contractor worth about $9.45B at the $78.57 close at 16:00 ET on October 22, 2026, and national security customers made up $2,076M of $2,778M in second-quarter revenue ⚠️ Second-quarter adjusted EPS rose 18.1% to $1.76 even though pretax income fell to $199M from $233M, because income tax expense dropped to $18M from $58M and diluted shares fell to 119.6M from 122.9M ⚠️ Income tax expense of $18M on $199M of second-quarter pretax income works out to a GAAP tax rate of about 9%, against about 16% for the first half, and first-half adjusted EPS of $3.57 leaves the second half needing $2.93-$3.13 to reach the $6.50-$6.70 guide 🚀 At the $78.57 close at 16:00 ET on October 22, 2026, about a $9.45B market value, the stock trades near 11.9 times the midpoint of the new EPS guide 🏦 Net debt reached $4,076M, or 3.3 times trailing adjusted EBITDA against 2.5 times a year earlier, after $934M of first-half acquisition payments helped cut cash by $394M to $334M 📉 Second-quarter free cash flow fell 33.4% to $263M, though first-half free cash flow of $524M already covers more than half of the full-year guide of $850M to $925M 📈 Civil and commercial revenue fell to $702M from $827M; booked work rose to $11.8B from $10.7B in March 📅 Next: Earnings call at 8 a.m. EDT on Friday, October 23, 2026, and a $0.59 dividend payable December 4, 2026 Source: SEC 8-K + 10-Q, Oct 23
Highlight
Read as text
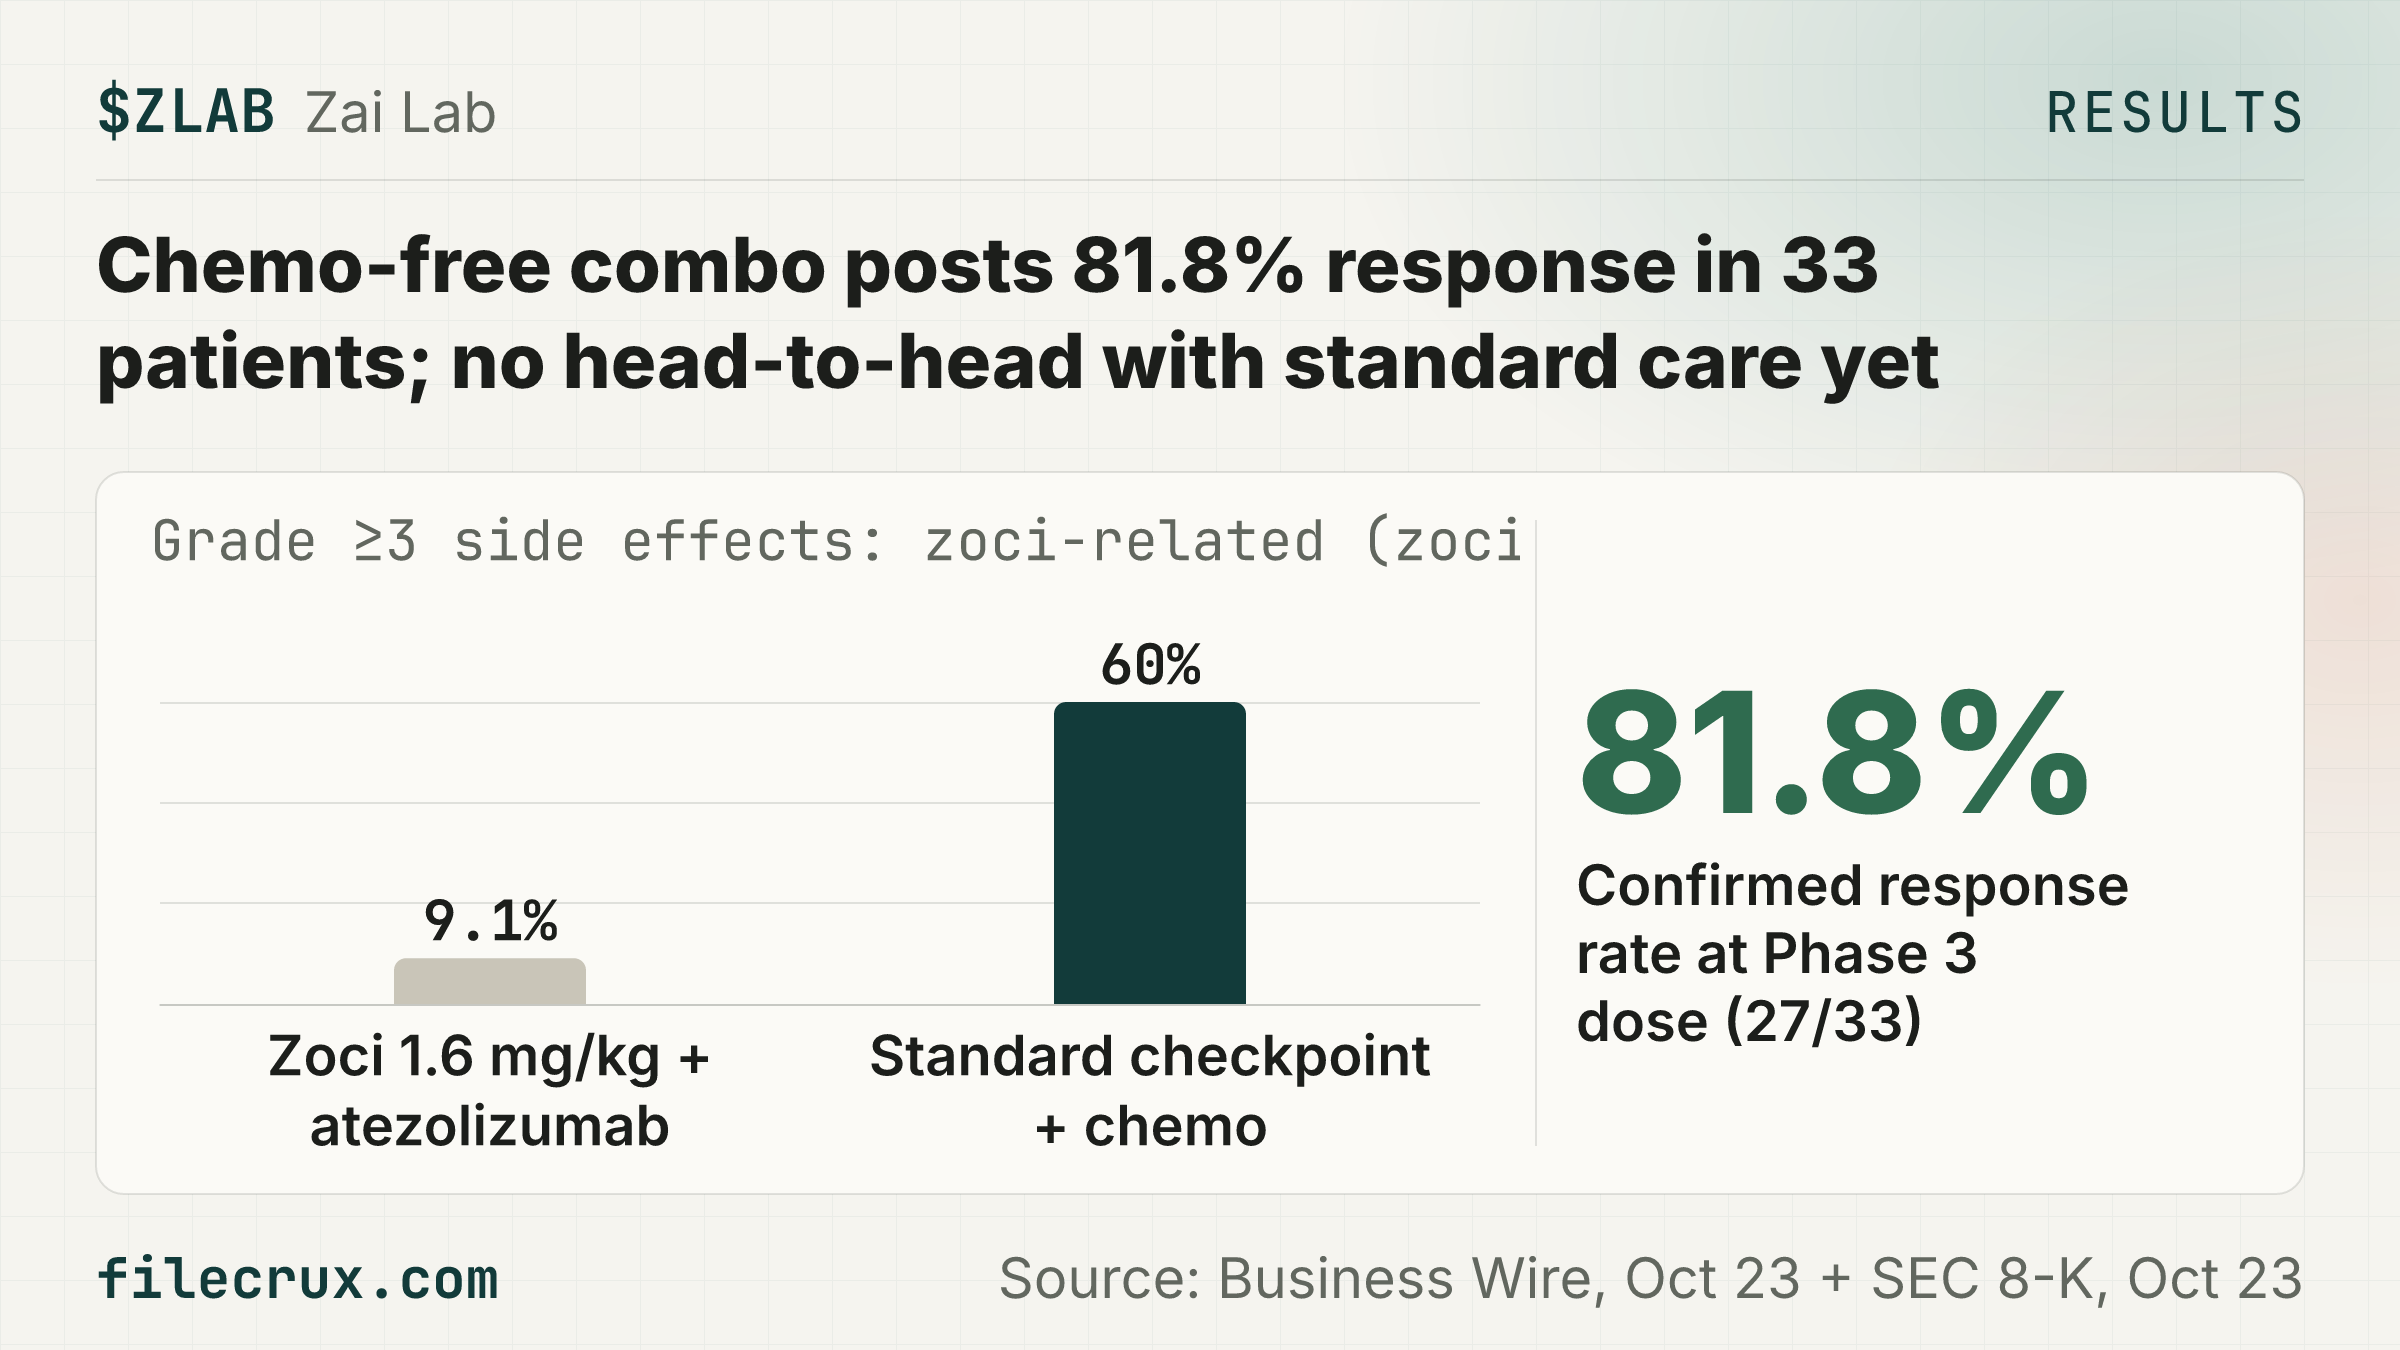
$ZLAB Follow-up: Zai Lab's zoci posts 81.8% response in first-line small cell lung cancer. 🏢 Zai Lab is a commercial-stage biopharma based in China and the US, and zoci, its DLL3-targeting antibody-drug conjugate, is on track to be its first global oncology launch 🏦 Its Oct 22, 2026 release said a $250M PIPE at $22.04 per ADS would mainly fund zoci, about 10% of the ~$2.47B market value at the $22.04 close at 16:00 ET on October 22, 2026 📈 At the 1.6 mg/kg Phase 3 dose, zoci plus atezolizumab produced a confirmed 81.8% response rate (27/33) and an 81.9% six-month progression-free survival rate in first-line extensive-stage disease 📈 That response rate beats the 60-70% the release cites for standard checkpoint inhibitor plus chemotherapy, and the regimen uses no platinum chemotherapy 📈 Grade 3 or worse zoci-related side effects hit 9.1% of patients with no treatment-related discontinuations, against about 60% treatment-related for standard care ⚠️ The case against is that this is 33 patients with no control arm and indirect comparisons, the response rate's 95% interval falls to 64.5%, inside the standard-care range, and only 15 patients have six months of follow-up 📅 Next: ESMO poster on October 26, 2026; global randomized Phase 3 expected to start by year-end 2026 Source: Business Wire, Oct 23 + SEC 8-K, Oct 23
Highlight

Read as text
$GRC Gorman-Rupp's Q3 net income doubles to a record $22.7M as sales rise 11.8%. 🏢 Gorman-Rupp is an Ohio company, founded in 1933, that makes pumps for water, wastewater, construction, agriculture, fire suppression and industrial uses 🏆 Q3 net income at the Ohio pump maker doubled to $22.7M from $11.3M a year earlier, lifting earnings to 86 cents a share from 43 cents, on record sales of $193.3M 📈 Setting aside last year's one-time facility costs, adjusted EPS still rose 65% from 52 cents, and gross margin widened 420 basis points to 33.4% 🏢 The stock closed at $70.13 at 16:00 ET on October 22, 2026, a market value of about $1,850M, or near 20 times Q3 EPS multiplied out over four quarters 🏦 Nine months of operating cash flow, $114.9M in all, paid down $58.0M of debt, which cut Q3 interest expense to $4.3M from $5.8M and left long-term debt of $250.2M against cash of $59.3M at the end of the third quarter ⚠️ The case against is that nine-month orders rose only 2.2%, backlog of $236.8M sits below the $244.0M at end-2025, and lower LIFO and medical costs supplied 130 basis points of Q3's margin gain 📅 Next: The company gave no guidance and set no date, so watch whether Q4 orders rebuild the $236.8M backlog Source: Business Wire release, Oct 23
Highlight

Read as text
$TNGX Follow-up: Tango cuts about 14% of staff, deprioritizes new-target discovery, delays two readouts to January 2027. 🏢 Tango Therapeutics is a Boston cancer drug developer whose oral PRMT5 inhibitor vopimetostat posted an 82% response rate with Revolution Medicines' daraxonrasib in pancreatic cancer in its October 23, 2026 release ✂️ On October 22, 2026 the board of Tango, a Boston cancer drug developer, approved a plan to deprioritize novel target discovery and cut about 14% of the workforce, mostly in research, to focus on its PRMT5 drugs vopimetostat and TNG456 ⚠️ The vopimetostat lung cancer monotherapy data and the first TNG456 data, both guided on August 11, 2026 for the second half of 2026, are now expected in January 2027 ⚠️ The 8-K gives no headcount, savings or restructuring charge, so the cut cannot yet be sized against the Q2 2026 net loss of $55.3 million, which included $37.2 million of R&D spending 🏢 With $1.01 billion of cash and investments on June 30, 2026 against a market value of about $4.71 billion at $27.93 at 16:00 ET on October 22, 2026, this reads as a cost trim to steer money to late-stage work, not a cash rescue 📅 For scale, Tango held $1.01 billion of cash and investments on June 30, 2026; the 8-K gives no savings figure for the cut 📅 Next: Lung cancer and TNG456 data in January 2027; front-line Phase 3 start targeted for the first half of 2027, though Tango is still securing daraxonrasib supply for it Source: SEC 8-K, Oct 23 + SEC 8-K, Aug 11
Highlight
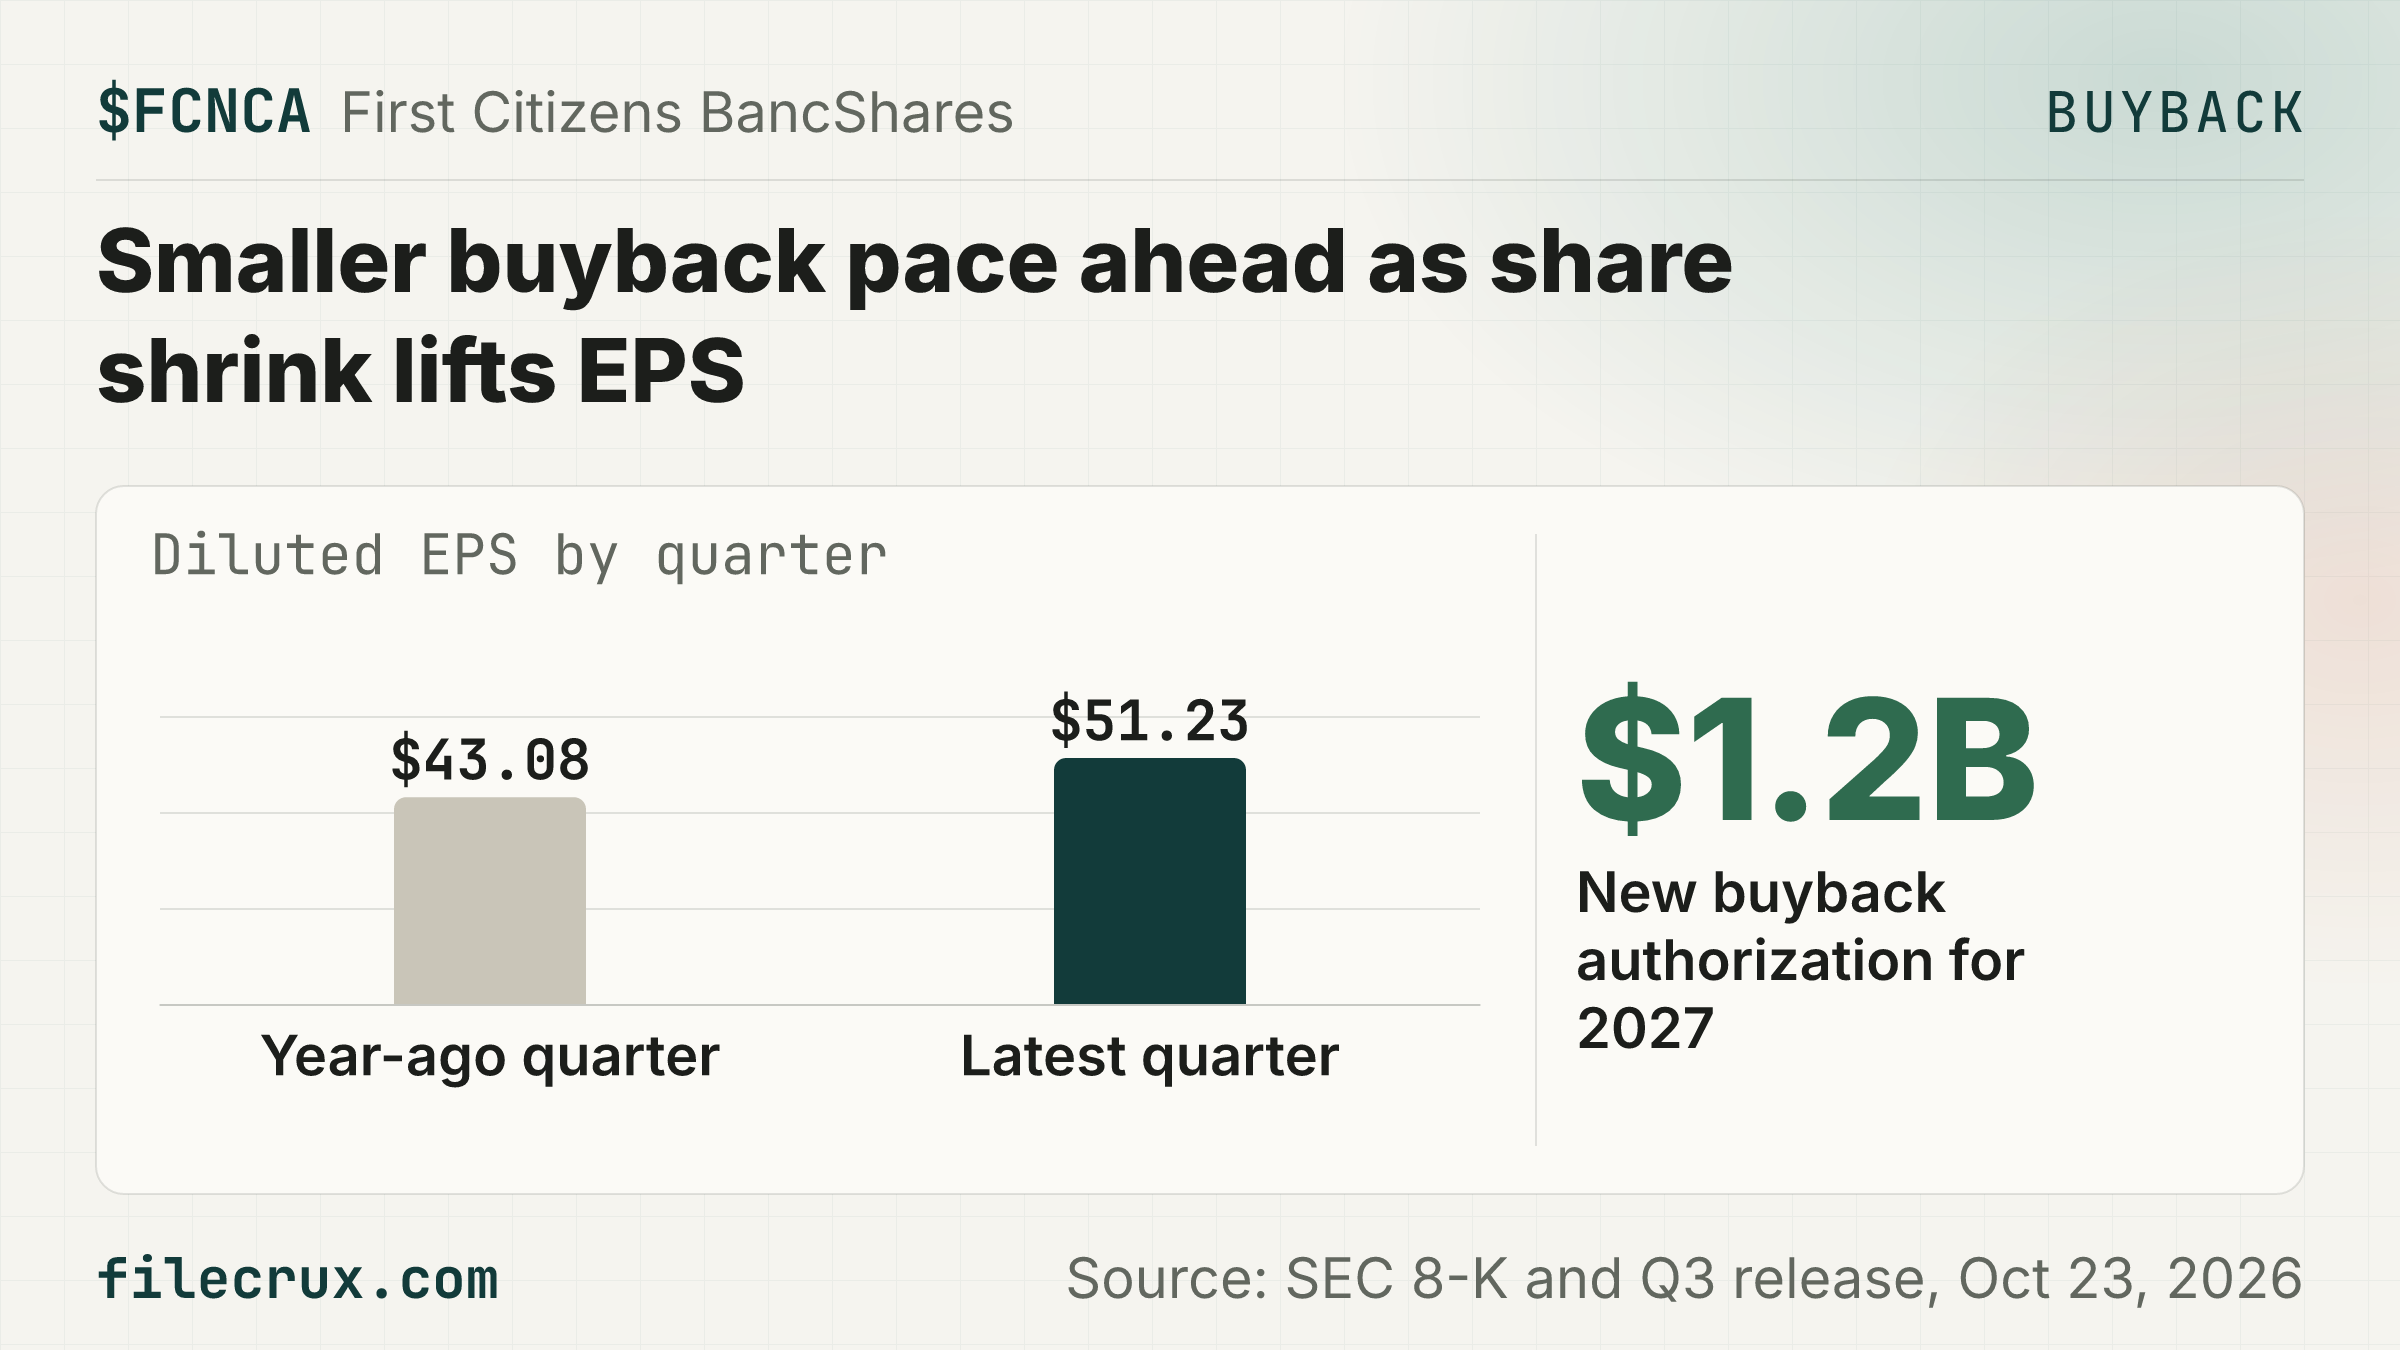
Read as text
$FCNCA First Citizens sets $1.2B buyback for 2027 as Q3 EPS rises 19% to $51.23. 🏢 First Citizens BancShares is a Raleigh, N.C. bank holding company with more than $225 billion in assets 💰 The new 2027 plan allows up to $1.2 billion of buybacks, about 4.7% of the ~$25.34 billion market value at the $2196.76 close at 16:00 ET on October 22, 2026 ⚠️ That is a slower pace than 2026, when it spent $2.1 billion on buybacks in three quarters, so $1.2 billion works out to about $300 million a quarter against Q3's $600 million 📈 Buybacks drive much of the 19% gain over year-ago quarterly EPS of $43.08, since Q3 net income to common rose only about 4% to $577 million while average shares fell about 12% 📉 Against Q2, net income fell 10% to $606 million and EPS fell 7.7% as a $55 million credit provision replaced a $10 million benefit 📈 In return, the CEO said Q3 beat the company's own expectations, deposits grew 6.8% to $185.26 billion, and $711 million was left under the 2025 plan at Sept. 30 ⚠️ The Q4 outlook puts net interest income at $1.70 billion to $1.77 billion but net charge-offs at 30 to 35 bps, up from 27 bps in Q3 📅 Next: Earnings call at 9 a.m. Eastern time on Friday, October 23, 2026, then Q4 results against the outlook Source: SEC 8-K and Q3 release, Oct 23, 2026
Highlight

Read as text
$TNGX Tango's pancreatic combo response rate slips to 82% from 92% on more patients. 🏢 Tango Therapeutics is a clinical-stage cancer drug developer testing its oral PRMT5 inhibitor vopimetostat with Revolution Medicines' daraxonrasib 📉 The response rate in 22 second- and third-line MTAP-deleted pancreatic cancer patients was 82% at the August 20, 2026 cutoff, down from 92% in the June 2026 data, and 7 of the 18 responses were unconfirmed at the cutoff, though the company says all were confirmed later, while 88% of patients were still progression-free at 9 months 🏢 At $27.93 at 16:00 ET on October 22, 2026, Tango is worth about $4.71 billion, roughly $3.7 billion above its cash and investments 🏦 Tango held $1.01 billion of cash and investments on June 30, 2026, which it expects to fund its current operating plan, against a Q2 2026 net loss of $55.3 million, and an August 11 at-the-market program allows up to $400 million in stock sales, about 8.5% more shares at the $27.93 close at 16:00 ET on October 22, 2026 ⚠️ Median follow-up is only 7.1 months, the 250 mg dose was not well tolerated, and Tango names securing enough daraxonrasib for the Phase 3 as a risk 📅 After FDA talks, the planned front-line Phase 3 will randomize patients 1:1 against standard chemotherapy, with response rate and PFS as dual primary endpoints 📅 Next: Phase 3 start expected in the first half of 2027, plus talks with regulators on a second-line approval Source: GlobeNewswire release, Oct 23 + SEC 8-Ks, Aug 11
Highlight

Read as text
$ALV Autoliv trims its 2026 margin guide to around 10.5%, the bottom of its range. 🏢 Autoliv is the Stockholm-based maker of airbags, steering wheels and seatbelts, with $11,066M of net sales over the last 12 months ✂️ Autoliv narrowed its full-year 2026 adjusted operating margin guide to around 10.5%, the low end of its prior around 10.5-11% range, blaming raw materials, logistics, flooding in Thailand and weaker customer call-off accuracy ⚠️ Losing 0.25pp off the old midpoint on about $11.1B of sales takes roughly $28M out of adjusted operating income, small against a market value of about $8.71B at $118.88 a share at 16:00 ET on October 22, 2026 ⚠️ Even the lowered guide needs a big fourth quarter: a 9.4% adjusted margin through nine months implies roughly 13-14% in Q4 on our math, which Autoliv says will come from more product launches and significant raw material recoveries 📉 The third quarter was soft, with net sales down 0.5% to $2,693M, diluted EPS down 6.8% to $2.13 and adjusted margin at 9.7% against 10.0% a year earlier 💰 Sales and cash guidance held at around 0% organic growth and around $1.2B of operating cash flow, which funds a buyback that retired 1.23 million shares for $150M in Q3 📅 Next: Earnings call at 2:00 p.m. CEST today, October 23, 2026; Investor Day in Shanghai on April 26 and 27, 2027 Source: Autoliv Q3 release + SEC 8-K, Oct 23
Highlight

Read as text
$FLG Flagstar halves its 2027 profit guide to $400–500M from $800–900M. 🏢 Flagstar Bank, a regional bank with about 320 retail locations in nine states and strong footholds in greater New York/New Jersey and the upper Midwest, said in its Q3 release that full realization of its long-term objectives has shifted to 2028 from 2027 ✂️ Regional lender Flagstar Bank's investor deck, filed with its Q3 release, says its 2027 financial objectives have shifted to 2028: 2027 adjusted EPS guidance drops to $0.85–$0.95 from $1.60–$1.70, and the old 2027 net income and EPS targets become the 2028 forecast, with a higher 2028 loan-loss provision of $150–200M ✂️ With $67M earned through September, the new 2026 guide leaves only about $18–28M for Q4 ⚠️ The company blames higher rates, deposit competition, inflation and NYC rent regulation: 2027 net interest income is now seen at $2.2–2.3B against $2.5–2.65B before and the 2027 loan-loss provision at $175–225M against $100–150M 📉 At $11.44 (16:00 ET, October 22, 2026, market value about $4.75B), the stock trades at about 12–13.5 times the new 2027 adjusted EPS guide, against about 7 times the old one 📈 On the other side, 2028 keeps the old profit targets, the $11.44 close (16:00 ET, October 22, 2026) is 74% of $15.56 tangible book per share with warrants ($17.05 without), and 12.38% CET1 sits $1.2B above its 10.5% target floor 📅 Next: Q4 results will test the 2026 net income guide, cut to $85–95M from $225–300M Source: SEC 8-K investor deck + Q3 release, Oct 23
Highlight

Read as text
$ZYME Zymeworks licenses ZW209 to Roche for $55M upfront plus $40M at Phase 1b. 🏢 Zymeworks is a Vancouver biotech that collects money from licensed drugs such as Ziihera and YUPELRI while developing its own antibody drugs, and ZW209 is its experimental T-cell engager aimed at DLL3-expressing tumors such as small cell lung cancer ⚠️ Only the $55M upfront is committed, it is paid only after US antitrust (HSR) clearance, and Roche can end the agreement at any time by written notice 📈 The $55M equals about 31% of the $179.4M cash Zymeworks held on June 30, 2026, a balance from before the Theravance takeover closed on September 23 🤝 If Roche also starts the Phase 1b trial, which follows the Phase 1a trial now under way and has no date given, the two payments total $95M, about 4.7% of the roughly $2.02B market value at $28.44 at 16:00 ET on October 22, 2026 ⚠️ The other up to $718M in research, development, commercial and sales-based milestones is contingent, with no dates given, and Zymeworks may not do any DLL3 T-cell engager work of its own for up to five years ✅ In return Roche pays for the Phase 1a trial that Zymeworks runs and all later development, and Zymeworks keeps its platform patents plus high-single-digit to mid-teen royalties on any sales 📅 Next: Management call on October 27 at 8:30 am ET; the $55M upfront falls due once HSR clearance arrives Source: GlobeNewswire release, Oct 23 + SEC 8-K, Oct 23
Highlight
Read as text
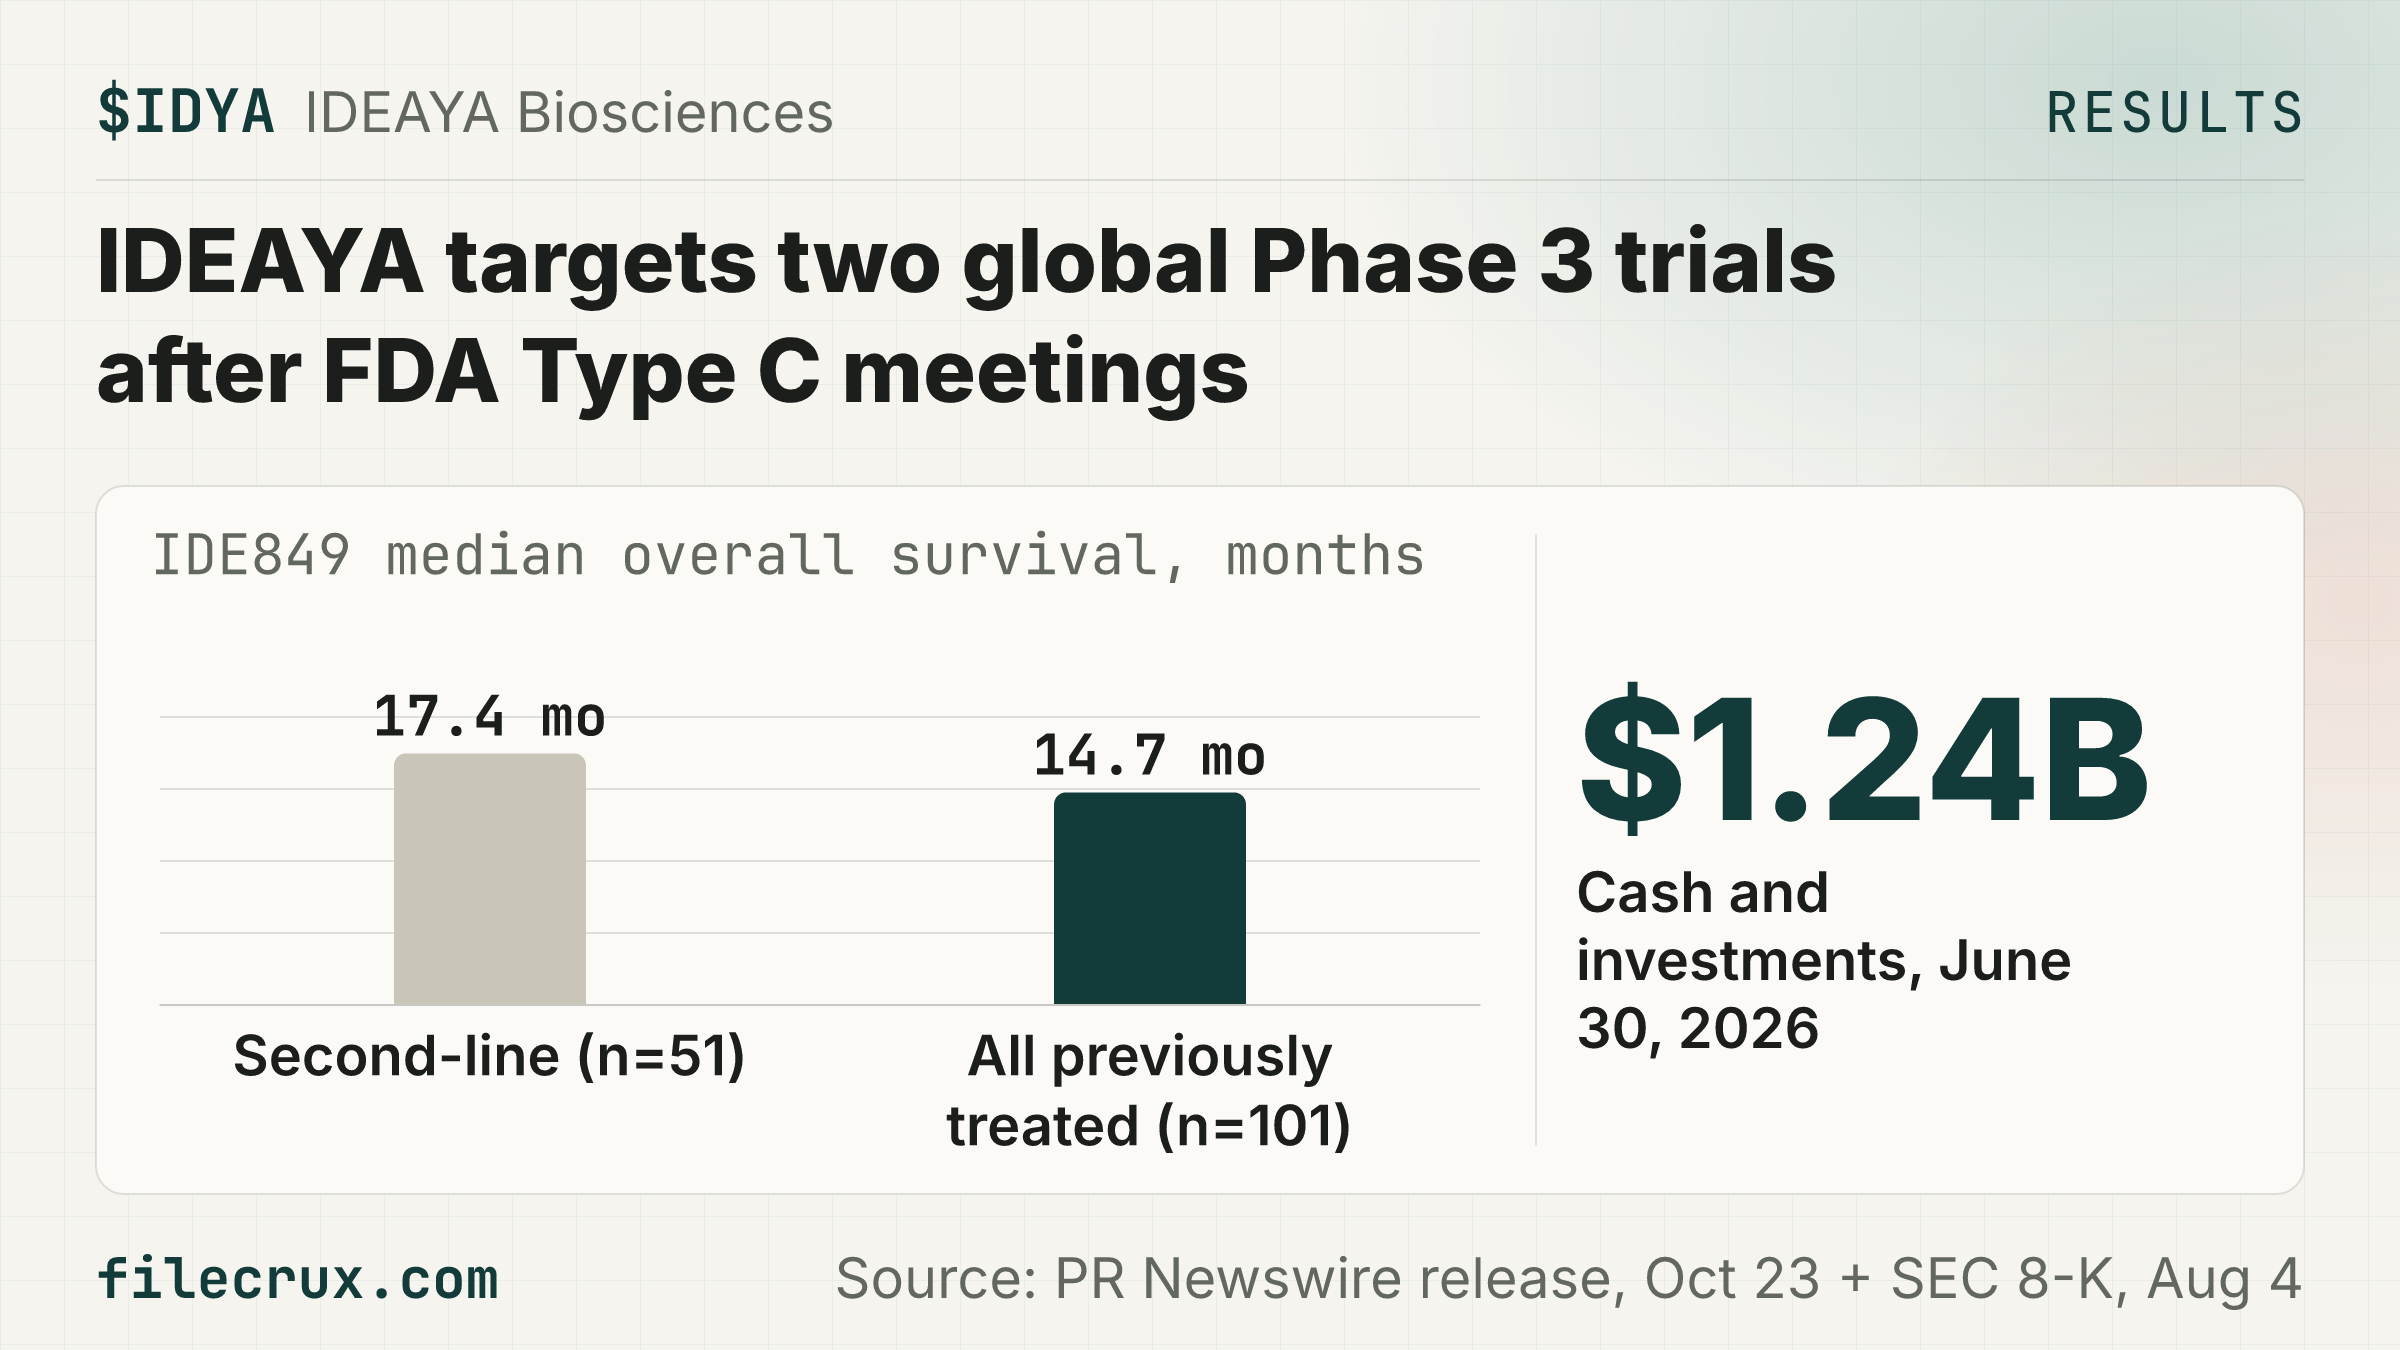
$IDYA Follow-up: cancer drug maker IDEAYA's IDE849 shows 17.4-month median OS in second-line lung cancer, two Phase 3s planned. 🏢 IDEAYA Biosciences, a cancer drug developer, licensed IDE849 outside Greater China from Hengrui in December 2024 📈 Hengrui's Phase 1 study in China (Aug 21, 2026 cutoff) gave 17.4-month median survival in second-line small cell lung cancer (n=51) and 14.7 months in 101 previously treated patients, beyond the 12-month landmark data the Aug 4, 2026 8-K promised 📈 After FDA Type C meetings, IDEAYA now plans two randomized global Phase 3s, in lung cancer after Imdelltra and in neuroendocrine carcinoma, where the August 8-K cited talks on one 🏦 Cash and investments of $1.24B at June 30, 2026 sit against a $3.49B market value at $36.12 (16:00 ET Oct 22, 2026) ⚠️ This is single-arm Phase 1 data with 53.9% of survival events in, a 95% confidence interval of 9.9 months to not reached on the 17.4-month second-line median, and 33.3% severe drug-related side effects at the 2.4 mg/kg dose versus 5% (1/20) at that dose in IDEAYA's own global study ⚠️ The release gives no Phase 3 start date, while the August 8-K aimed for a registrational start by the end of 2026 📅 Next: ESMO poster Monday, October 26; IDEAYA's own global study update comes by the end of 2026 or early in 2027 Source: PR Newswire release, Oct 23 + SEC 8-K, Aug 4
Highlight
Read as text
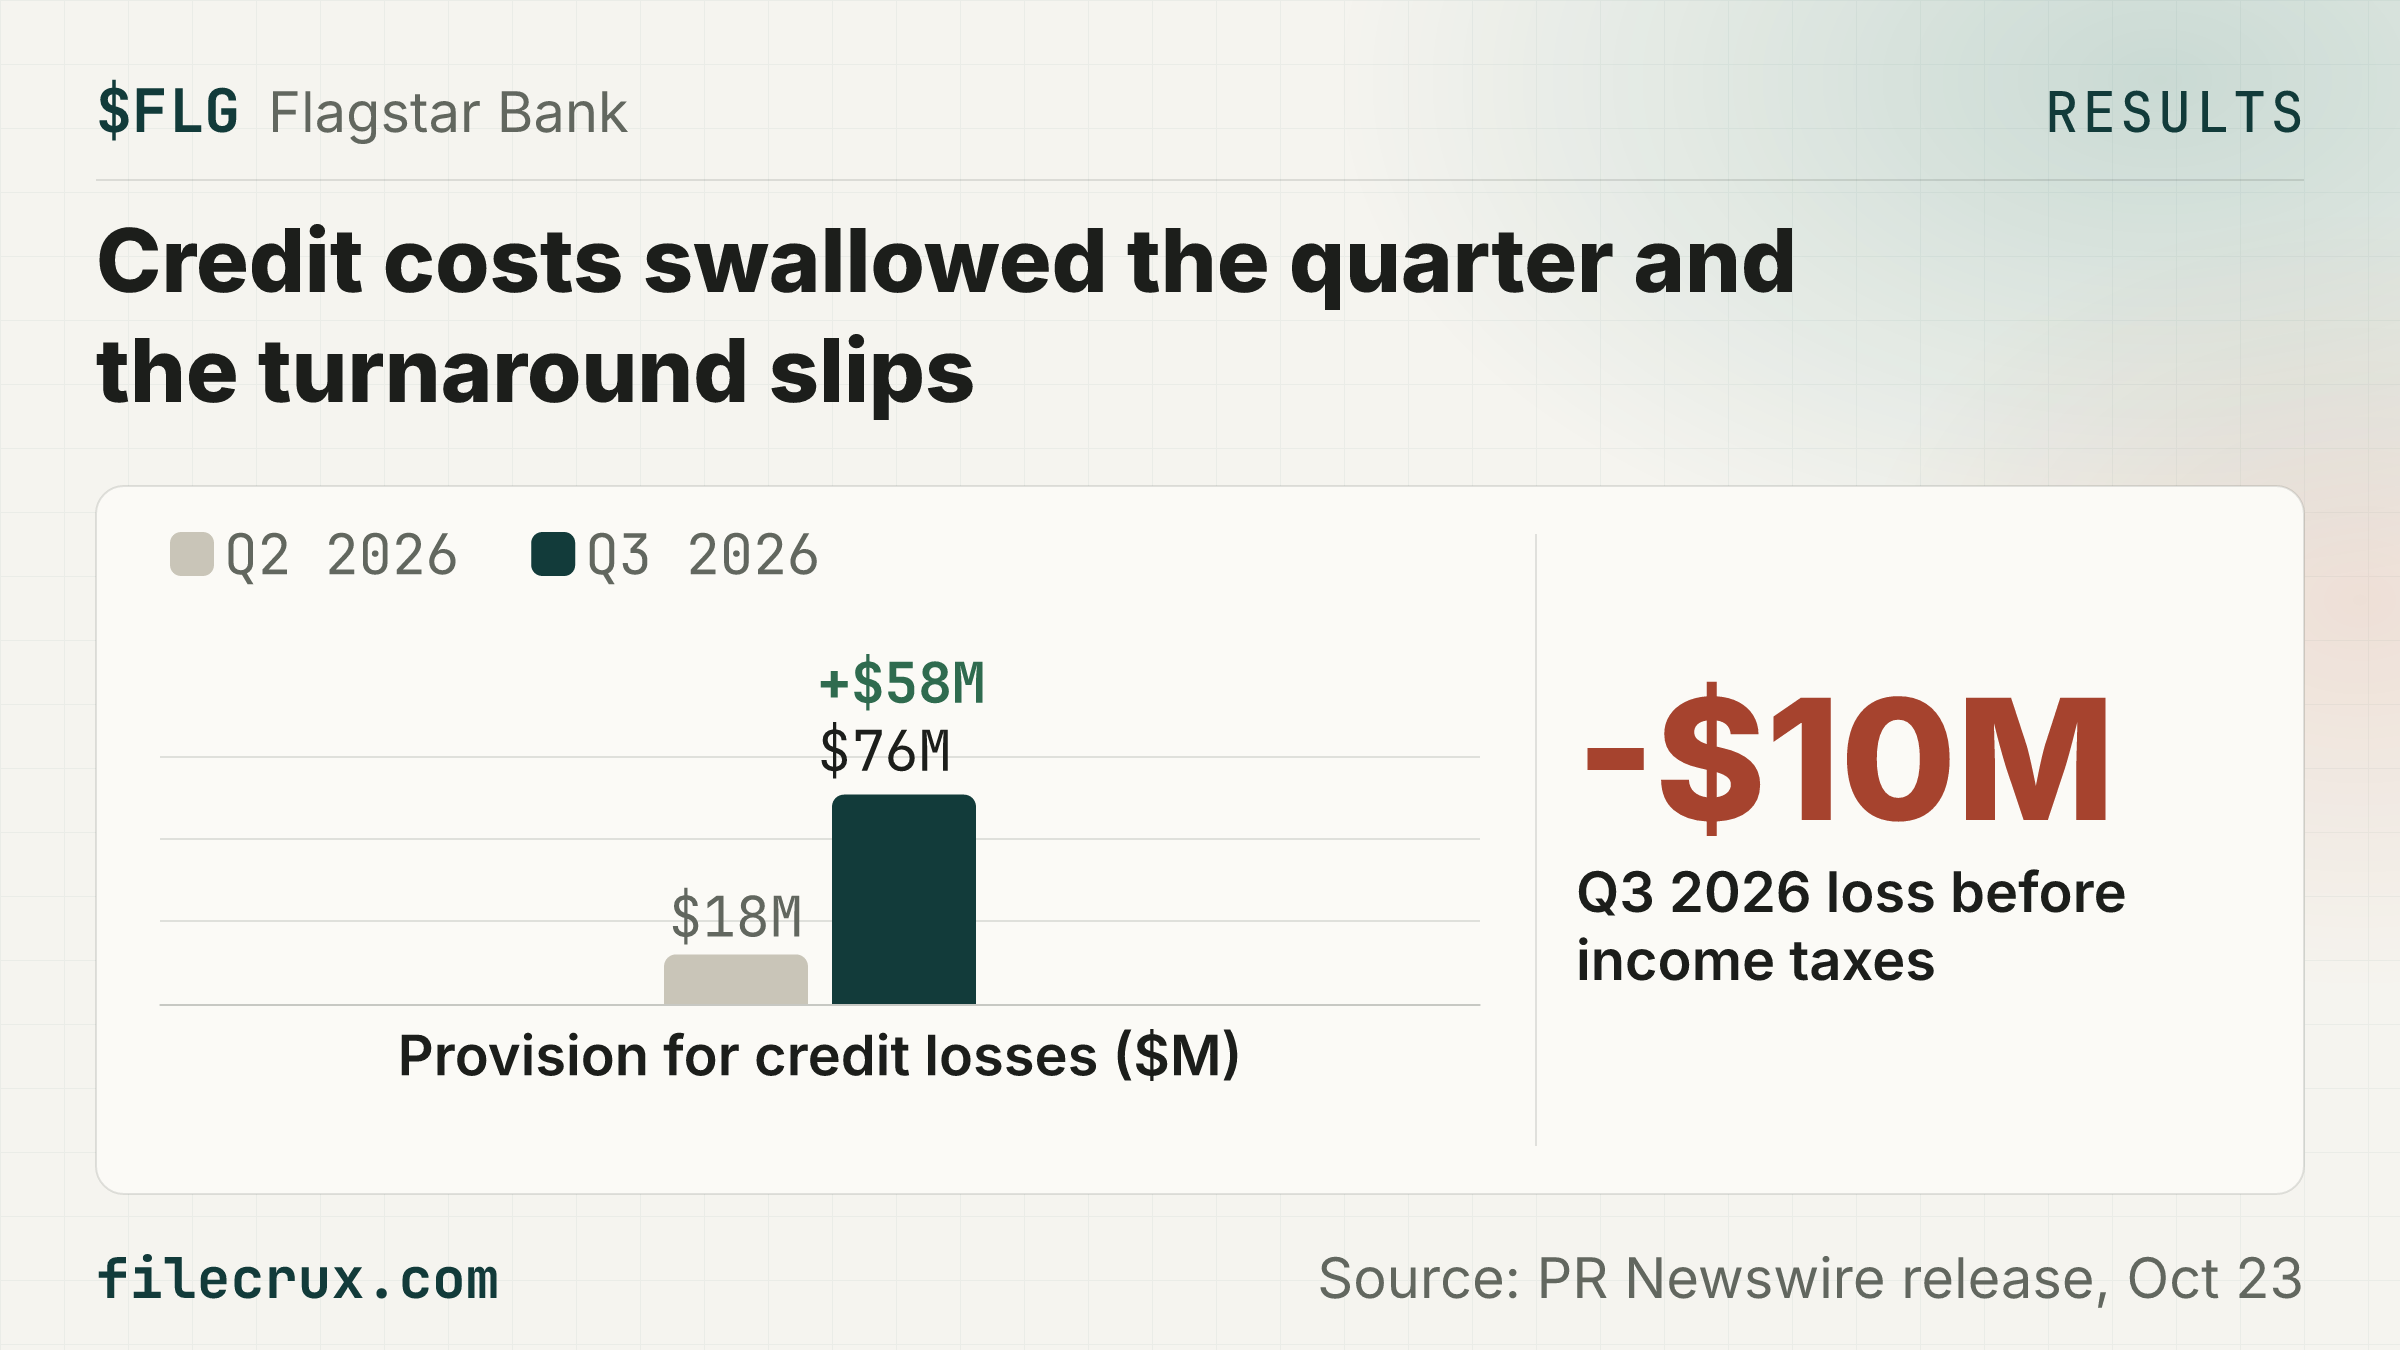
$FLG Flagstar Bank, an $87.4B-asset regional bank, lost $10M before tax in Q3; a one-time tax gain kept EPS at $0.01. 🏢 Flagstar Bank is a regional bank with $87.4B of assets and about 320 branches in nine states, centered on the New York/New Jersey area 🔥 Before tax, the bank lost $10M in Q3 after earning $48M before tax in Q2, and a one-time $22M tax benefit from settling a 2019-2021 federal audit is what left Q3 net income at $12M 📉 The $76M provision, up $58M from $18M, roughly matched net charge-offs with the reserve flat, as rate and rent-regulation reserve build was offset by multi-family runoff, and exceeded $66M pre-provision revenue ⚠️ The CEO pushed full delivery of the bank's long-term strategic targets to 2028 from 2027, citing higher-for-longer rates, so the earnings recovery holders are waiting for is a year further out ⚠️ At $11.44 a share (16:00 ET, October 22, 2026), the bank is worth about $4.75B, or roughly two-thirds of its $17.05 tangible book value per share, while Q3 return on tangible common equity was only 0.22% 📈 Underneath, the core business improved: net interest income rose 5% to $460M, business (C&I) loans grew 11% to $20.6B, net charge-offs fell to $74M from $100M, and a 12.38% CET1 capital ratio paid for a $250M buyback completed in early October 📅 Next: The earnings call was set for October 23, 2026 at 8:00 a.m. (Eastern Time); watch whether management puts numbers on the 2028 targets and on credit costs in the rent-regulated book Source: PR Newswire release, Oct 23
Highlight

Read as text
$ALNY Alnylam plans a 2027 pivotal Huntington's study, pending regulator alignment, after one top dose cut spinal-fluid mutant huntingtin by a mean 60-64% at month 3. 🏢 Alnylam Pharmaceuticals is the RNAi drug maker behind AMVUTTRA for ATTR amyloidosis, and it is developing brezosiran for Huntington's disease with Regeneron 📈 In the top dose group so far, one spinal injection cut mutant huntingtin in spinal fluid by a mean 60% to 64% at month 3, and by up to 83% in one patient; the study has enrolled 48 patients in total across five dose cohorts 📈 Over up to 12 months, higher doses brought no rise in NfL, a nerve-damage marker, or in inflammatory markers, and the lasting effect points to dosing twice a year 🏢 At a $30.41B market value ($227.28 at 16:00 ET on October 22, 2026), the stock rides on TTR drugs that sold $1,030M in Q2 2026, and Alnylam held $3.31B of cash and investments at June 30, 2026 ⚠️ The case against: these are single doses in a small early study, spinal-fluid huntingtin is a marker rather than proof of slower disease, and the 2027 start still needs regulators to agree 📅 Next: Alnylam discusses the data at its RNAi Roundtable on October 26, 2026, at 10:00 a.m. ET; watch for the pivotal design and chosen dose Source: Business Wire release, Oct 23 + SEC 8-K, Jul 30
Highlight

Read as text
$ORIC Enozertinib shows 84% response in untreated atypical EGFR lung cancer, Phase 3 planned. 🏢 ORIC Pharmaceuticals is a clinical-stage cancer drug developer with two drugs in the clinic: rinzimetostat for prostate cancer and enozertinib for lung cancer 📈 In a Phase 1b trial of enozertinib, from clinical-stage cancer drug developer ORIC, in untreated lung cancer with atypical EGFR mutations, 84% (21 of 25) of patients responded by investigator and 80% by blinded central review, though 65% had brain metastases 📈 Brain tumors responded in 70% of the 10 patients with measurable brain lesions by investigator, and no patient stopped the drug because of side effects 🤝 Redwood-1 will randomize about 360 patients to enozertinib or osimertinib or afatinib, with central-review response rate as a primary endpoint for potential accelerated approval, so a filing need not wait for progression-free survival 🔥 ORIC held $387.6M in cash and investments at June 30, 2026, about 27% of its $1.41B market value at $13.63 at 16:00 ET on October 22, 2026, against $45.3M of second-quarter operating costs, and the company expects it to fund its plan into the second half of 2028 ⚠️ The bear case is that this is a single-arm readout in 25 patients, median progression-free survival is immature, 23% had Grade 3 side effects, and rival comparisons are cross-trial 📅 Next: Conference call today at 8:00 a.m. ET, ESMO poster Monday, October 26, 2026, and the start of Redwood-1 expected in 1H 2027 Source: GlobeNewswire release, Oct 23 + SEC 8-K, Aug 3
Report
Deckers cuts sales outlook; tariff refunds carry its higher profit guide
Highlight
Read as text
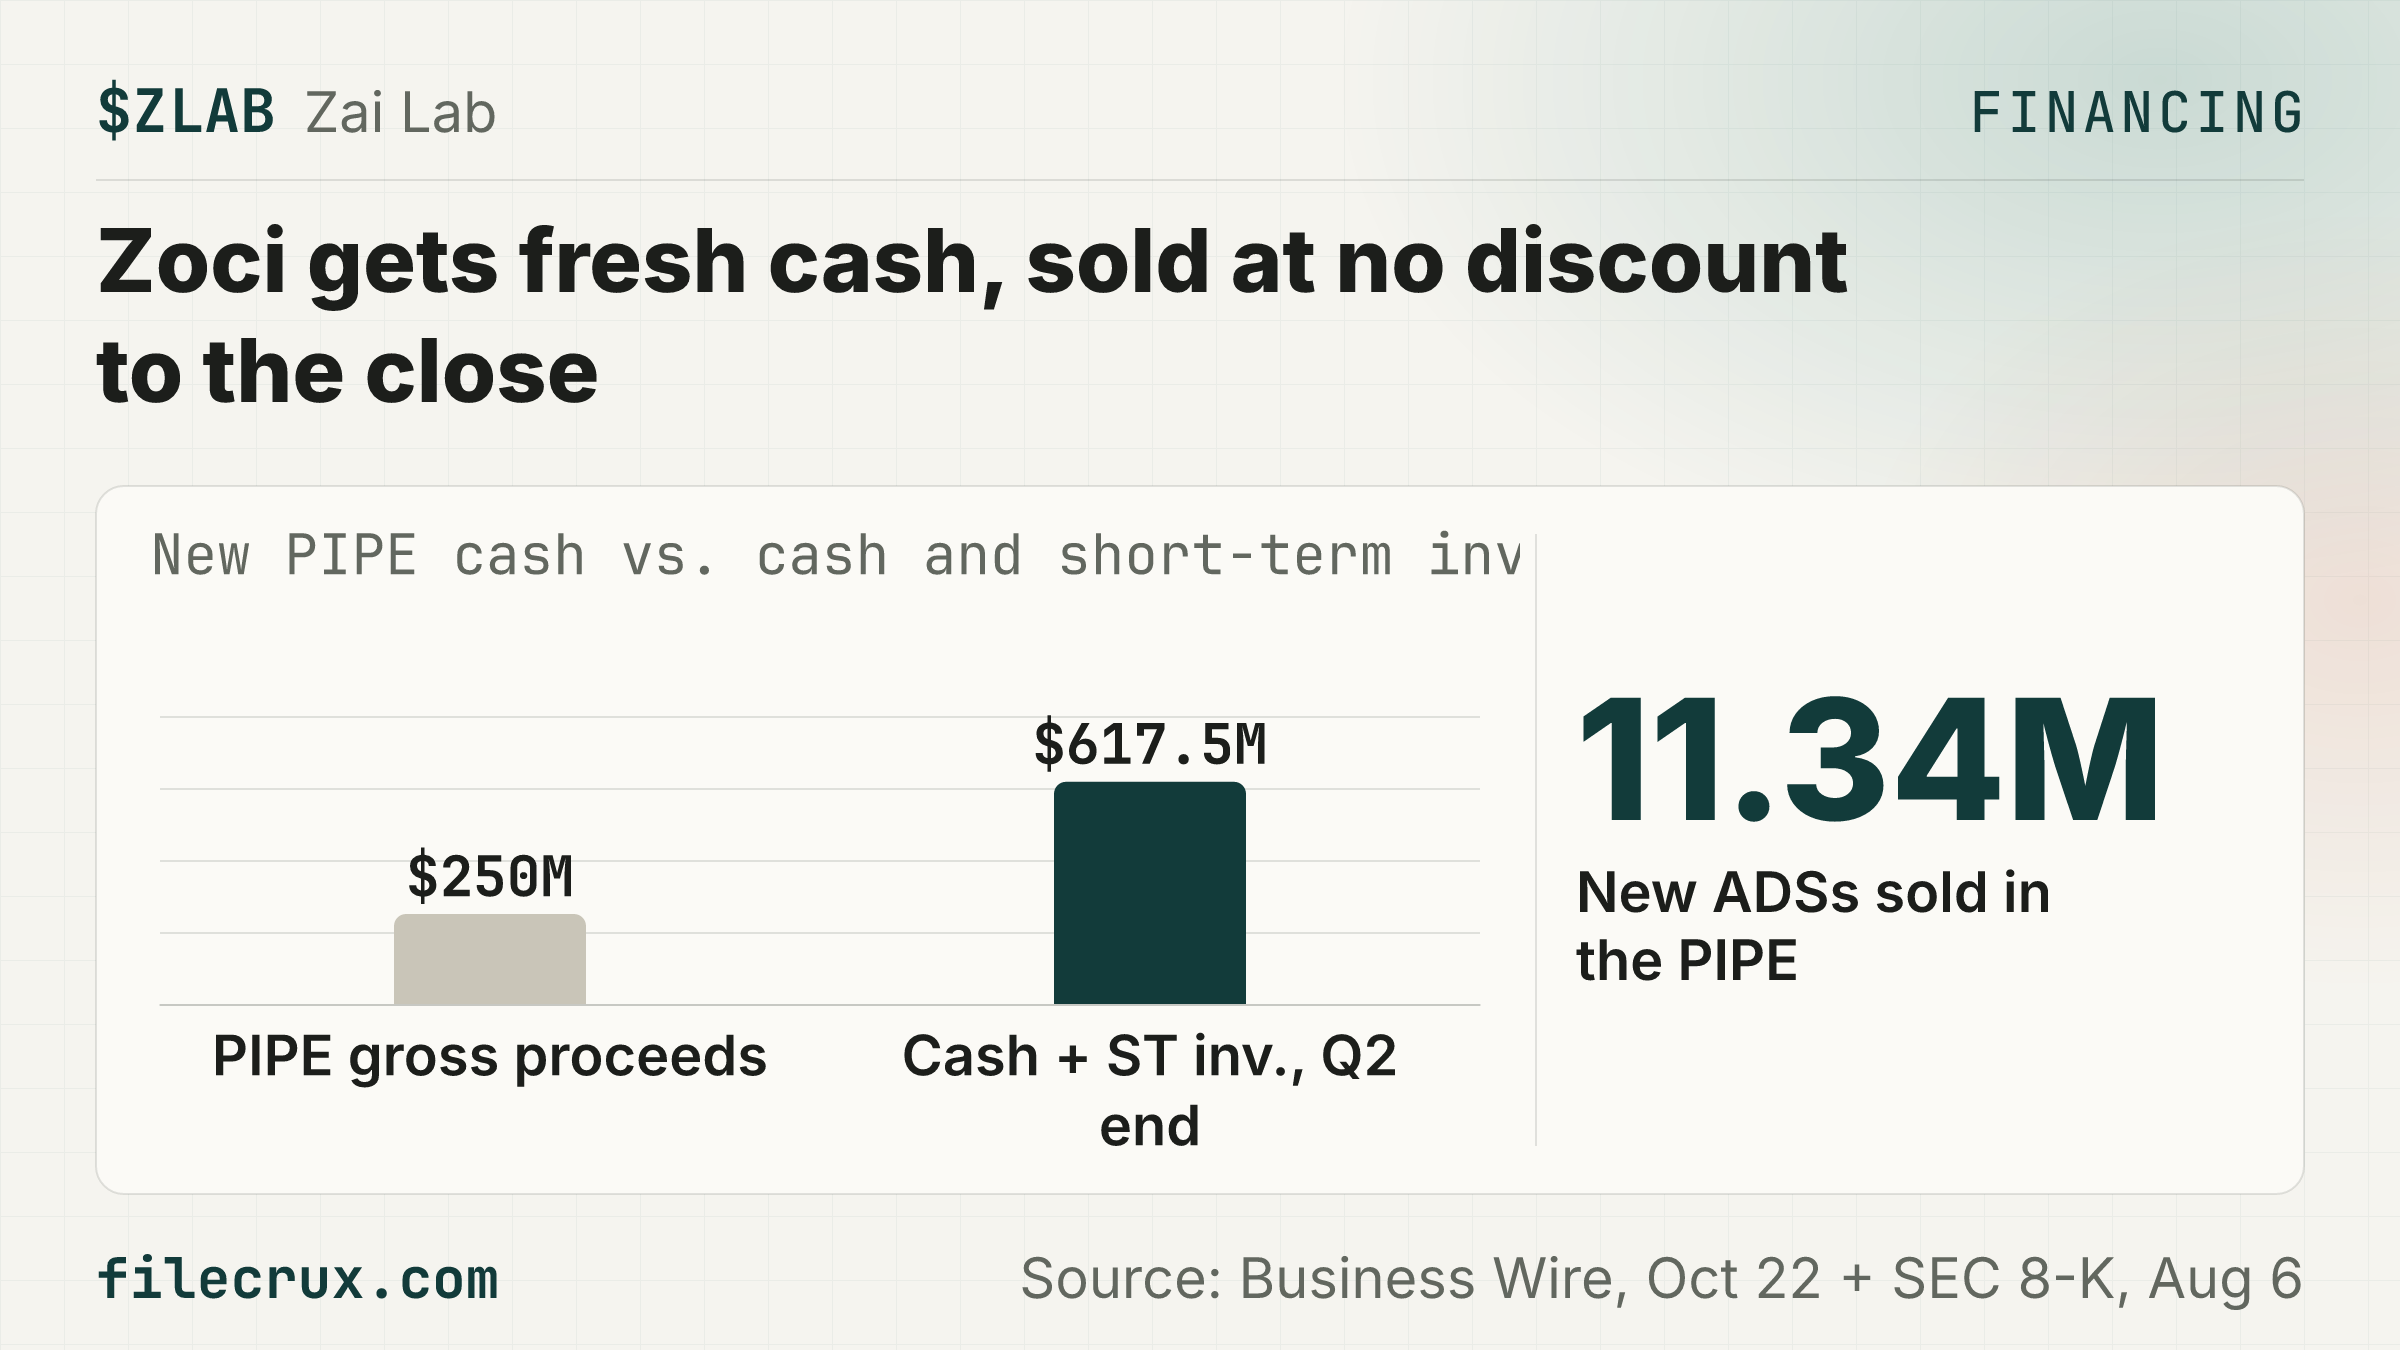
$ZLAB Zai Lab sells $250M of new ADSs to TCGX-led investors. 🏢 Commercial-stage biopharma based in China and the US 🏦 The 11.34M new ADSs are priced at the 16:00 ET October 22, 2026 close, about 10% more ADSs 🏦 $250M is about 10% of the ~$2.47B market value at that close 🏦 It equals about 40% of the $617.5M in cash and short-term investments at the end of Q2 2026 🤝 In return the cash mainly funds zoci, its DLL3 drug in Phase 3 for lung cancer, vs a $76.5M Q2 2026 operating loss 📅 Next: PIPE expected to close on or about October 27, 2026 Source: Business Wire, Oct 22 + SEC 8-K, Aug 6
Report
RingCentral beats and raises; its $6.50 profit per share is mostly tax
Highlight

Read as text
$HURN Huron Consulting to join S&P SmallCap 600 before the open on Nov 2. 🏢 Global professional services firm, with 50% of 2026 first-half revenue from healthcare clients 🤝 It replaces Supernus Pharmaceuticals, which Indivior is acquiring 🏢 Market value is about $3.13B at $193.35 a share, 16:00 ET Oct 22, 2026 ⚠️ LT debt $812.8M at June 30 📈 In July Huron raised its full-year 2026 revenue (before reimbursable expenses) guidance to $1.85 billion to $1.89 billion 📅 Next: Huron joins the index prior to the opening of trading on Monday, November 2 Source: S&P DJI release, PR Newswire, Oct 22 + SEC 8-K, Jul 28
Report
TTM forecasts at least $6.5 billion in 2027 sales; shares fall 27.6%
Highlight
Read as text
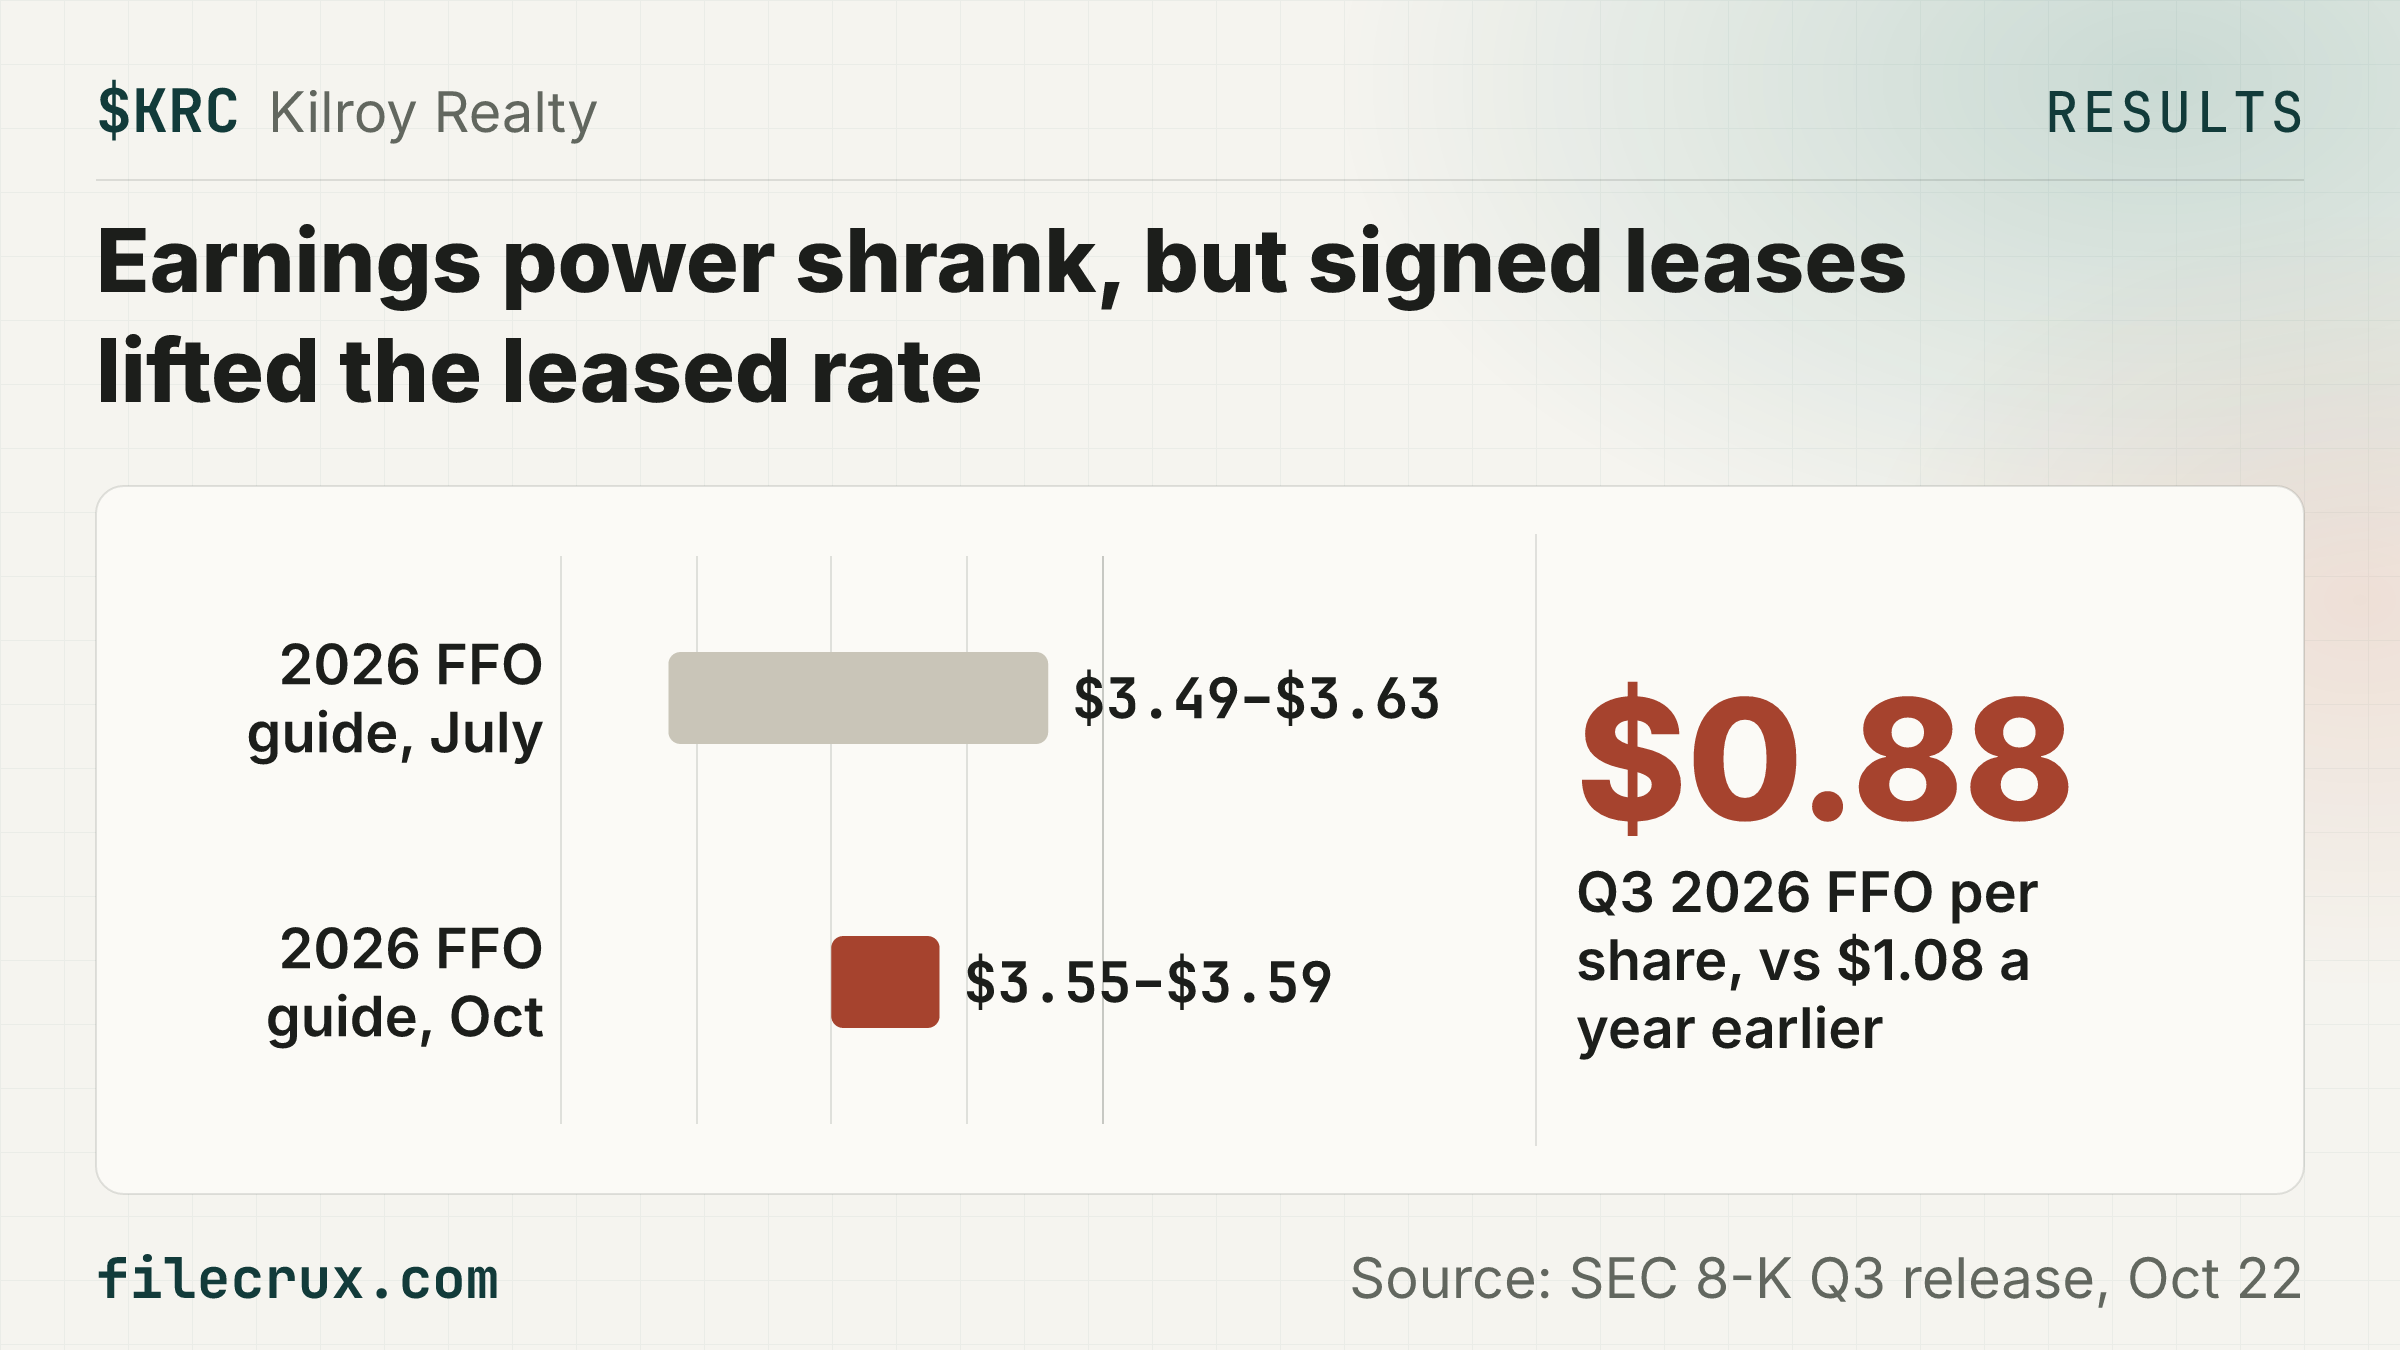
$KRC Kilroy Q3 FFO fell 18.5% to $0.88 a share; full-year guide narrowed. 🏢 Office and life science REIT in SF, LA, Seattle, San Diego and Austin, 17.1M sq ft stabilized 📉 Q3 2025 FFO was $1.08 🏢 Market value about $4.18B at $35.955 a share, 16:00 ET Oct 22, 2026 📈 Leased 83.0% vs 81.5% June 30; 2026 FFO guide $3.55–$3.59 from $3.49–$3.63 ⚠️ Occupancy slipped to 76.9% at Sept 30 from 77.0% at June 30 and 81.0% a year earlier; the gap to 83.0% leased is signed leases not yet commenced 📅 Next: Earnings call October 23, 2026, 10:00 a.m. Pacific Time Source: SEC 8-K Q3 release, Oct 22
Highlight

Read as text
$RNG RingCentral's $569.7M Q3 GAAP profit was mostly a $544.9M non-cash tax benefit. 🏢 RingCentral sells AI-powered business phone and contact center software 📈 Excluding the valuation allowance release on U.S. deferred tax assets, Q3 GAAP diluted EPS was $0.28, up 47.4%, not $6.50 🏢 The $544.9M is about 7% of its ~$7.55B market value at $89.78, 16:50 ET Oct 22, 2026 🚀 No cash came with it; Q3 free cash flow was $157M, and 2026 FCF guidance rose to $620–630M 📅 Next: $0.125 dividend payable November 20, 2026, record date November 6, 2026 Source: RingCentral Q3 release, SEC 8-K, Oct 22, 2026
Highlight
Read as text
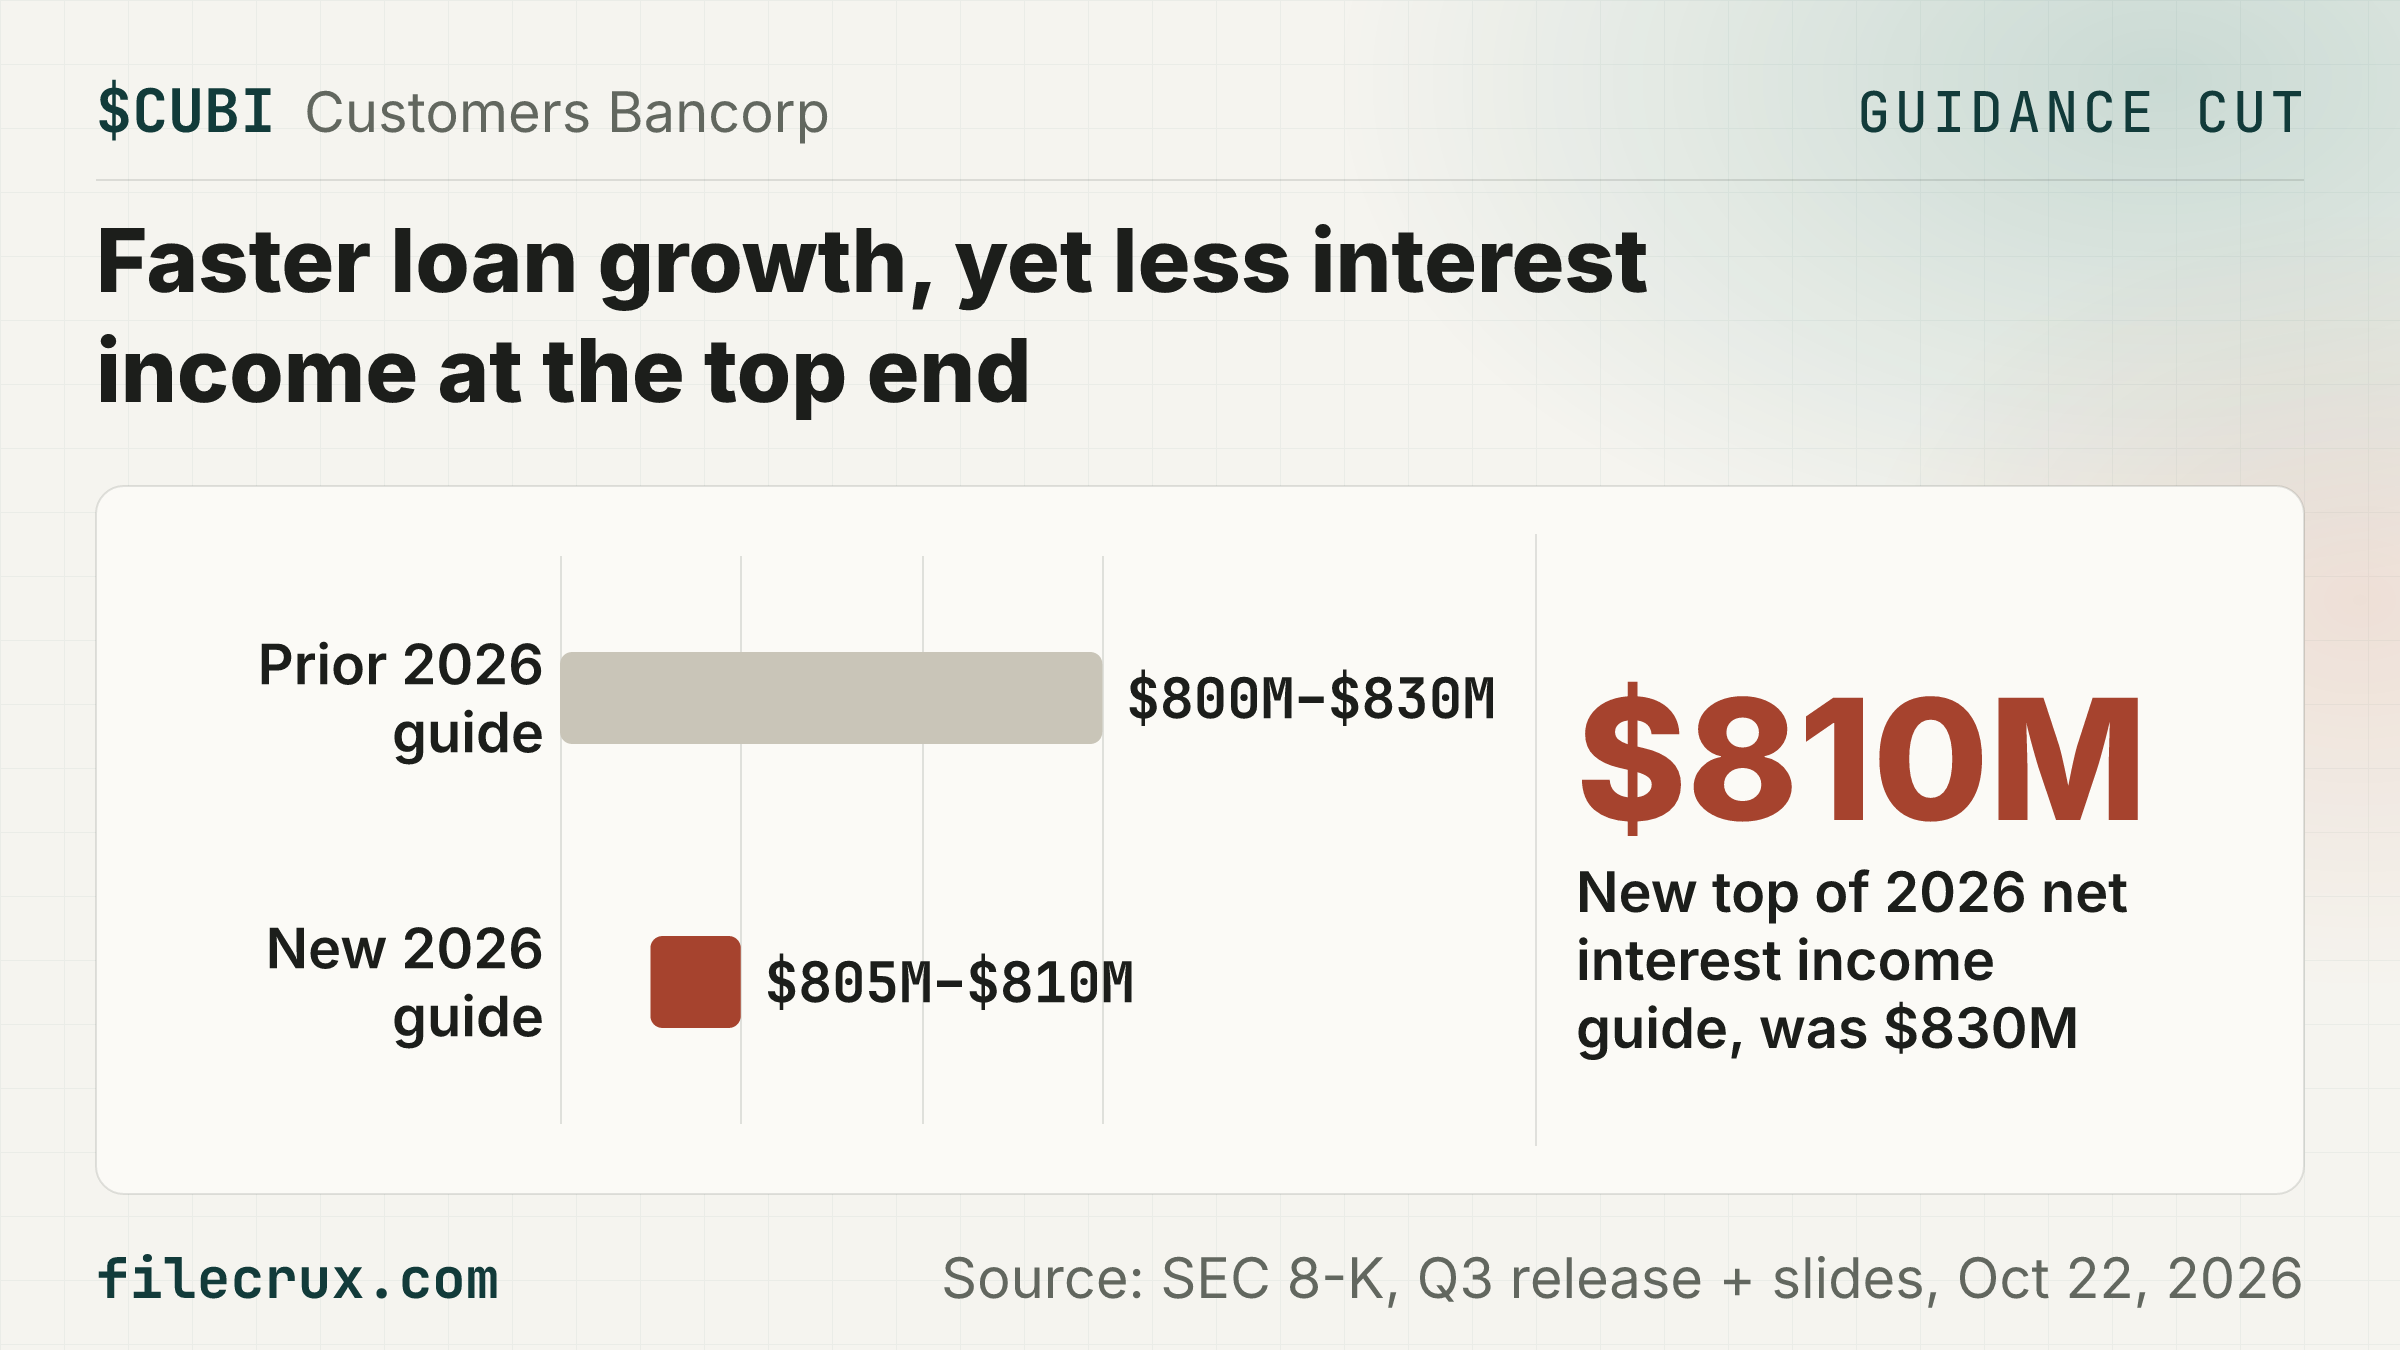
$CUBI Customers Bancorp trims 2026 net interest income guide to $805M–$810M from $800M–$830M. 🏢 Pennsylvania commercial bank: $27.4B assets at Sept 30; ~$2.66B market value at $78.73, 15:59 ET Oct 22, 2026 ⚠️ Expense guide up to $460M–$465M from $440M–$460M, implying ~$120M–$125M in Q4 vs $113.4M in Q3 🚀 Loan growth guide raised to 12%+ from 8–12%; Q3 EPS $2.25 vs $2.05 in Q2 📈 Other side: Q3 NII rose 7.6% q/q to $208M; slides see Q4 margin up from a ~3.25% September run rate 📅 Next: Earnings webcast Friday, October 23, 2026, 9:00 AM EDT Source: SEC 8-K, Q3 release + slides, Oct 22, 2026
Highlight
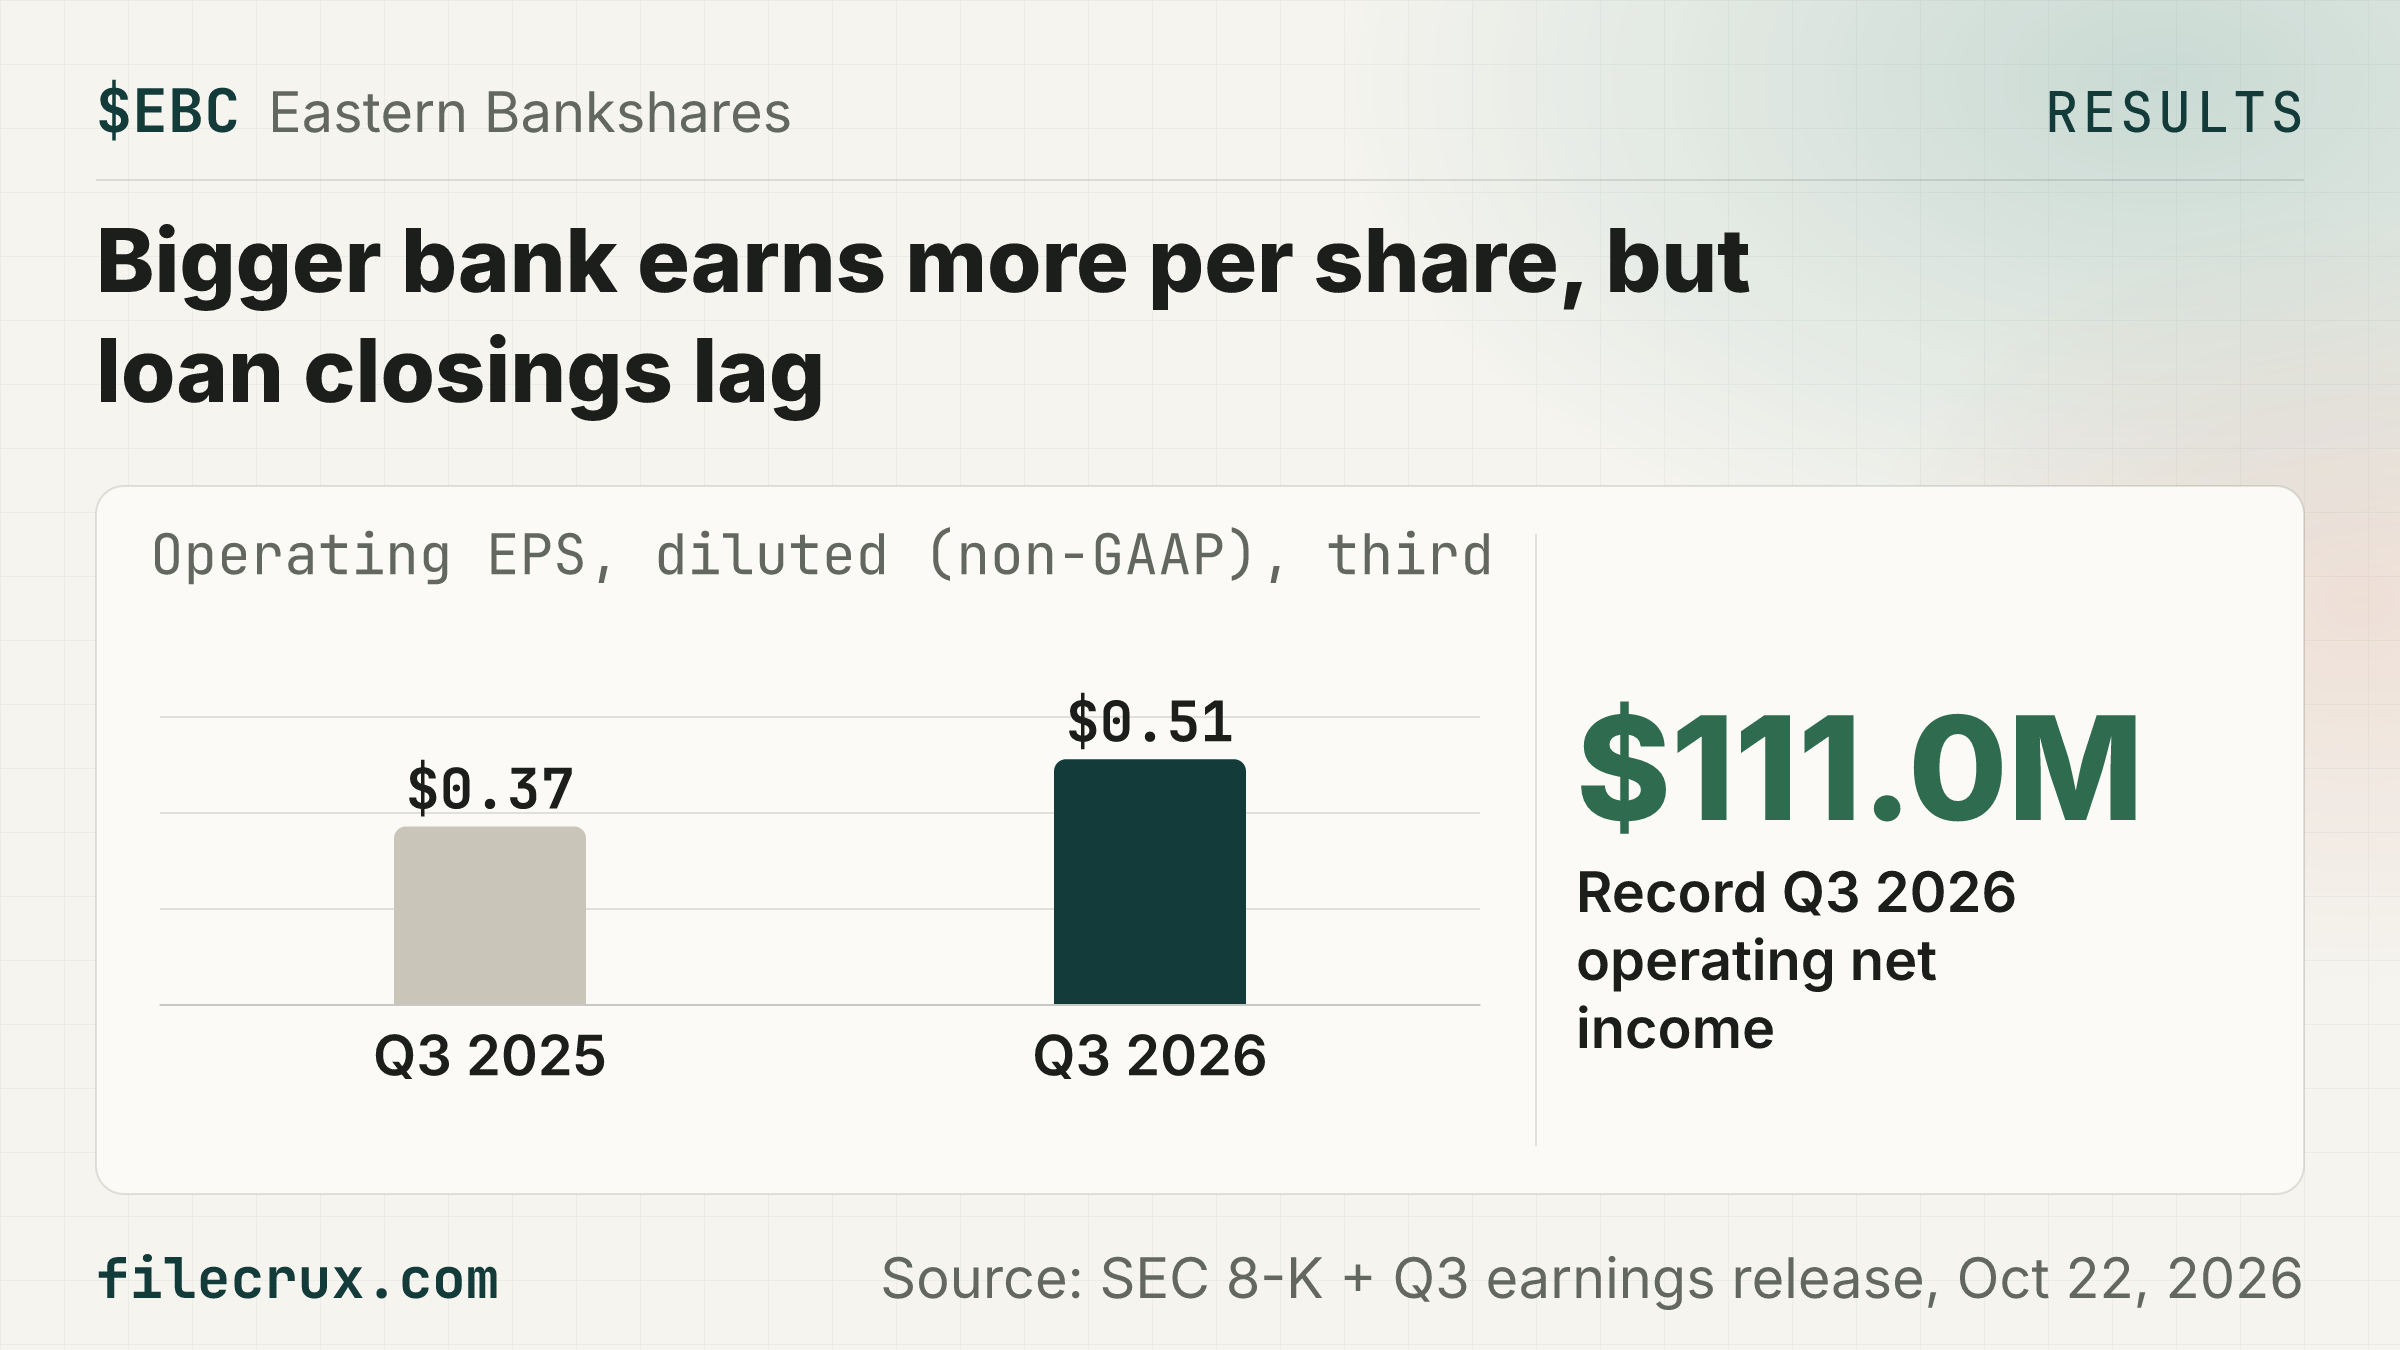
Read as text
$EBC Eastern Bankshares Q3 operating income hits record $111.0M, $0.51 a share. 🏢 Parent of Eastern Bank, a Greater Boston lender with $31.7B in assets 📈 Operating EPS was $0.37 a year ago, before the HarborOne merger; Q3 revenue $306.6M vs $241.5M 🏢 Market value about $5.06B at $22.125 (16:00 ET, October 22, 2026), ~10.8x annualized Q3 operating EPS ⚠️ GAAP EPS of $0.51 trails $0.53 a year ago, which had a tax benefit; CEO says loan closings are somewhat slower than anticipated 📅 Next: Webcast October 23, 2026; $0.15 dividend due December 21, 2026 Source: SEC 8-K + Q3 earnings release, Oct 22, 2026
Highlight

Read as text
$SLM Sallie Mae swings to Q3 loss, cuts 2026 EPS guide to $1.95–$2.05 from $3.10–$3.20. 🏢 Sallie Mae (SLM Corp) calls itself the leader in private student lending ✂️ Midpoint is ~37% lower; net charge-off guide rises to $400–420M from $365–385M ⚠️ At $21.8 (16:42 ET, Oct 22, 2026) SLM is worth ~$4.10B, ~10.9x the new guide midpoint 🔥 Q3 diluted loss of $0.19 a share vs. $0.63 profit a year ago 🏆 Other side: record $3.4B Q3 originations, up 15%, which the company says mainly drove the loss 📅 Next: Earnings call Oct. 22, 2026, 5:30 p.m. ET Source: SEC 8-K + 10-Q, Oct 22
Highlight

Read as text
$HTH Hilltop Q3 profit fell 46% to $24.9M as broker-dealer pre-tax income fell to $6.8M from $26.5M and a $10.2M credit provision replaced a $2.5M reversal a year ago. 🏢 Dallas financial holding company: Texas bank PlainsCapital, mortgage lender PrimeLending and broker-dealer HilltopSecurities 🏢 Market value about $2.14B at $37.285 (16:30 ET, October 22, 2026) ✅ Offsets: net interest margin rose to 3.33% from 3.21% in Q2, deposits grew to $11.0B from $10.5B, and CET1 capital stood at 18.28% 📅 Next: Earnings call Friday, October 23, 2026 Source: Hilltop Q3 release, SEC 8-K, Oct 22
Highlight
Read as text
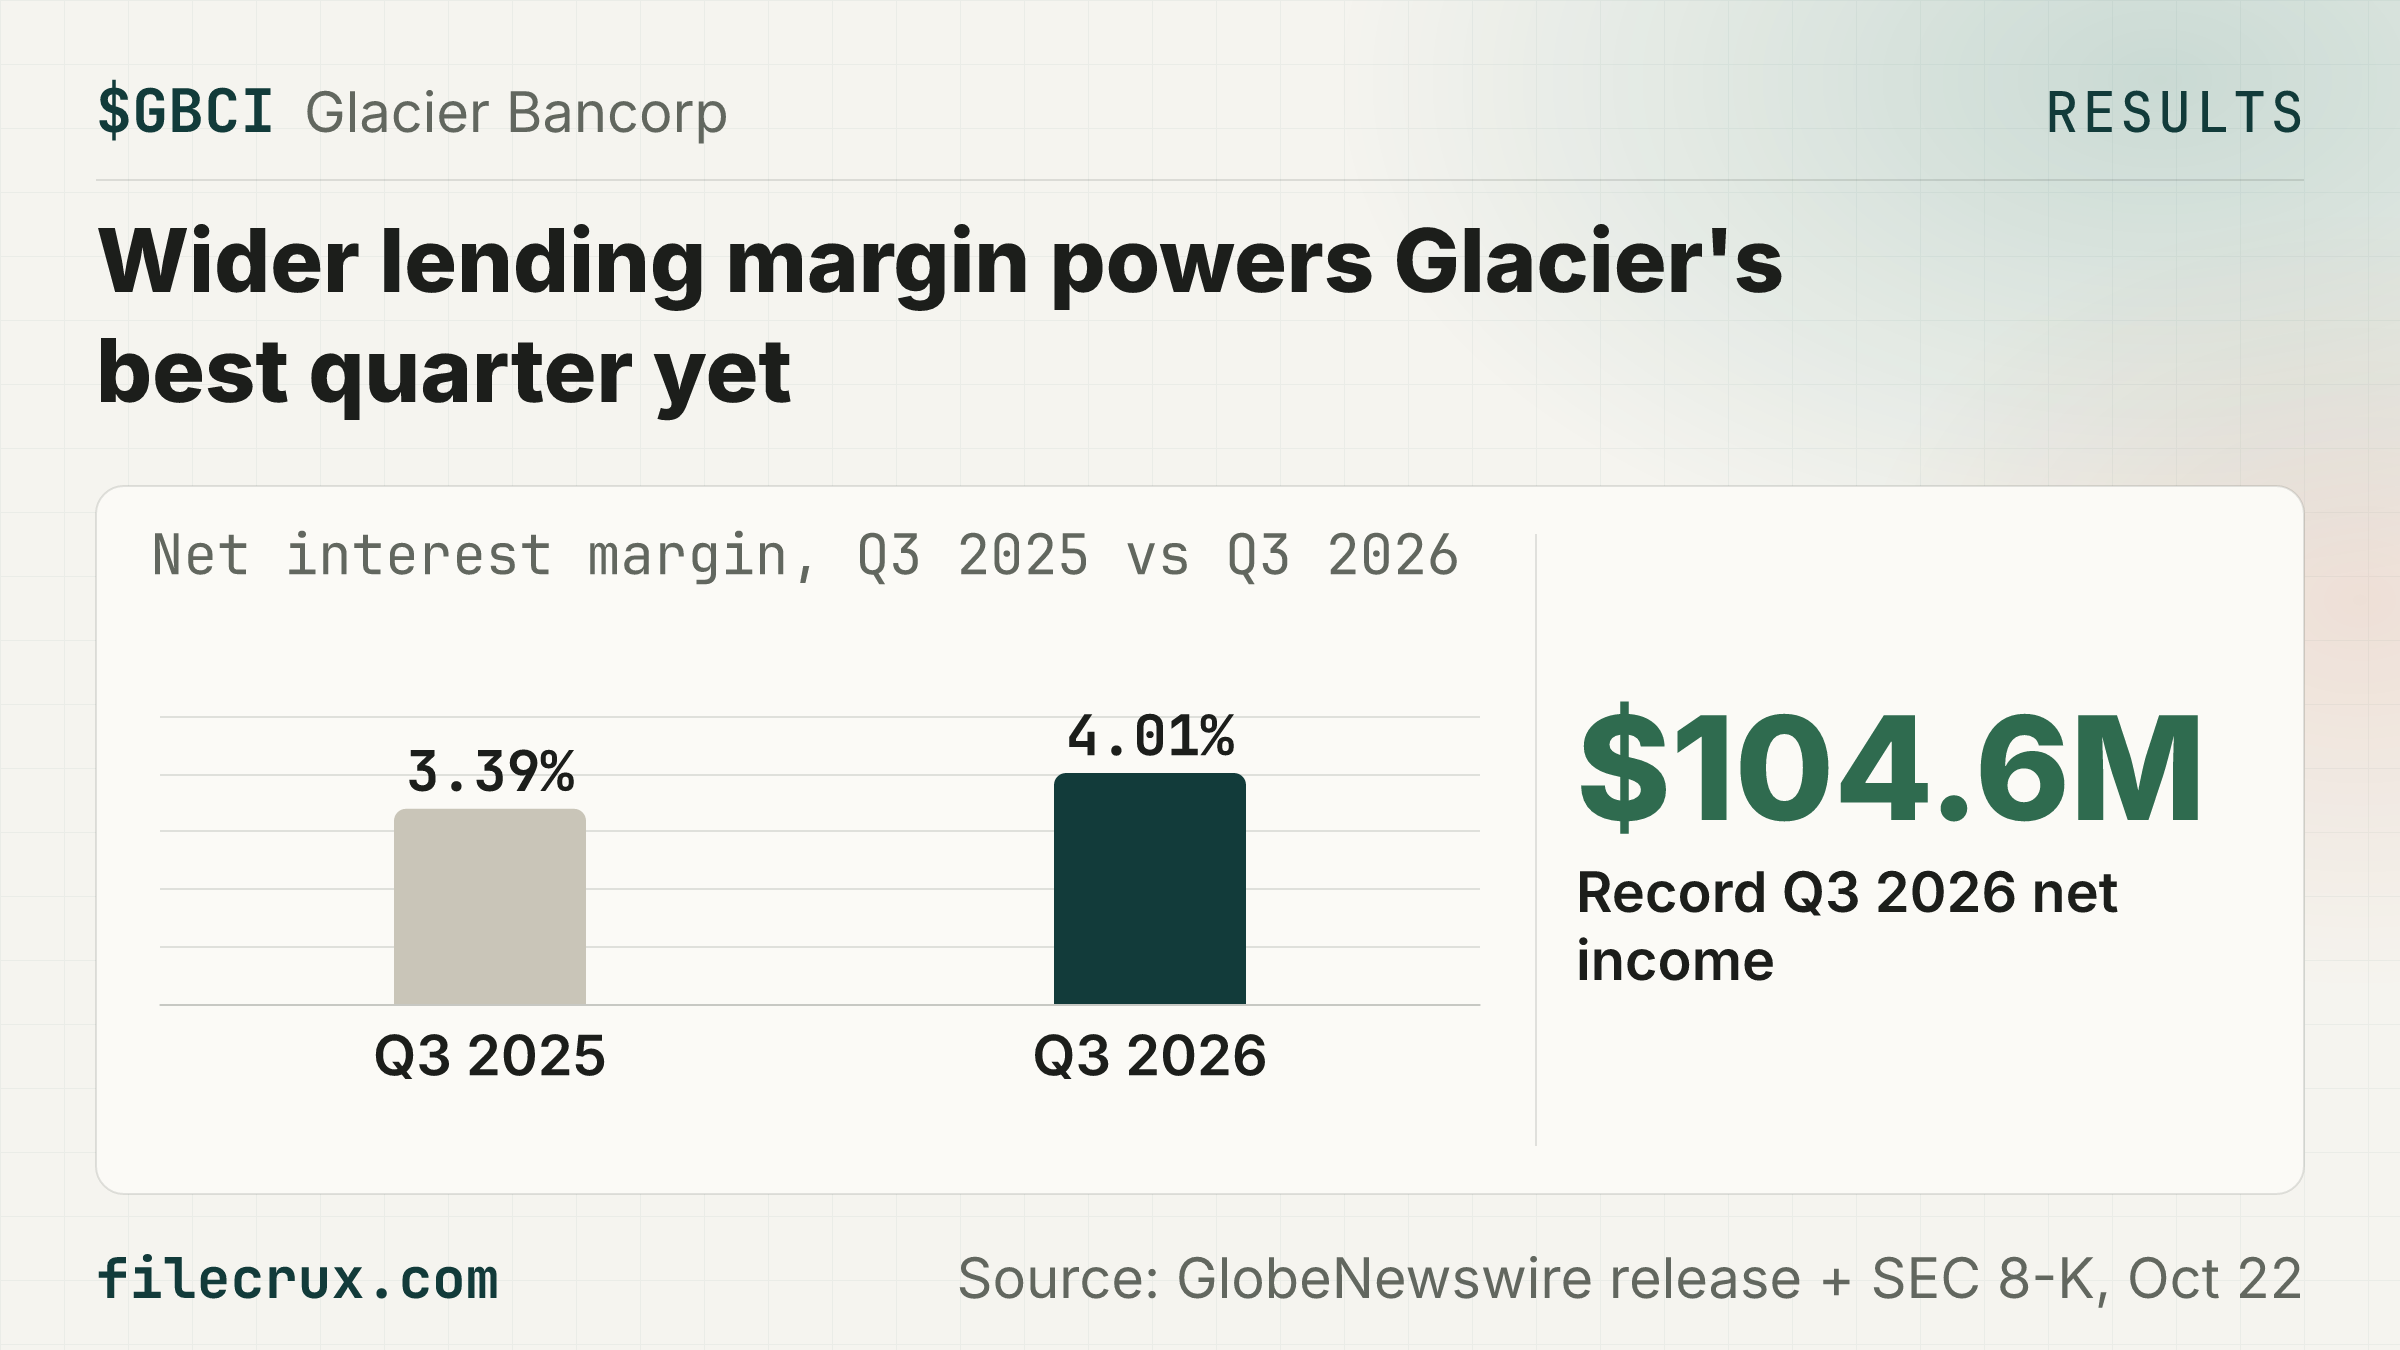
$GBCI Glacier Bancorp Q3 net income a record $104.6M, up 54% from a year ago. 🏢 Montana-based parent of Glacier Bank; $32.29B assets at Sep 30, 2026, about $5.99B market value at $46.005 (16:00 ET, Oct 22, 2026) 📈 Diluted EPS $0.80, up 40%; net interest margin widened to 4.01% from 3.39% a year earlier, and net interest income rose 29% to $290M ⚠️ Guaranty deal (closed Oct 1, 2025, $560M stock) adds to gain; non-performing assets up 67% in a year to $90.6M, down 1% from Q2 📅 Next: Conference call 11:00 a.m. Eastern Time, Friday, October 23, 2026 Source: GlobeNewswire release + SEC 8-K, Oct 22
Highlight

Read as text
$AMTB Amerant raises buyback room to $50M from about $3M as Q3 profit climbs. 🏢 Coral Gables, Florida bank holding company with $10.2B in assets 💰 $50M is about 4.3% of its ~$1.16B market value at $29.69 (16:00 ET, Oct 22, 2026); the program now runs to Dec 31, 2027 📈 Q3 2026 net income $25.7M vs $14.8M a year ago; Q4 margin projected 3.65%-3.70%, below Q3's 3.77% 📉 Book value per share fell to $21.49 from $23.33 in Q2 as accumulated other comprehensive loss grew to $118.9M, and no buying is required 📅 Next: Q3 results webcast, October 23, 2026 Source: SEC 8-K and Q3 release, Oct 22
Highlight

Read as text
$LBRT Follow-up: Lenders lift frac firm Liberty Energy's leverage cap to 4.50x from 3.50x. 🏢 Liberty was worth ~$2.51B at $15.385/share, 16:00 ET Oct 22, 2026 🏦 An Oct 20 amendment with JPMorgan-led banks holds 4.50x through Q1 2027, then 4.25x, 4.00x, 3.75x 🏦 $750M revolver undrawn at Sept 30, but a $580.1M borrowing base less $30.2M of LCs left $549.9M ⚠️ $1.295B of 0% converts is due 2031-32, but $1.6B is owed on power equipment vs ~$669M liquidity (Oct 21) 📅 Next: Cap returns to 3.50x for quarters ending on or after March 31, 2028 Source: SEC 10-Q, Oct 22 + 8-K, Oct 21
Highlight
Read as text
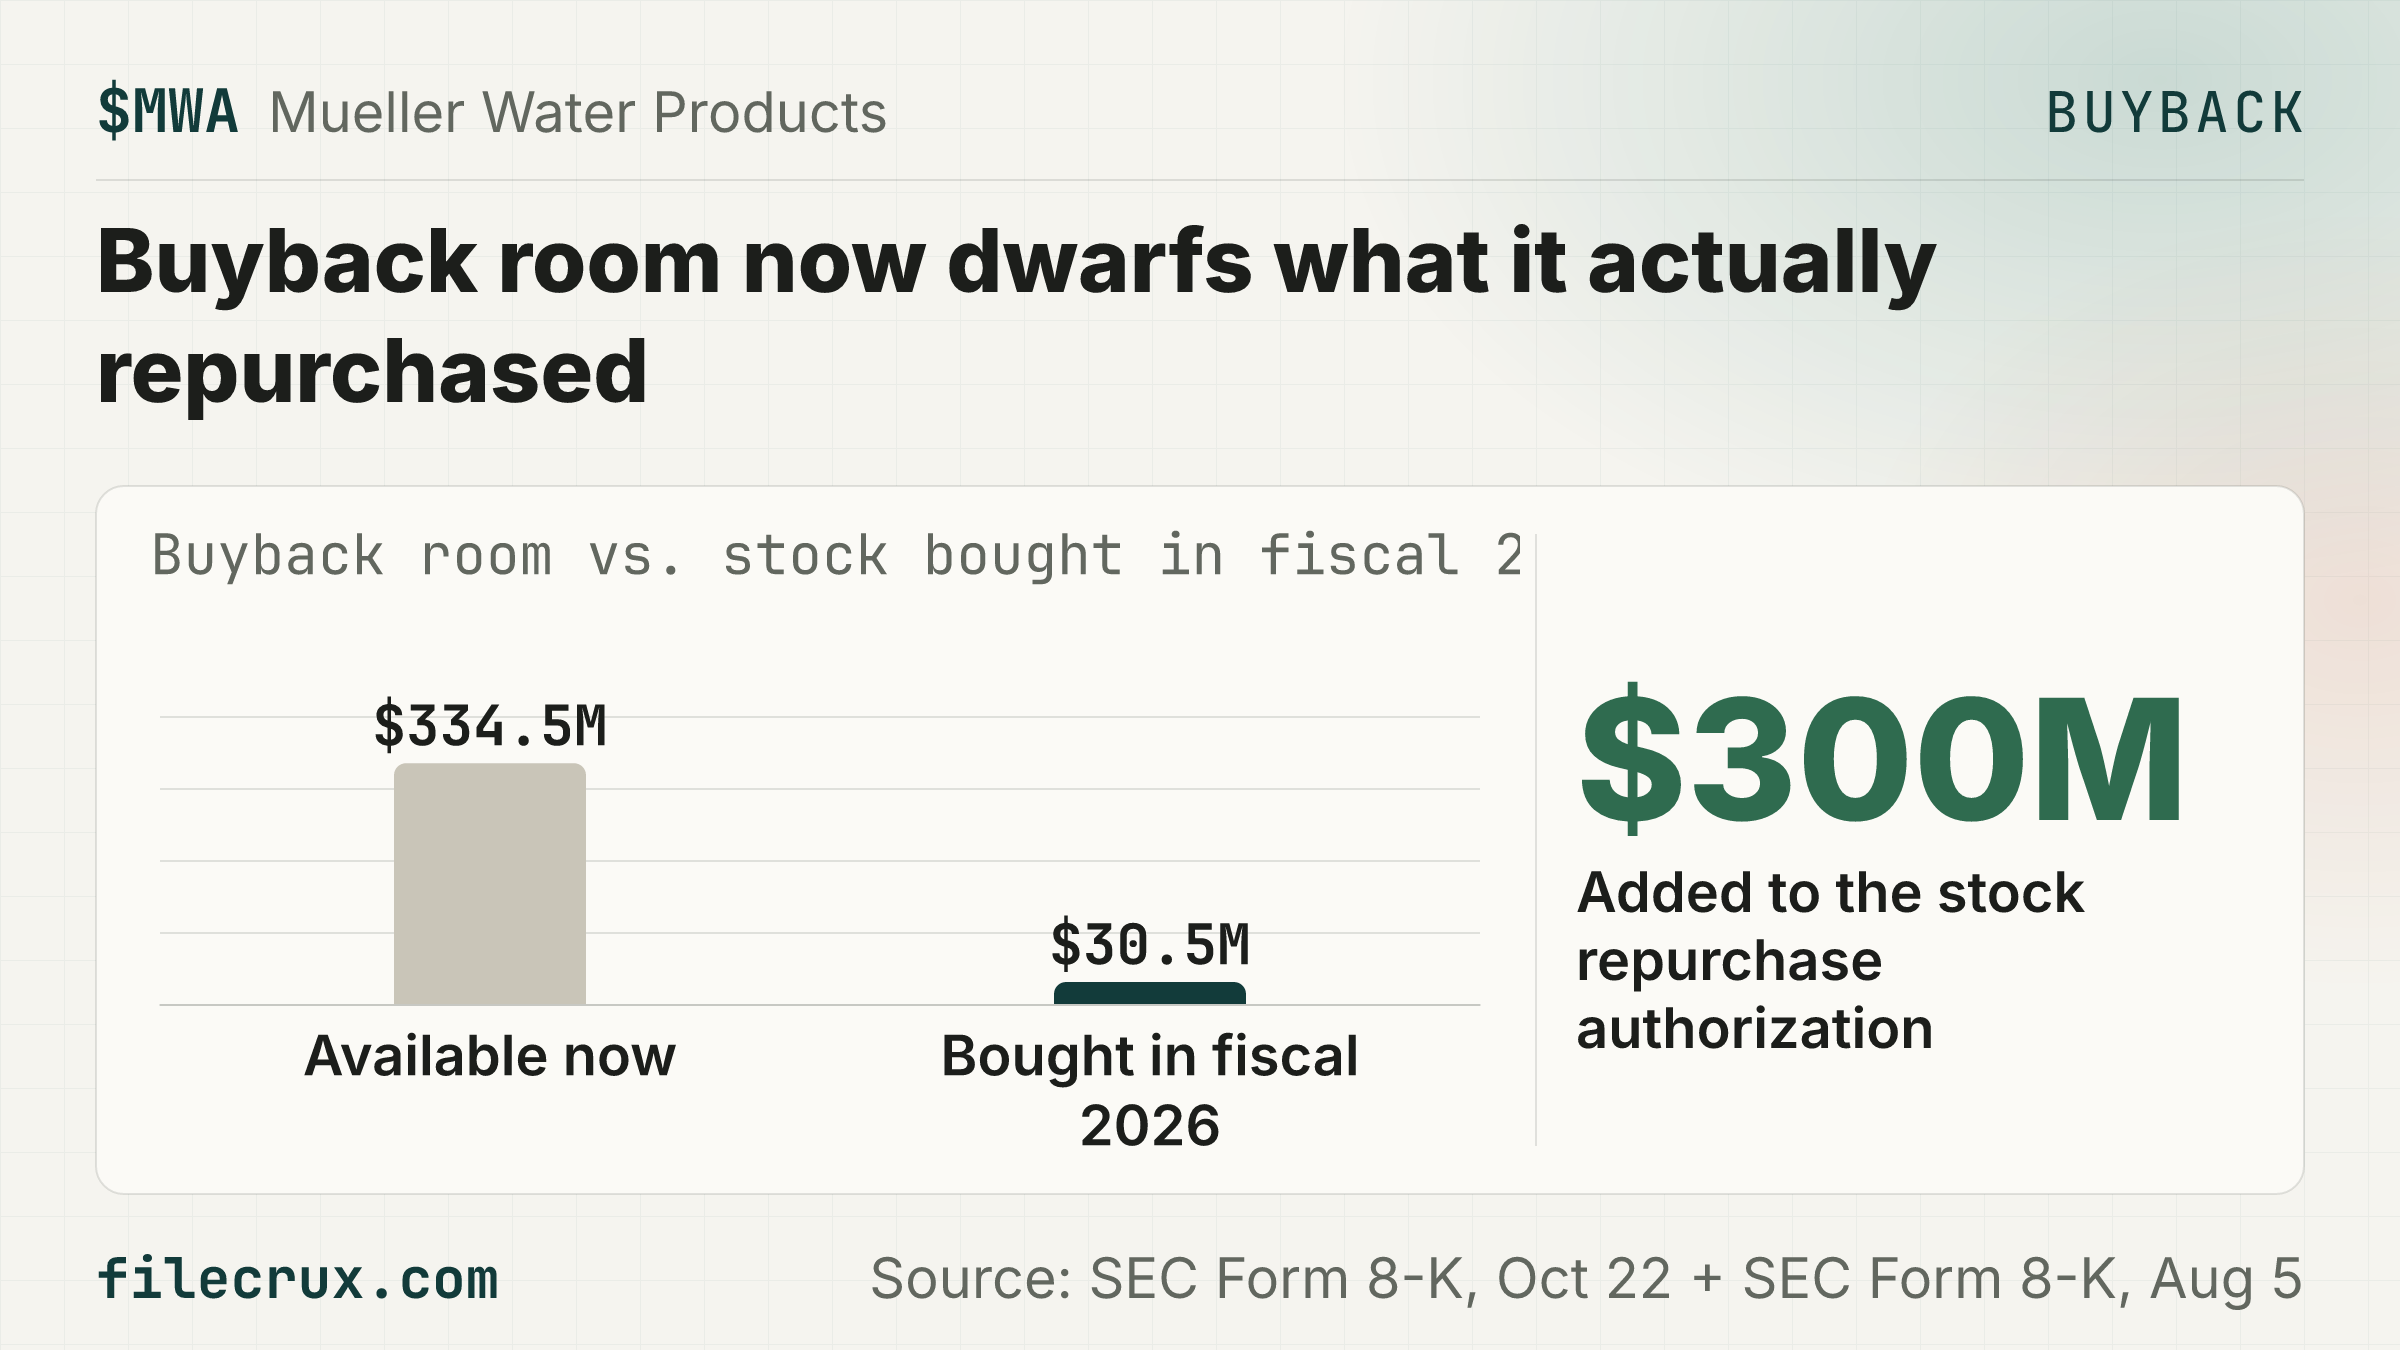
$MWA Mueller Water adds $300M to buyback, lifts dividend 14.3% to $0.08. 🏢 Makes valves, fire hydrants and metering products for North American water systems 💰 $334.5M is now available for buybacks, about 9.6% of its ~$3.48B market value at the $22.28 close, 16:00 ET Oct 22, 2026 ⚠️ It is not an obligation: the company bought only $30.5M of stock in fiscal 2026, and June 30 cash of $495.3M sat against $452.9M of debt 📅 Next: Dividend of $0.08 payable November 19, 2026, to holders of record November 9, 2026 Source: SEC Form 8-K, Oct 22 + SEC Form 8-K, Aug 5
Highlight

Read as text
$SSNC SS&C narrows FY26 adjusted EPS guide up to $7.11–$7.17. 🏢 Financial and healthcare tech provider worth about $20.99B at $89.45 (15:59 ET, Oct 22, 2026) 🚀 July's range was $6.93–$7.25; midpoint rises to $7.14 from $7.09 after Q3 adj. EPS of $1.78, up 14.8% 📉 Q3 organic revenue growth slowed to 5.2% from 7.6% in Q2; Q4 organic guide midpoint is 4.0% 🏦 $2.0B of Senior Notes due Sept 30, 2027 are now current debt vs $525.4M Sept 30 cash; SS&C calls a Q4 refinancing probable 📅 Next: Earnings call 5:00 p.m. eastern time, October 22, 2026 Source: SEC 8-K and earnings release, Oct 22, 2026
Highlight
Read as text
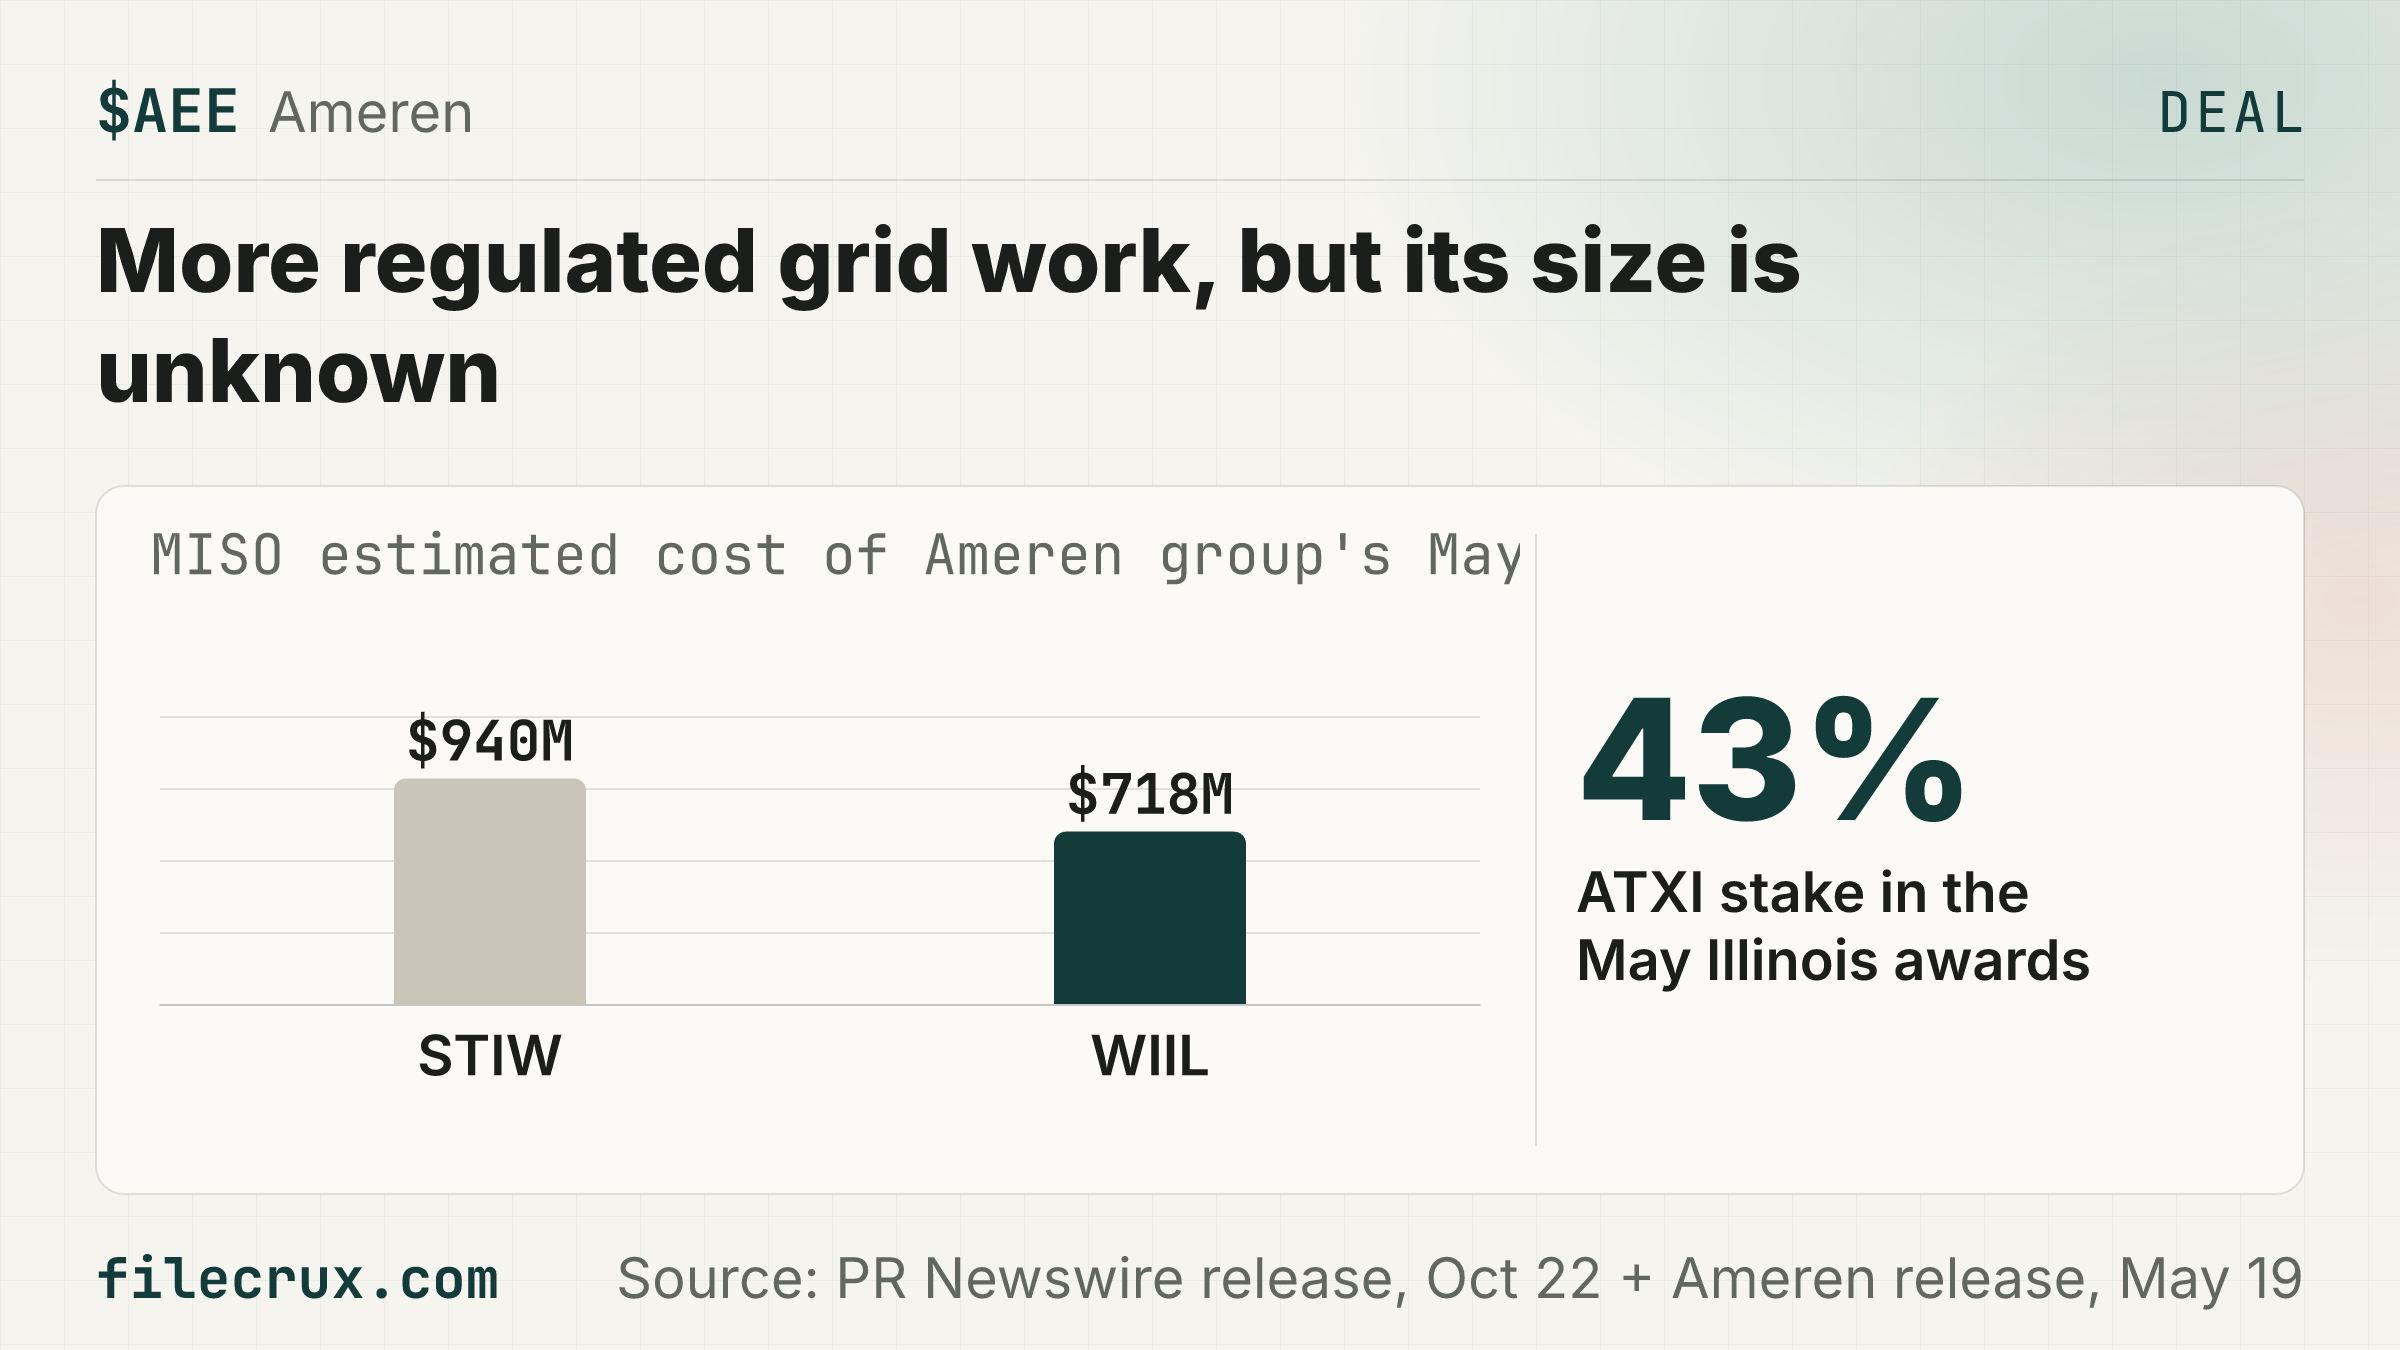
$AEE Ameren group wins MISO's Iowa EASL grid project; cost not disclosed. 🏢 St. Louis-based utility serving 2.5 million electric customers ✅ Partners are NextEra's GridLiance and Dairyland; the release gives no cost, stake or in-service date 🤝 May comparison: ATXI took 43% of two Illinois lines MISO priced at $940M and $718M, about $713M, vs a $30.16B market value at $108.93, 16:00 ET Oct 22, 2026 ⚠️ Shared with two partners; May's lines aren't due in service until 2034 📅 Next: Cost and Ameren's stake still to be disclosed; no date given Source: PR Newswire release, Oct 22 + Ameren release, May 19
Highlight
Read as text
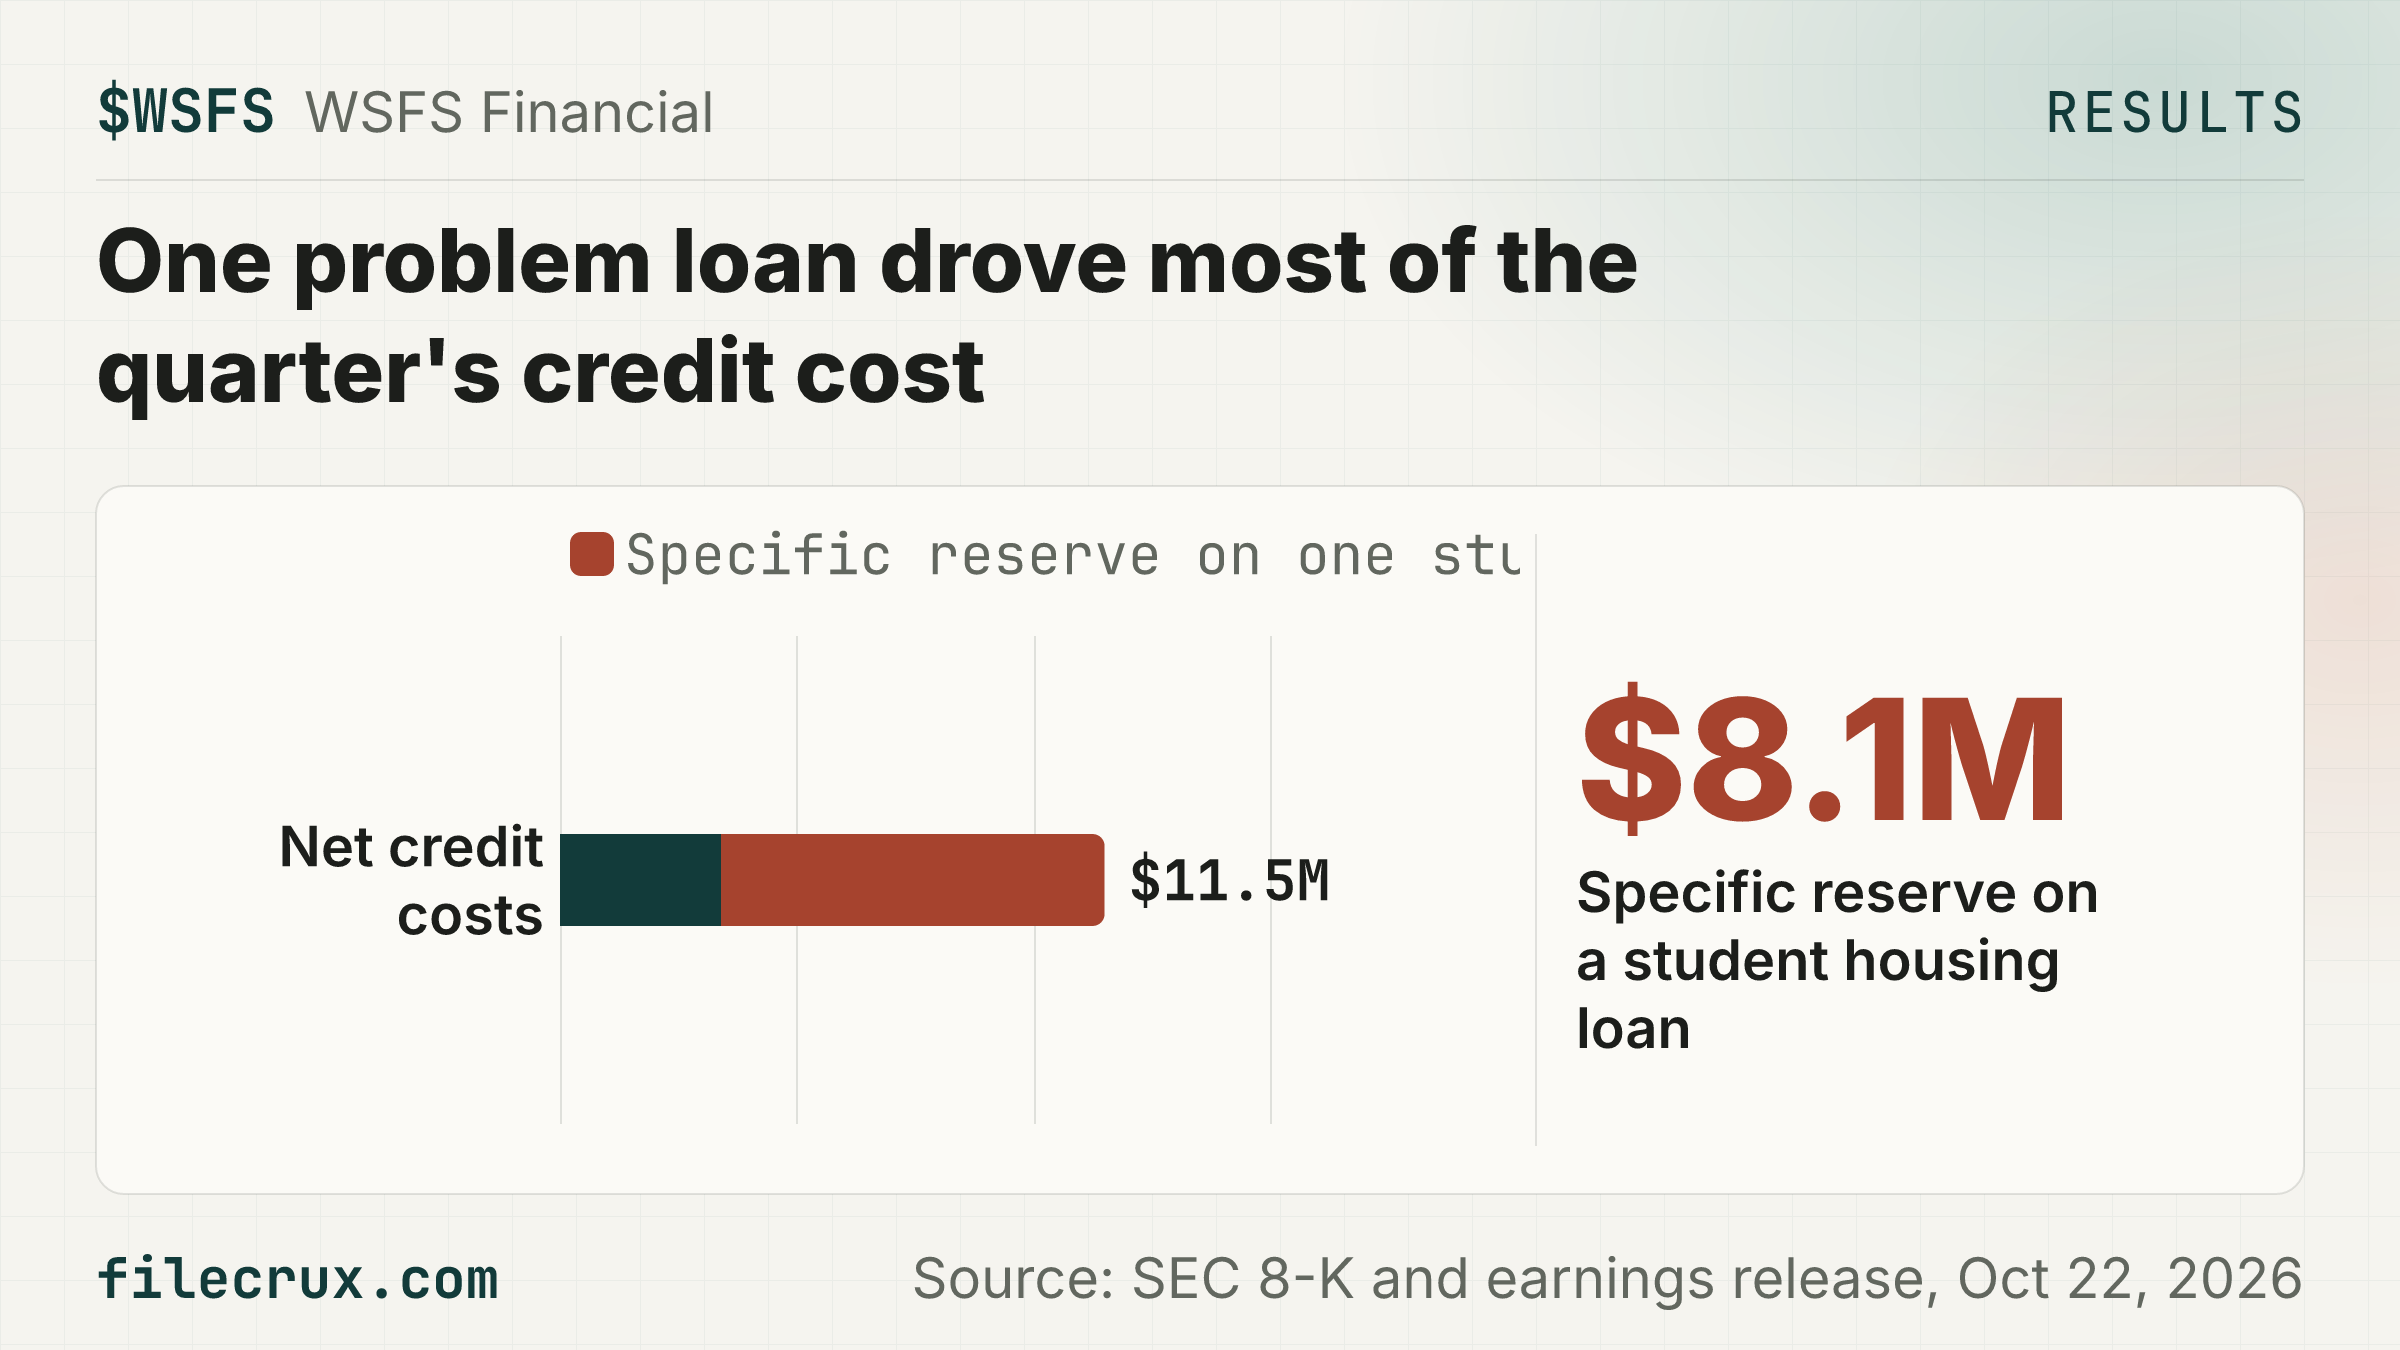
$WSFS 3Q EPS up 27.7% to $1.75, despite an $8.1M reserve on one loan. 🏢 WSFS owns WSFS Bank, a Philadelphia/Delaware bank with $22.1B in assets at Sept 30, 2026 🧾 3Q net credit costs rose $4.4M to $11.5M, driven by an $8.1M reserve on a student housing loan 🏢 That's vs 3Q net income of $89.3M and a ~$3.96B market value at $77.51 (16:00 ET, Oct 22, 2026) ⚠️ Watch: problem assets rose $57.5M vs June 30, 2026, driven by several downgrades, primarily within multifamily and construction 📅 Next: Earnings call 1:00 p.m. ET, Friday, October 23, 2026 Source: SEC 8-K and earnings release, Oct 22, 2026
Highlight

Read as text
$UVE Universal Q3 net income up 31.8% to $52.5M as reinsurance costs eased. 🏢 Fort Lauderdale homeowners insurer worth about $1.35B at $48.34 at 16:10 ET on October 22, 2026 📈 A new reinsurance program from June 1, 2026 cut the ceded premium ratio 5.1 pts to 27.6% from 32.7%, lifting net premiums earned 12.1% to $403.2M ⚠️ Florida premiums written fell 3.3%; Hurricane Isaias hit after quarter end, though claims to date are less significant than initially anticipated 📅 Next: Management webcast 10:00 a.m. ET, Friday, October 23, 2026 Source: SEC 8-K, Oct 22
Highlight
Read as text
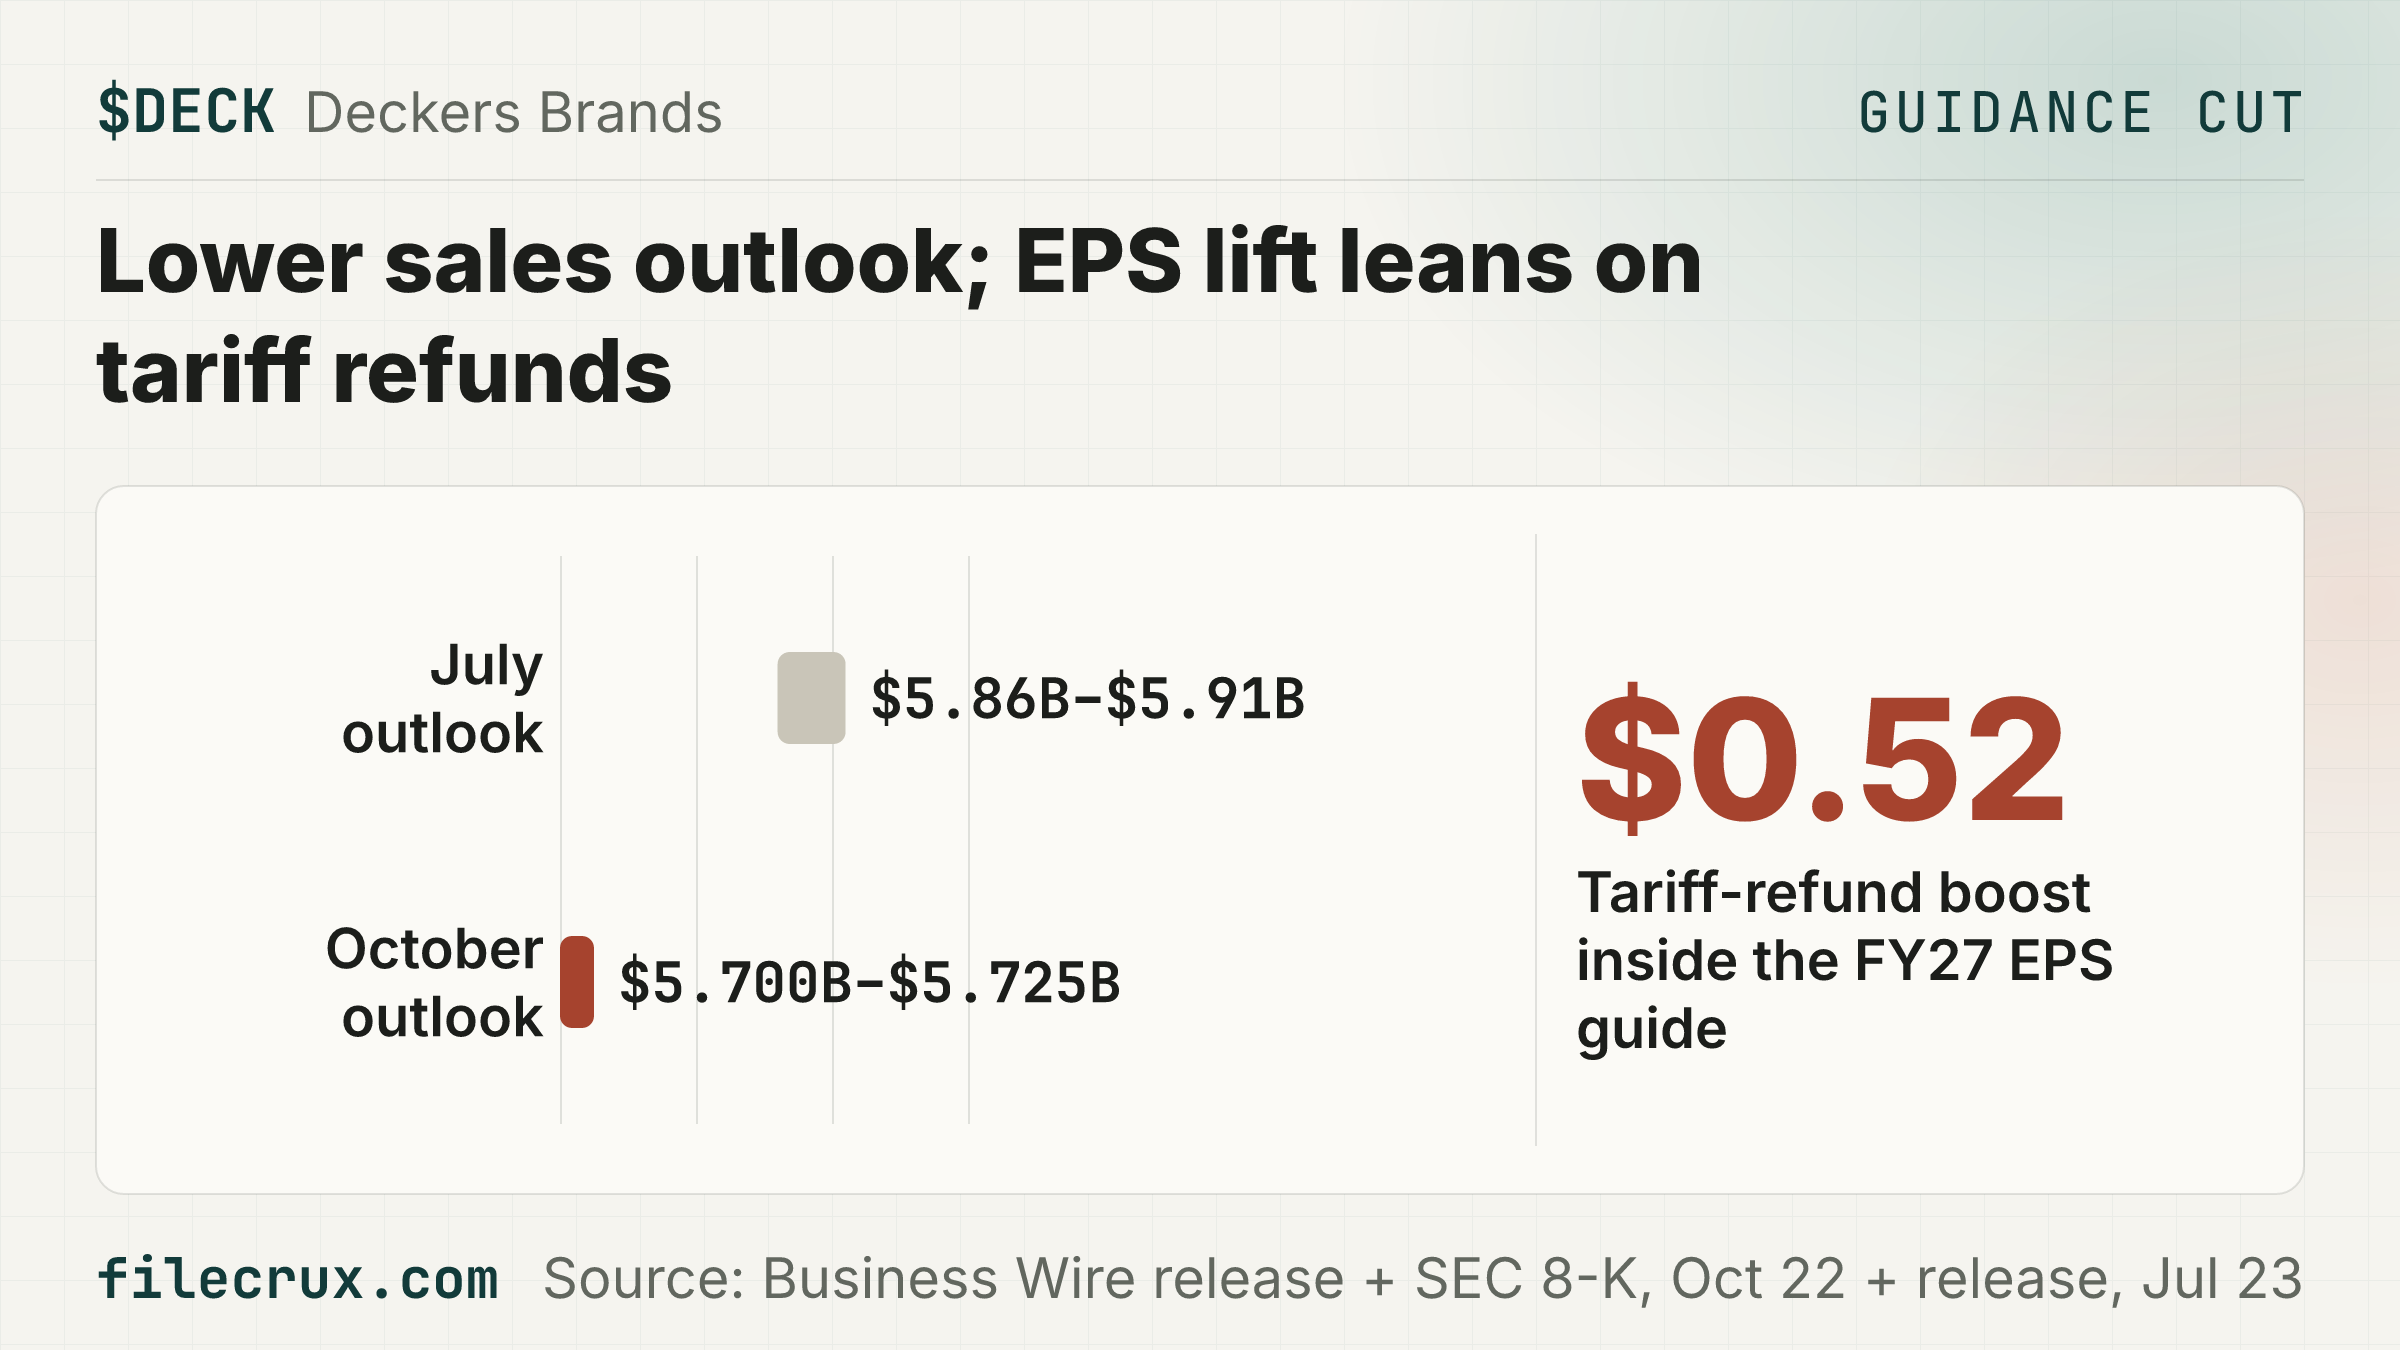
$DECK Deckers cuts FY27 sales guide to $5.700B-$5.725B from $5.86B-$5.91B. 🏢 HOKA and UGG owner; $11.63B market value at $85.245, 16:06 ET Oct 22, 2026 ✂️ HOKA guide now high-single-digit growth vs low-double-digit; UGG low-single-digit vs mid-single-digit ⚠️ EPS guide rose to $7.80-$7.95 on ~$0.52 of tariff refunds; without them ~$7.28-$7.43, below July's $7.35-$7.50 📈 Q2 sales +3.5% to record $1.481B; EPS +27% to $2.31 incl. $0.28 tariff refunds; $637M 1H buybacks, $1.21B cash 📅 Next: Call Thursday, October 22, 2026, at 4:30 pm Eastern Time Source: Business Wire release + SEC 8-K, Oct 22 + release, Jul 23
Highlight

Read as text
$BY Byline Q3 non-performing assets up 21.6% to $87.9M as EPS rises to $0.94. 🏢 Byline Bancorp, a Chicago commercial bank with $9.9B in assets ⚠️ They were 0.89% of assets at Sept 30 vs 0.73% at June 30, mainly from more non-accrual loans ⚠️ $87.9M is ~5% of its $1.72B market value at $37.99 (16:00 ET, Oct 22, 2026); reserves cover 132.87% of bad loans vs 161.91% 🏆 Other side: Q3 net income was a record $41.8M and EPS rose 14.6% from $0.82 a year earlier 📅 Next: Earnings call at 9:00 a.m. Central Time on Friday, October 23, 2026 Source: Byline Q3 release, SEC 8-K, Oct 22, 2026
Highlight
Read as text
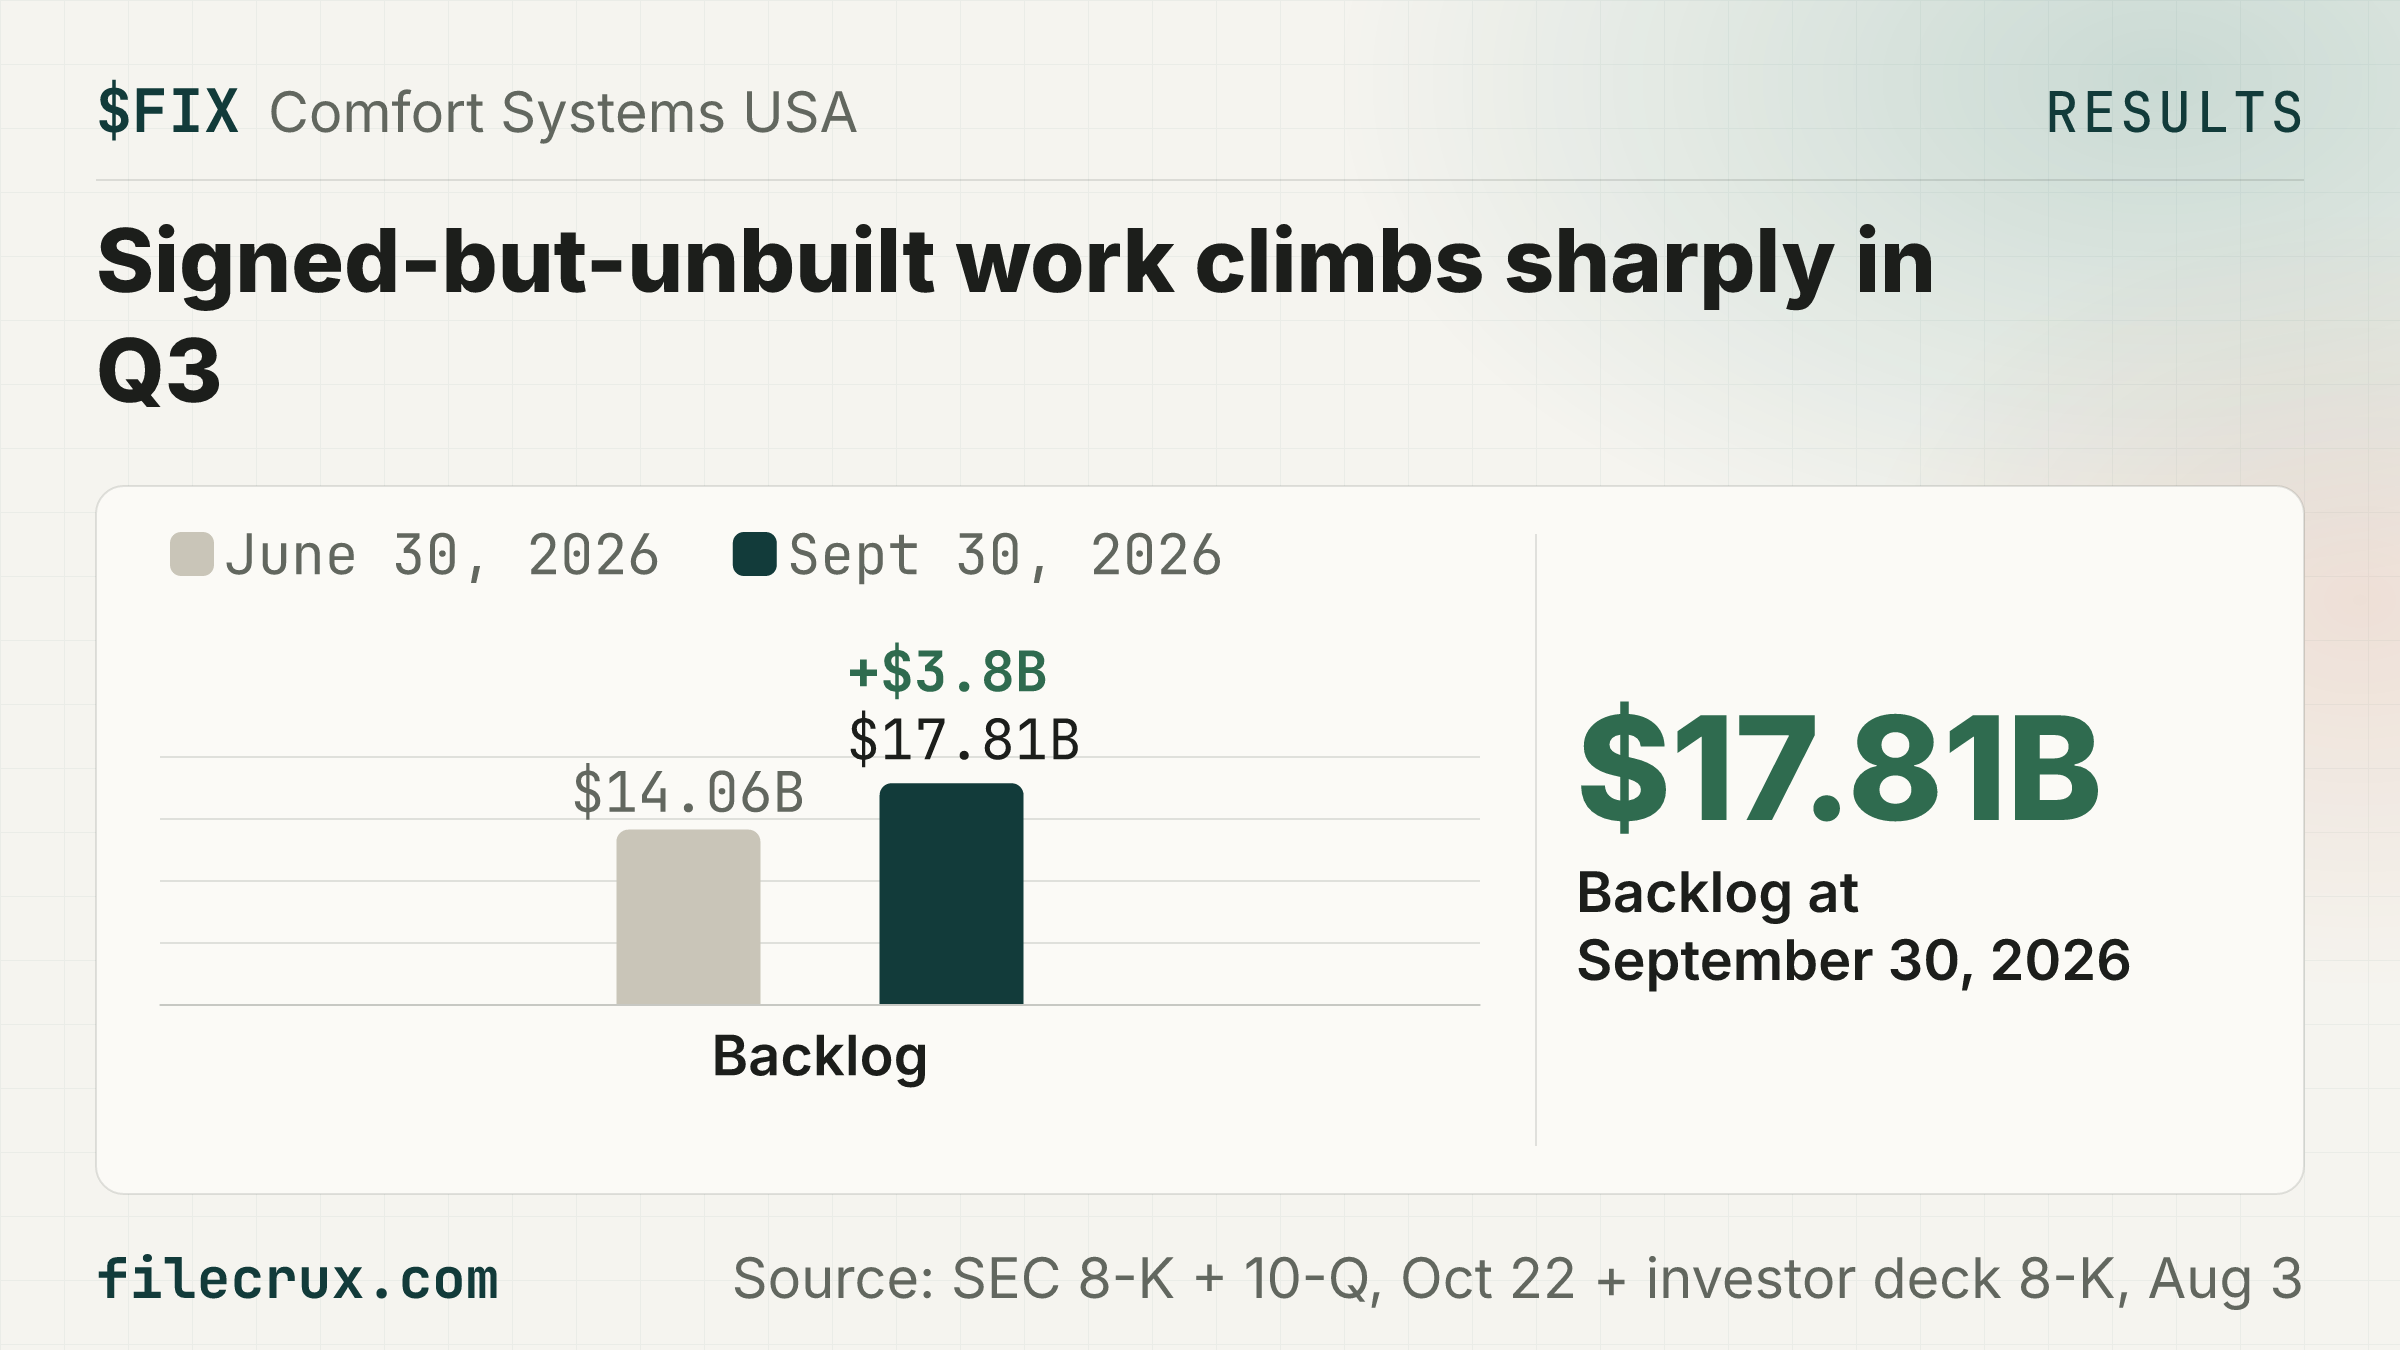
$FIX Comfort Systems backlog jumps $3.8B in one quarter to $17.81B. 🏢 Comfort Systems USA, a US HVAC and electrical contractor, got 58% of H1 2026 revenue from tech work like data centers 📈 Backlog $17.81B Sept 30 vs $14.06B June 30, $3.67B of the rise same-store; market cap $45.02B at $1279.19 (16:21 ET, Oct 22, 2026) 📈 Q3 2026 revenue rose 50% to $3.77B; it sees organic growth into 2027 ⚠️ Backlog can still be cut or cancelled before it becomes revenue, a risk it lists 📅 Next: Call Friday, October 23, 2026 at 10:00 a.m. Central Time Source: SEC 8-K + 10-Q, Oct 22 + investor deck 8-K, Aug 3
Highlight

Read as text
$SIGI Follow-up: Q3 operating EPS up 35% to $2.37 from $1.75; investment income guide raised. 🏢 Selective Insurance Group, a New Jersey P&C insurer worth ~$5.46B at $91.7 (15:59 ET, Oct 22, 2026) 🚀 2026 after-tax investment income guide is now $490M vs $480M; Q3's $127M made 15.2 of 16.9 operating ROE points 📉 Other side: net premiums written fell 7% and total revenue 2% 💰 Dividend up 12% to $0.48; new $200M buyback equals ~3.7% of that $5.46B value, on top of $53M left 📅 Next: Analyst call 8:00 AM ET, Friday, October 23, 2026 Source: SEC 8-K, Oct 22, 2026
Highlight
Read as text
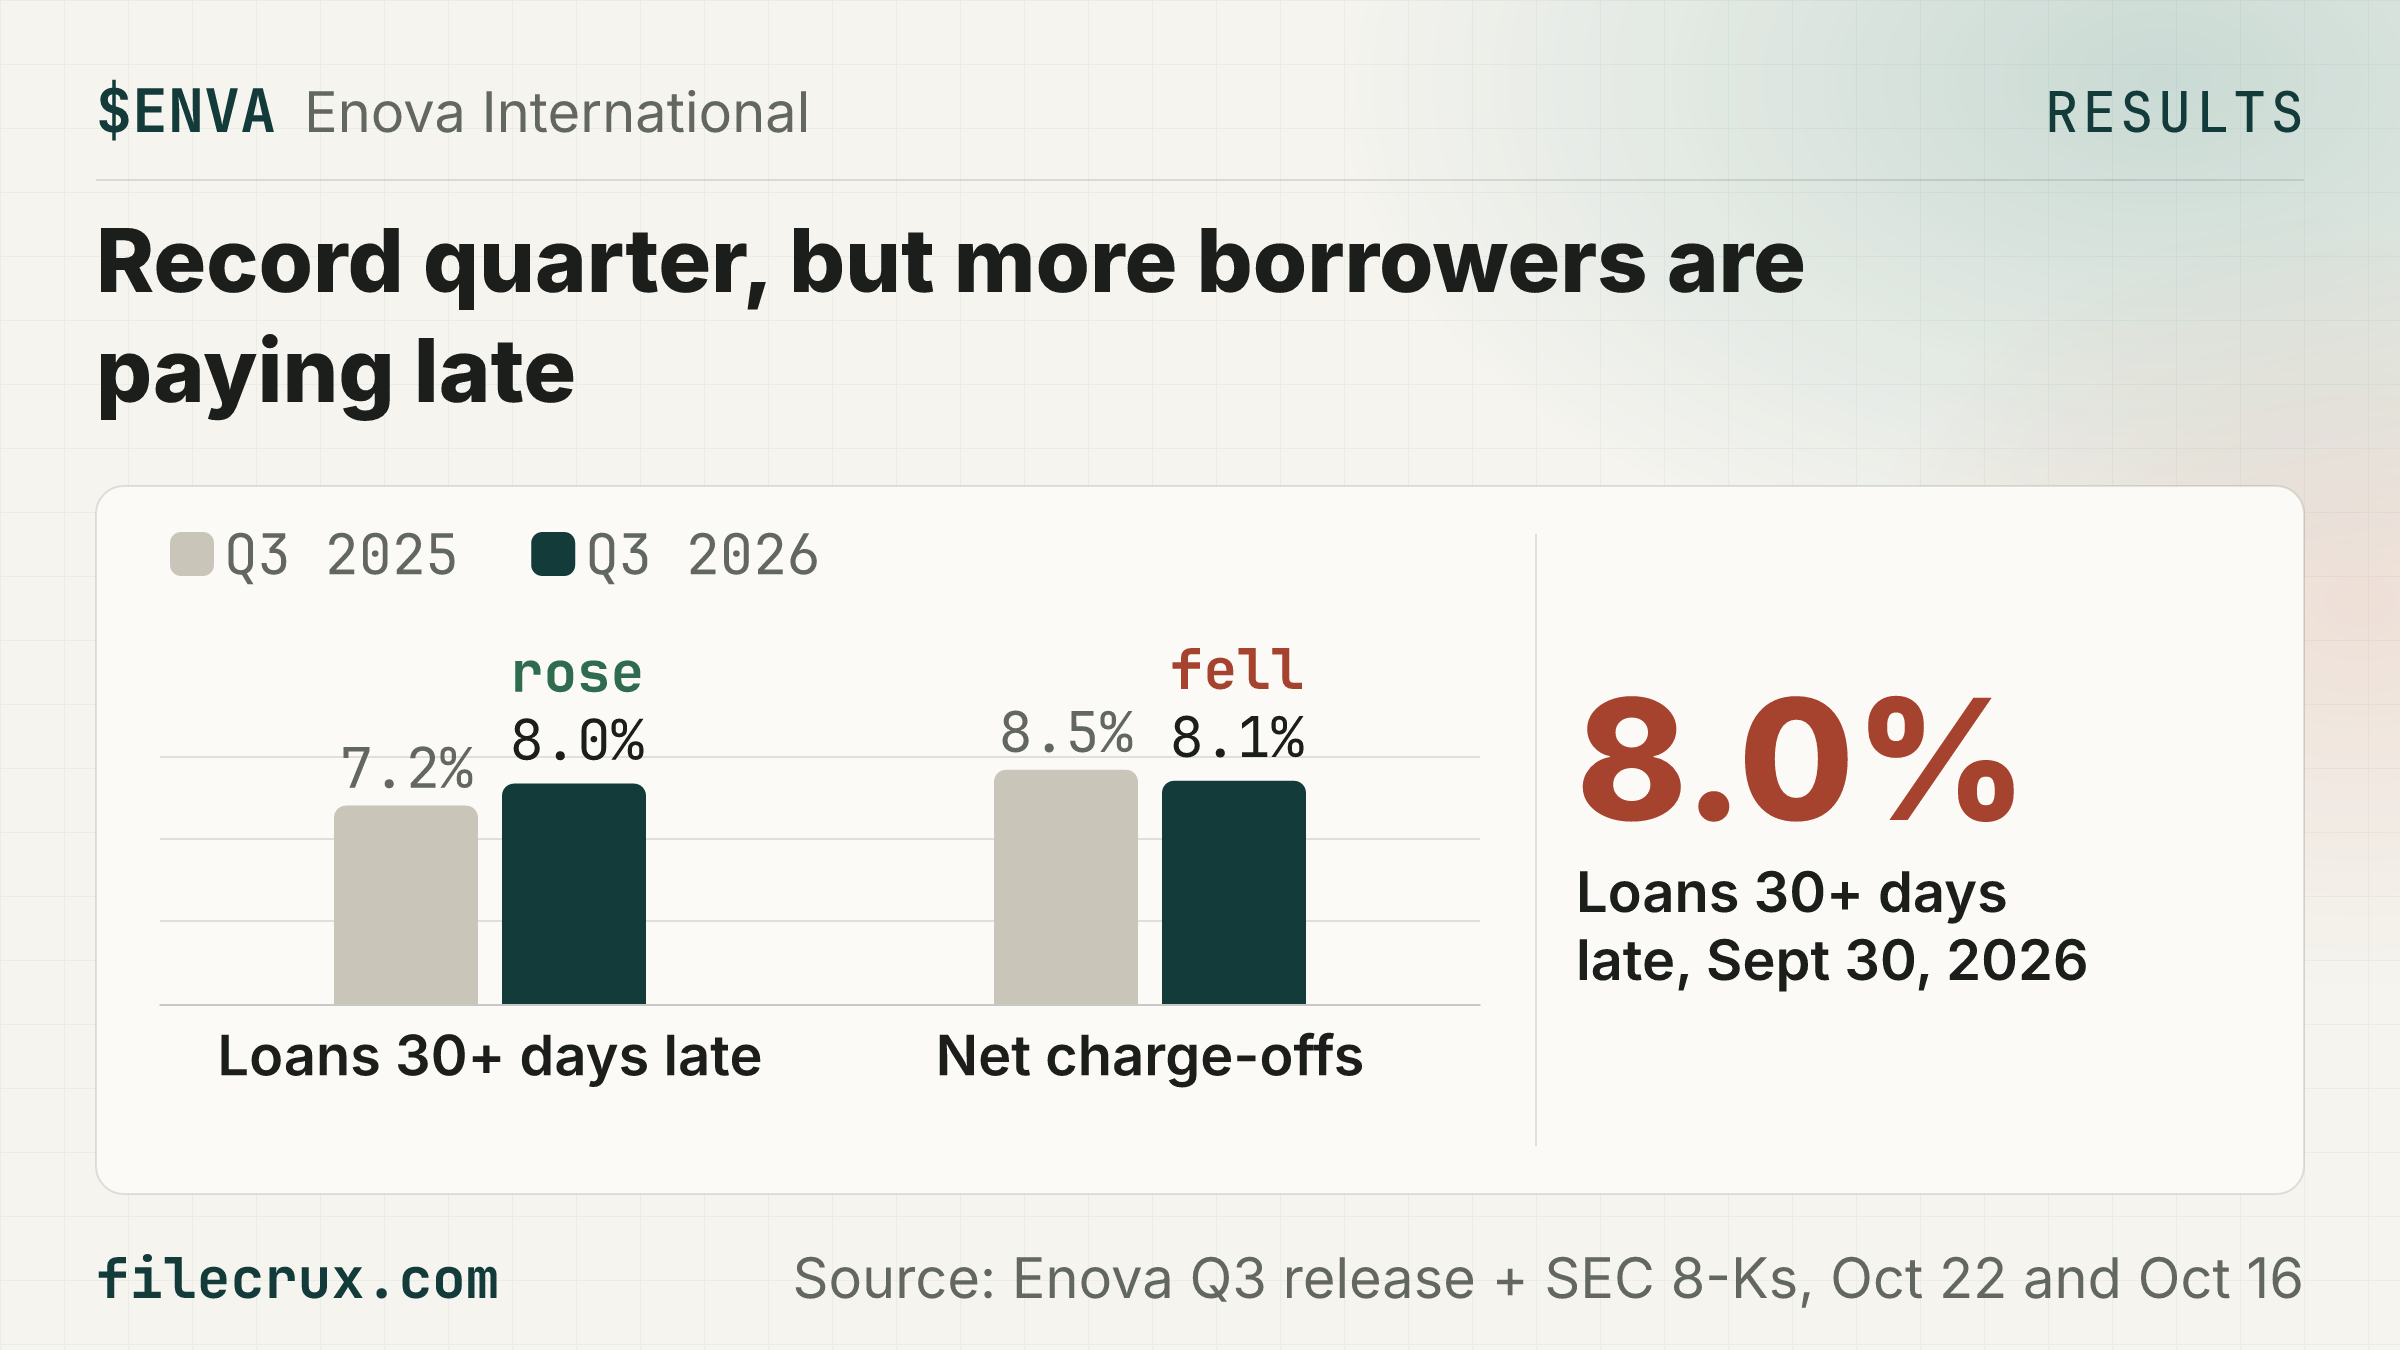
$ENVA Enova tops $1B of quarterly revenue for the first time, up 26% in Q3. 🏢 Online lender to small businesses and consumers; its Oct 16 8-K ended the Grasshopper bank deal for $4M cash ⚠️ Loans 30+ days late hit 8.0% of the book vs 7.2% a year earlier, as receivables grew 30% to $5.9B 📈 Q3 net income rose 34% to $107.3M vs a $4.40B market value at $176.67 (16:00 ET, Oct 22, 2026) 💰 Other side: net charge-offs fell to 8.1% from 8.5%; Enova bought back $46M of stock in Q3 📅 Next: Call 5 p.m. ET, October 22nd; replay until October 29, 2026 Source: Enova Q3 release + SEC 8-Ks, Oct 22 and Oct 16
Highlight

Read as text
$SAM Boston Beer lifts 2026 non-GAAP EPS guide to $9.00-$10.50 from $8.50-$10.50. 🏢 Brewer of Samuel Adams, Twisted Tea, Truly and Sun Cruiser 🚀 The bottom of its 2026 gross margin guide also rose to 49% from 48.5%, after a 51.7% Q3 margin 🏦 Worth about $2.05B at $197.26 a share at 15:59 ET on Oct 22, 2026; $308.1M cash, no debt at Sept 26 ⚠️ 2026 volume guide cut to down mid-single digits from low-to-mid; $194.5M litigation charge accrued, unpaid; post-trial motions, appeals planned 📅 Next: 2027 guidance on the Q4 earnings call in February 2027 Source: GlobeNewswire release + SEC 8-K, Oct 22
Highlight
Read as text
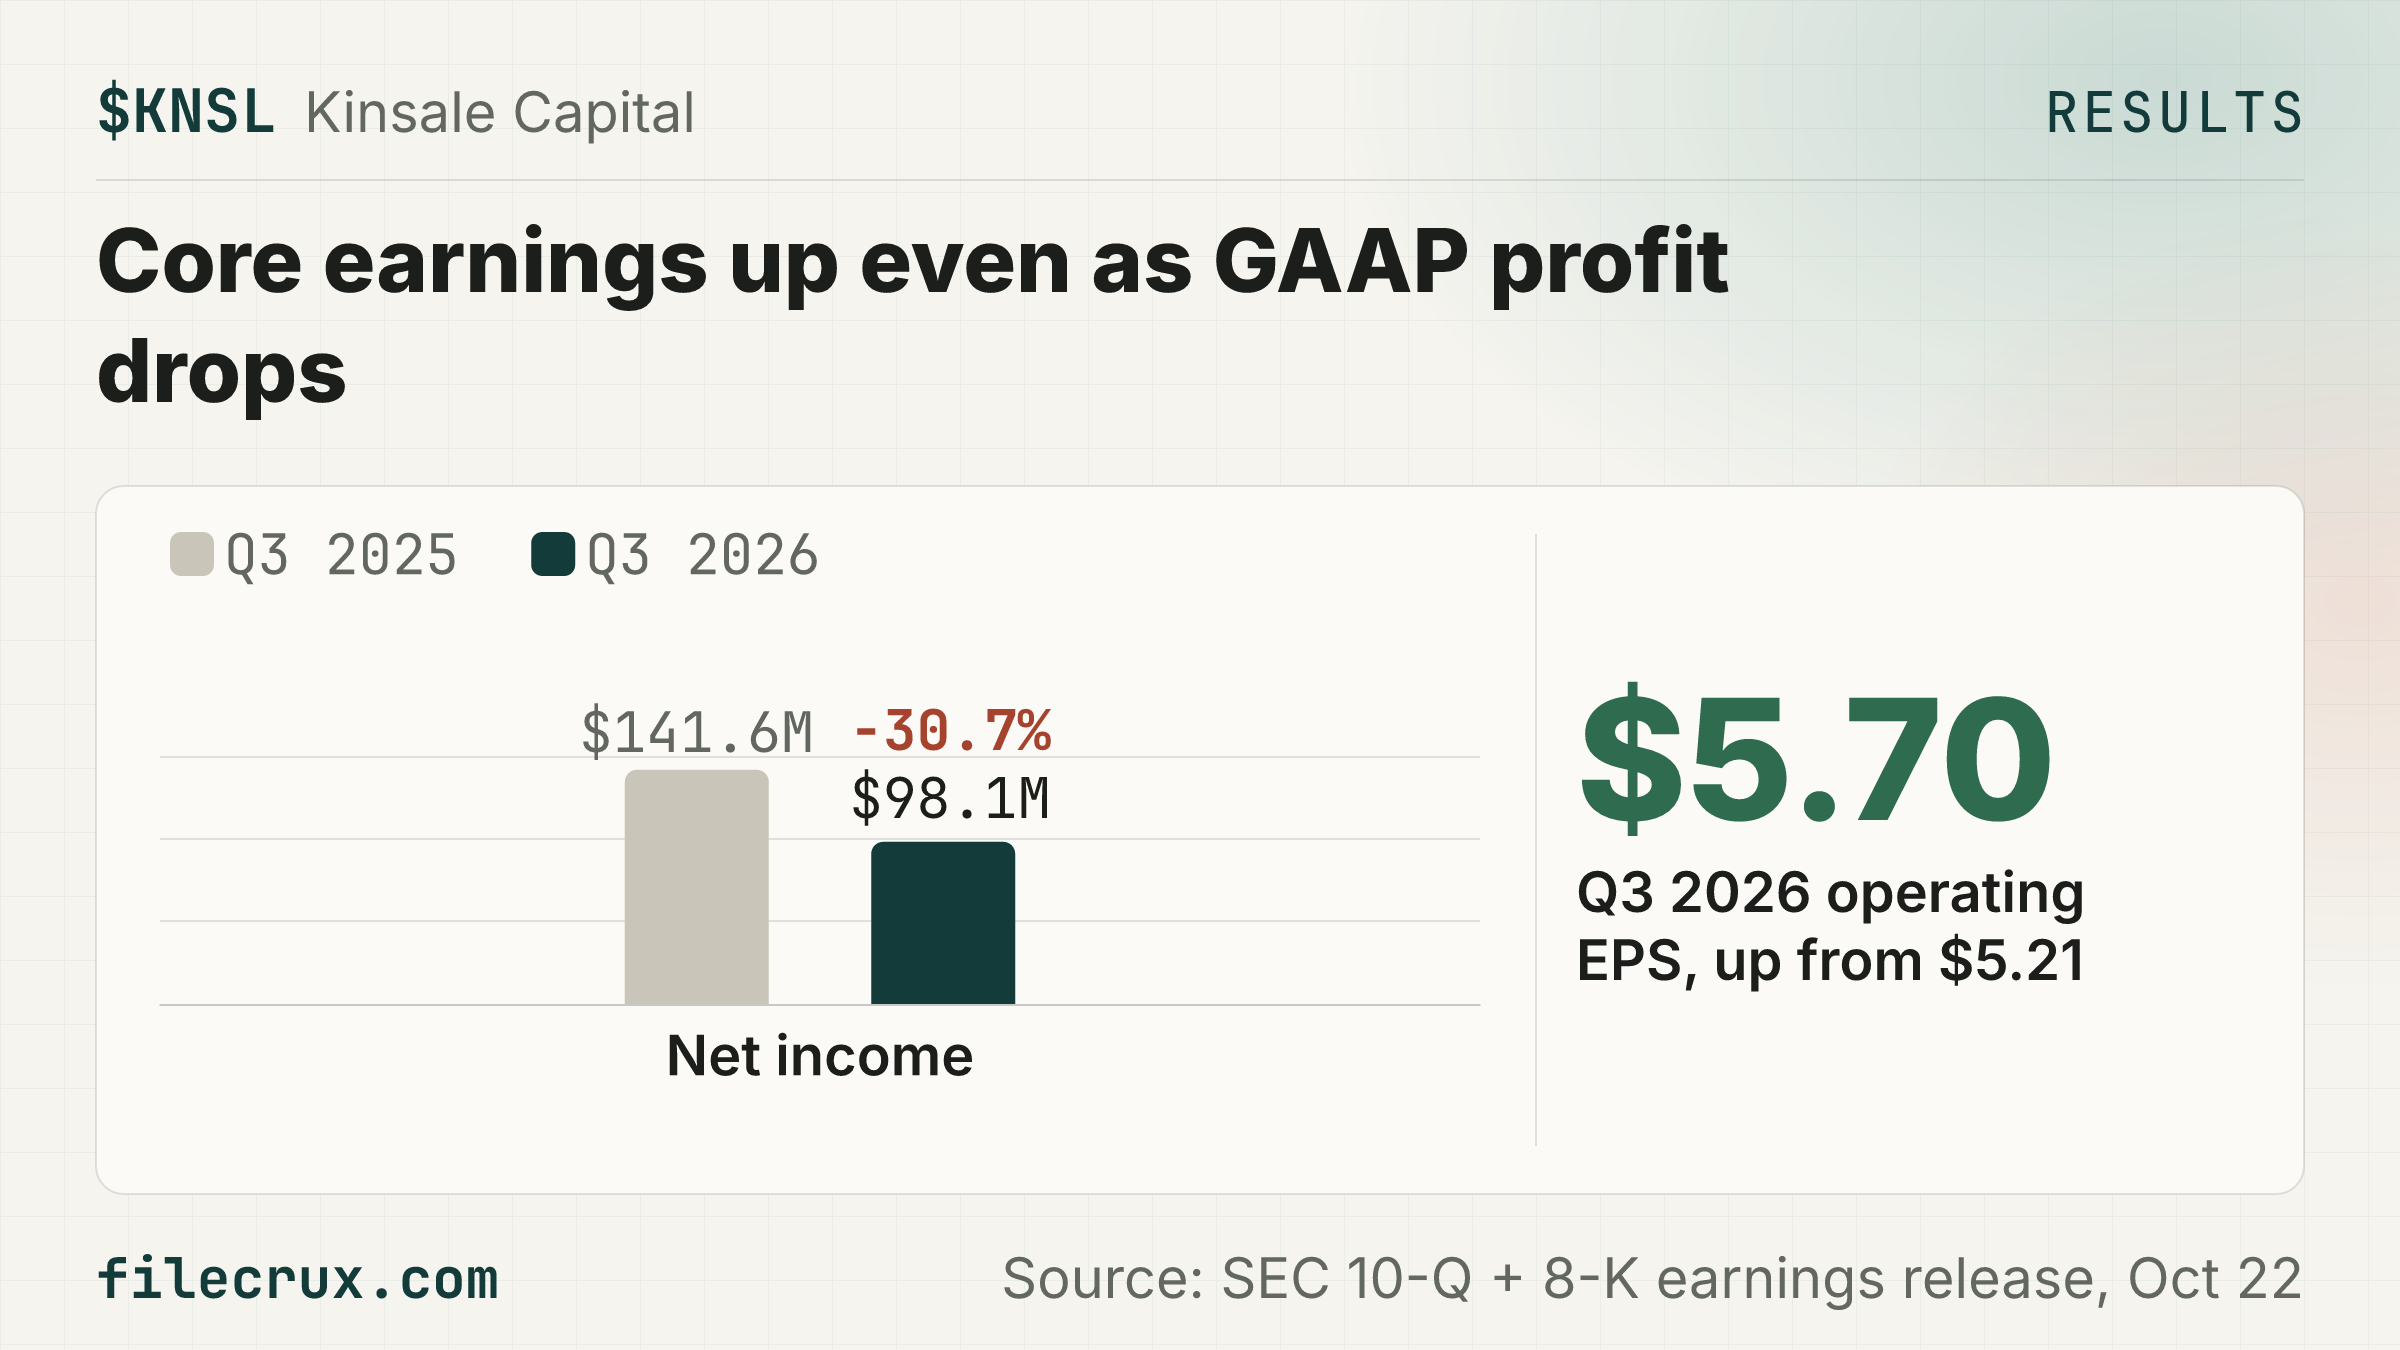
$KNSL Kinsale Q3 net income fell 30.7% to $98.1M from $141.6M, mainly on investment losses vs. prior-year gains. 🏢 Excess and surplus lines insurer worth about $8.90B at $390.65, 16:00 ET Oct 22, 2026 🧾 It sold lower-yielding bonds to buy higher-yielding ones, a $37.6M pre-tax hit to Q3 earnings with no impact to book value, it says 📈 Q3 operating EPS, excluding investment gains and losses, rose to $5.70 from $5.21 📉 Gross written premiums fell 4.8% to $462.9M; property fell 19.3% 📅 Next: Call Friday, October 23, 2026 at 9:00 a.m. (Eastern Time) Source: SEC 10-Q + 8-K earnings release, Oct 22
Highlight

Read as text
$SEZL Sezzle files with the OCC to charter Sezzle Bank, N.A. 🏢 Buy-now-pay-later fintech whose loans partner WebBank originates and funds 🏦 It also applied for FDIC deposit insurance and will apply to the Fed to become a bank holding company 🏢 Worth about $4.69B at $139.36 (15:59 ET, Oct 22, 2026) with $79.8M cash at June 30, 2026; no bank capital figure given ⚠️ Approval isn't guaranteed and WebBank stays exclusive loan originator under a program running to September 27, 2029 📅 Next: Q3 2026 results after the market close on November 4, 2026 Source: GlobeNewswire release, Oct 22 + SEC 8-Ks
Highlight

Read as text
$SRCE 1st Source Q3 2026 net income rose 17.13% to a record $49.54M from $42.30M a year ago. 🏢 Parent of 1st Source Bank, a South Bend, Indiana lender with $9.34B in assets at Sept 30, 2026 📈 Diluted EPS $2.03 vs $1.71 a year earlier, as tax-equivalent margin widened 19bp to 4.28% 🏢 Market value about $2.10B at $87.12 a share, 15:59 ET Oct 22, 2026 ⚠️ Deposits lag: Q3 avg $7.44B, up 0.27% y/y vs loans' 3.42%, as brokered deposits fell 41.12% 📅 Next: $0.45 dividend, up 5 cents or 12.50% from the one declared a year ago, paid November 13, 2026 Source: 1st Source release via SEC 8-K, Oct 22, 2026
Highlight

Read as text
$NEM Newmont lowers 2026 all-in cost guidance to $1,520 an ounce. 🏢 The only gold producer in the S&P 500 🚀 Full-year cash cost (CAS) guidance also improves to $925/oz, on cost discipline and higher co-product prices 📈 Q3 free cash flow was $1.9B, against a market value of about $120.03B at $113.91 a share, 16:15 ET Oct 22, 2026 ⚠️ Q3 all-in cost was $1,454/oz, but Q4 is guided at $1,900/oz and Newmont expects 2027 unit costs to trend higher 📅 Next: $1.95B to Barrick expected in Q4 as amended Nevada Gold Mines JV adds Fourmile, Fiberline and Mike Source: Newmont Q3 release, SEC 8-K, Oct 22, 2026